Paid Cash? How to Prove Income to a Lender
Paid in cash and facing an income check? Learn which records prove your earnings and how to build a paper trail lenders accept.
By Thomas Young
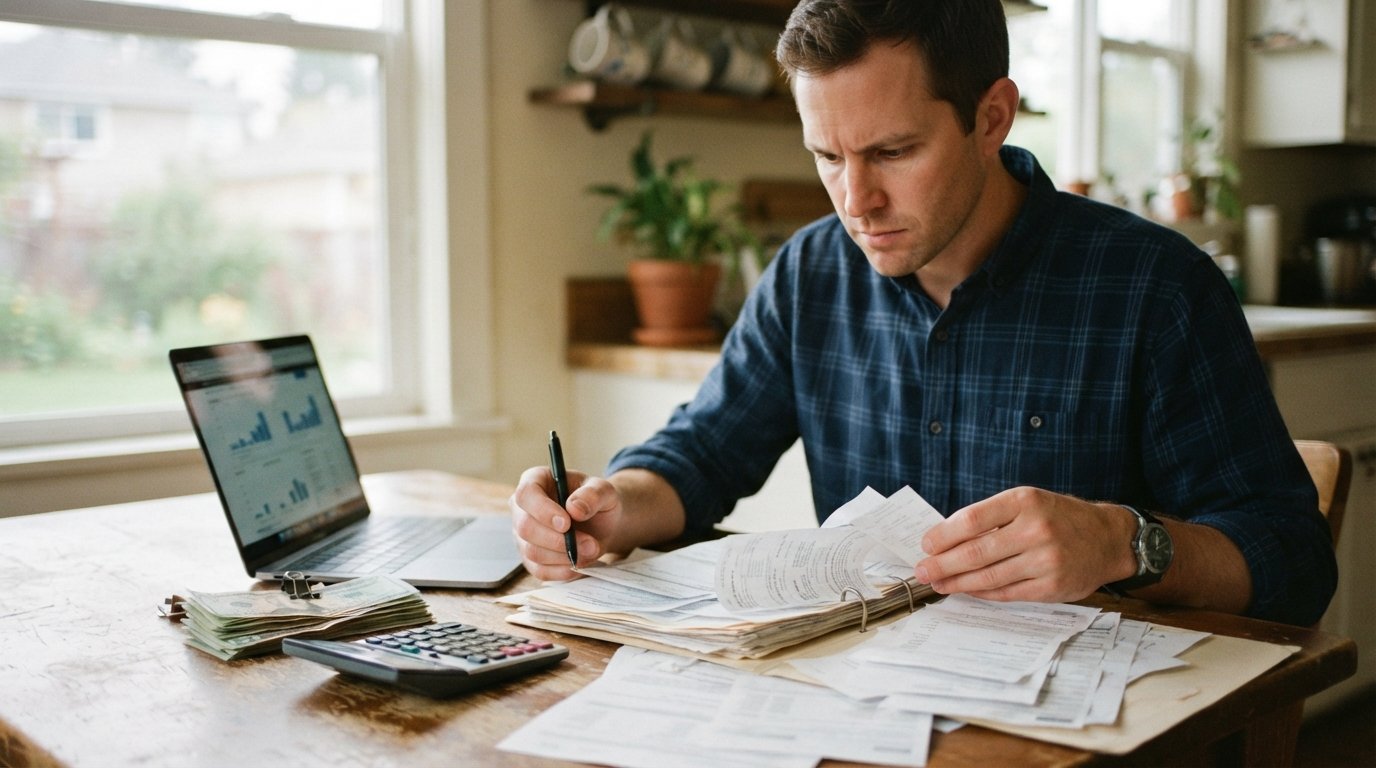
You have steady work, money coming in every week, and a lender asks for proof of income. The problem: you get paid in cash, so there are no pay stubs to hand over. This situation is far more common than most borrowers realize, and it does not automatically disqualify you from a loan. Lenders understand that plenty of people work in cash based jobs, from construction and landscaping to gig work and small side businesses. What they need is evidence that the money is real, consistent, and likely to continue. Your job is to assemble that evidence before the application conversation gets uncomfortable. This guide walks you through what to do when a lender asks for proof of income and you are paid cash, including which records carry weight, how to build a paper trail quickly, and what to say when documentation is thin.
Why Lenders Ask for Proof of Income at All
Before you panic about the lack of pay stubs, it helps to understand what the lender is actually trying to measure. Income verification exists to answer one question: can this person realistically repay the loan? Lenders use proof of income to calculate a debt to income ratio, confirm that your earnings are stable, and satisfy their own compliance requirements. Traditional proof means recent pay stubs, W-2s, or tax returns. When those do not exist, most lenders will accept alternative documentation that serves the same purpose.
This is especially true for short term lending products. A payday loan, for example, is typically a small, short term advance backed by future income, and the lender mainly needs to see that a paycheck or regular deposit is coming. Installment loans and personal loans involve larger amounts and longer repayment schedules, so the verification tends to be more thorough. Knowing which type of loan you are applying for tells you how much documentation you will likely need to produce.
The key insight is that lenders are not looking for a specific form. They are looking for a pattern. If you can show a consistent flow of money into your life, you have satisfied the spirit of the requirement even without a formal pay stub.
Records That Can Serve as Income Proof for Cash Work
Cash earners have more usable documentation than they often think. The trick is to gather several types of records that corroborate each other. A single bank statement might raise questions, but a bank statement plus invoices plus a client letter tells a coherent story. Start by pulling together everything you already have, then fill gaps as needed.
- Bank statements: Three to six months of statements showing regular deposits, even if those deposits are cash. Consistent deposit amounts and dates create a visible earnings pattern.
- Invoices and receipts: Copies of invoices you issued to clients, along with receipts for cash payments received, establish that you performed paid work.
- Tax returns and 1099 forms: If you reported your cash income, your tax return is among the strongest proofs available. A 1099 from a client works the same way a W-2 does.
- Client or employer letters: A signed letter describing your work arrangement, pay rate, and how long you have worked there adds credibility.
- Appointment books and job logs: Records showing dates, clients, and amounts charged demonstrate an active, ongoing operation.
Each of these documents is stronger when it overlaps with another. A bank statement showing a $600 deposit on the same date as a $600 invoice is far more persuasive than either document alone. Assemble your records chronologically so the lender can follow the trail without effort.
Using Bank Deposit History and Invoices Effectively
Bank deposit history is the backbone of cash income verification. Lenders can see exactly when money entered your account, how often, and in what amounts. If you deposit your cash earnings regularly rather than spending them directly, your statements become a de facto income record. The pattern matters more than any single deposit: weekly deposits of similar size read as a paycheck, while sporadic large deposits raise questions.
Invoices do a different job. They prove that the money came from work rather than from a gift, a transfer between accounts, or a loan. When you present bank statements alongside matching invoices, you close the loop. For self employed borrowers, this pairing is often the difference between approval and denial. If you have not been issuing invoices, start now, even for small jobs. A simple numbered invoice with your name, the client, the date, the service, and the amount takes two minutes to create and pays off at application time.
One practical tip: deposit cash consistently and keep the deposit slips or mobile deposit confirmations. If a lender asks why a deposit appears, you can point to the specific job that generated it. This level of detail signals reliability and makes the underwriter's job easier, which tends to work in your favor.
How Self Employed Applicants Are Evaluated
Self employed applicants go through a slightly different evaluation than salaried workers. Lenders know that income can fluctuate, so they look for average earnings over time rather than a single month. Expect them to review several months of records, calculate an average monthly income, and assess whether that average comfortably covers the proposed loan payment plus your existing obligations.
The evaluation usually weighs three factors: consistency, documentation, and plausibility. Consistency means your income arrives regularly. Documentation means you can back up your numbers with records. Plausibility means the stated income makes sense for the type of work you do. A landscaper claiming $8,000 a month with no invoices or deposits will not pass the plausibility test, but the same worker with six months of steady deposits and client records will.
If you operate under a business name, bring any business registration, a business bank account statement, or a Schedule C from your tax return. These establish that your cash work is a legitimate operation, not casual under the table income. Even a simple sole proprietorship registration strengthens your file. For borrowers who are exploring cash loan lenders in Houston Texas, the same documentation principles apply regardless of the lender you choose.
Building a Paper Trail Before You Apply
The best time to build income documentation was six months ago. The second best time is today, before you submit an application. If your records are thin, spend a few weeks creating a trail that a lender can follow. This is not about fabricating anything; it is about capturing the economic activity you are already generating.
- Open a dedicated bank account and deposit all cash earnings there. Even if you withdraw cash for expenses later, the deposits create a visible record.
- Start issuing invoices for every job. Number them sequentially and keep copies. Send them by email or text so there is a timestamped record.
- Write down your work schedule and client list. A simple log of dates, clients, and amounts builds a narrative that supports your bank deposits.
- Set aside money for taxes and file a return. A filed tax return showing self employment income is one of the most persuasive documents you can present.
- Ask long term clients for brief letters. A short note confirming your work relationship and typical pay adds a human element that underwriters appreciate.
Once these pieces are in place, your application file transforms. Instead of saying "I get paid in cash" and hoping for the best, you can hand over a folder or a set of PDFs that tells a complete story. Lenders respond to organization. A well prepared applicant with modest income often beats a disorganized applicant with higher income.
Options if Documentation Is Thin
Sometimes you need money before the paper trail is ready. If your documentation is genuinely thin, you still have options. The first is to be honest with the lender about your situation and ask what alternatives they accept. Many lenders have specific policies for cash workers and will tell you exactly which documents they need. Hiding the lack of pay stubs only wastes everyone's time.
The second option is to work with a lending platform that connects you to multiple lenders with varying documentation requirements. A matching service lets you submit one request and review offers from lenders who may be more flexible about alternative income proof. Platforms like ExpressCash connect borrowers with third party lenders who offer short term options, and the application process is designed to be fast and fully online. Because different lenders have different criteria, your chances improve when you can compare several offers rather than relying on a single lender's decision.
The third option is to strengthen your application with a co borrower or collateral, if the loan type allows it. A co signer with verifiable income can offset concerns about your documentation. Not every short term loan product permits this, but it is worth asking. Finally, consider whether a smaller loan amount would reduce the documentation burden. A $300 advance may require far less proof than a $5,000 personal loan, and a smaller loan can bridge your gap while you build records for a larger application later.
What to Say When the Lender Asks
How you present your situation matters as much as the documents themselves. When the lender asks for proof of income, respond directly and confidently. Explain that you are paid in cash, describe your work, and immediately offer the records you have. A statement like "I work in landscaping and get paid per job. Here are six months of bank statements showing my deposits, my invoices for the last three months, and a letter from my main client" answers the question before doubt can set in.
Avoid apologizing for being paid in cash or acting as though you have done something wrong. Cash work is legitimate work, and lenders encounter it constantly. What they want is transparency and evidence, not embarrassment. If a particular document is missing, say so and offer a substitute. Underwriters are trained to evaluate alternative documentation, but they can only do that if you give them the chance.
Keep your records updated as well. If you apply again in six months, your file should be stronger, not identical. Every deposit, invoice, and client letter you add makes the next application easier. Over time, the cash income question stops being an obstacle and becomes a routine part of your financial profile.
Final Thoughts on Cash Income and Lending
Being paid in cash does not close the door to borrowing. It simply changes the paperwork. Lenders want to see consistent, documented income, and there are many ways to demonstrate that beyond a pay stub. Bank statements, invoices, tax returns, client letters, and work logs all serve the same purpose: they show that money arrives regularly and that you can repay what you borrow. Start building your paper trail now, present it clearly when asked, and be upfront about your situation. With the right records and the right lender, cash income becomes a manageable detail rather than a barrier.