How to Pay for an Emergency Root Canal or Crown Without Insurance
Facing an urgent root canal or crown without insurance? Explore dental schools, payment plans, and short-term loans to cover the gap and avoid bigger bills.
By Olivia Reed
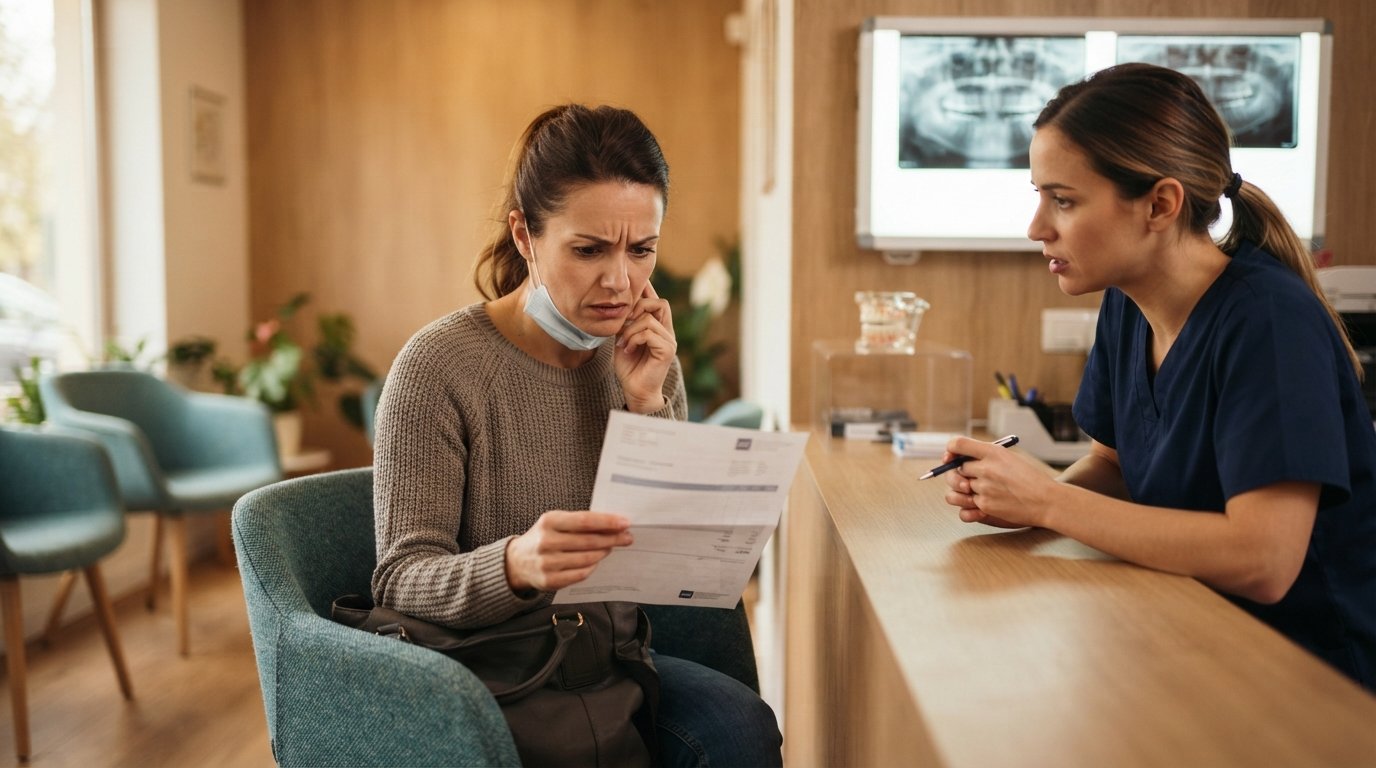
A throbbing toothache at 2 a.m. rarely comes with a convenient price tag. When the dentist says you need a root canal or a crown and you have no dental insurance, the cost can feel like a second emergency. A root canal alone can run $700 to $1,500, and a crown can add another $800 to $2,000. Facing that bill without coverage is stressful, but you have more options than you might think. This guide walks you through realistic ways to pay for an emergency root canal or crown without insurance, from negotiating with your dentist to using short-term funding wisely.
Before you panic or delay treatment, know that delaying a root canal can lead to a more serious infection, extractions, or even hospital visits that cost far more. The key is to act quickly and explore every financial avenue. Below, we break down the costs, the first stops for help, how to negotiate a payment plan, when a short-term loan makes sense, and how to avoid high-cost borrowing for elective add-ons. By the end, you will have a clear roadmap for handling the bill without insurance.
Typical Out-of-Pocket Costs for Urgent Dental Procedures
Dental costs vary widely depending on your location, the tooth involved, and whether you see a specialist. A root canal on a front tooth is usually less expensive than one on a molar because molars have more canals and are harder to treat. Crowns also range in price based on material: a metal crown is cheaper than a porcelain or zirconia crown. Here is a general idea of what you might pay without insurance:
- Root canal (front tooth): $500 to $1,000
- Root canal (molar): $1,000 to $1,800
- Crown (base metal): $800 to $1,200
- Crown (porcelain or ceramic): $1,000 to $2,500
- Exam and X-rays: $100 to $250
These are national averages, and urban areas tend to be higher. Emergency visits may also include an extra fee. If the tooth is infected, you might need antibiotics or a pulpotomy first, adding to the total. Understanding these costs helps you plan and negotiate. It also helps you recognize when a quote is reasonable and when you should seek a second opinion. Remember that the final price often depends on the complexity of your case, so ask for a detailed breakdown before committing.
Dental School Clinics and Payment Plans as First Stops
One of the most overlooked ways to save on urgent dental work is to visit a dental school clinic. Dental schools offer treatment by supervised students at significantly reduced rates, often 30 to 50 percent less than private practices. The trade-off is time: appointments may take longer, and you may need to schedule around the school's calendar. However, for a root canal or crown, the savings can be substantial. Call your local dental school and ask about emergency services and sliding-scale fees. Some schools also offer payment plans.
Community health centers and nonprofit dental clinics are another option. Many are funded by grants and offer services on a sliding scale based on income. You can search for HRSA-funded health centers or use online resources like the National Association of Free and Charitable Clinics. These clinics may not offer crowns on-site, but they can often handle the root canal or refer you to an affordable specialist. It is worth making a few calls before you assume you cannot afford care.
Payment plans are your next stop. Many dentists offer in-house payment plans with no interest, especially for larger procedures. Ask the front office if you can split the cost over three, six, or twelve months. Some practices use third-party financing like CareCredit, which offers promotional periods with no interest if paid in full. Be careful: if you miss the promotional deadline, interest can be high. Always read the terms. If you need a short-term loan to cover the gap, compare offers from multiple lenders and consider using a platform like 4Payday to connect with lenders that suit your situation.
Negotiating a Payment Plan with the Dentist
Never assume the first price is final. Dental practices are often willing to negotiate, especially if you are paying cash and can demonstrate financial hardship. Start by asking for a discount for upfront payment. Some offices offer 5 to 10 percent off if you pay in full at the time of service. If you cannot pay in full, propose a payment plan. Be honest about what you can afford and stick to it. A written agreement protects both you and the dentist.
Here is a simple framework for negotiating:
- Ask for a detailed treatment plan with procedure codes and fees.
- Explain your situation and ask if there is a cash discount or a sliding scale.
- Propose a payment plan that fits your budget, and offer to set up automatic payments.
- Get the agreement in writing, including the payment schedule and any interest or fees.
- If the practice will not budge, get a second opinion from another dentist or a dental school.
Sometimes, the dentist may offer a different treatment option that costs less. For example, if a crown is not immediately necessary, you might be able to get a temporary filling and save for the crown later. However, do not skip necessary treatment. A root canal without a crown can lead to fracture and tooth loss. Ask about the risks and benefits of each option. A good dentist will work with you to find a solution that preserves your health and your wallet.
When a Short-Term Loan Makes Sense for the Gap
If you have exhausted savings, payment plans, and clinics, a short-term loan might bridge the gap. But it is crucial to understand when a loan is a smart move and when it is a trap. A short-term loan makes sense if you have a clear plan to repay it within a few months, and if the total cost of the loan is less than the cost of delaying treatment (such as a more expensive emergency room visit or extraction). It also makes sense if you have a stable income and can afford the payments without sacrificing necessities.
CashLoanFunded connects borrowers with third-party lenders offering payday loans, installment loans, and personal loans. The application is online and takes under five minutes, and you can receive funds as soon as the next business day if approved. This can be a lifeline when you need cash fast. However, remember that short-term loans often carry high annual percentage rates (APRs) and fees. They are designed for temporary financial gaps, not long-term solutions. Only borrow what you need for the essential procedure, and avoid adding elective treatments to the loan.
Before you apply, compare offers from multiple lenders. Check the APR, repayment terms, and any origination fees. Make sure you can afford the payments. If you have bad credit, you may still qualify, but the terms may be less favorable. Use the loan as a tool to get healthy, not to dig a deeper financial hole. For more on managing cash flow without a bank account, see our guide on how to get a payday loan without a checking account, which covers alternative funding options.
Avoiding High-Cost Borrowing for Elective Add-Ons
When you are already stressed about a root canal, it is easy to say yes to extras like teeth whitening, veneers, or other cosmetic add-ons. Avoid financing these with high-interest loans. Focus on the emergency treatment first. Once you are out of pain and have a plan to pay off the essential care, you can save for elective procedures. If you do want to finance cosmetic work, wait until you have saved or can get a low-interest personal loan. Never use a payday loan for elective dental work; the high cost is not worth it.
Also, be wary of dental discount plans that promise deep discounts but require upfront fees and may not cover major procedures. Do your research and read reviews. Some discount plans are legitimate, but they are not insurance and may have waiting periods. If you are considering one, calculate the total cost including the membership fee and compare it to the discounted fee. Often, negotiating directly with the dentist or using a dental school is a better deal.
Finally, prioritize prevention for the future. Once you handle this emergency, establish a relationship with a dentist and ask about in-house membership plans that cover cleanings and X-rays for a flat annual fee. These plans are not insurance but can help you avoid future emergencies. Taking care of your teeth now can save you from bigger bills later.
Paying for an emergency root canal or crown without insurance is challenging, but you have options. Start with dental schools and community clinics, negotiate a payment plan, and only consider a short-term loan if it fits your budget and you can repay it quickly. Your health is the priority, and with a little planning, you can get the care you need without financial ruin.