Lender Pressure to Accept Immediately: What to Do Now
Feeling rushed by a lender? Learn how to protect yourself, request written terms, and walk away safely. You have the right to decline any offer with no fee.
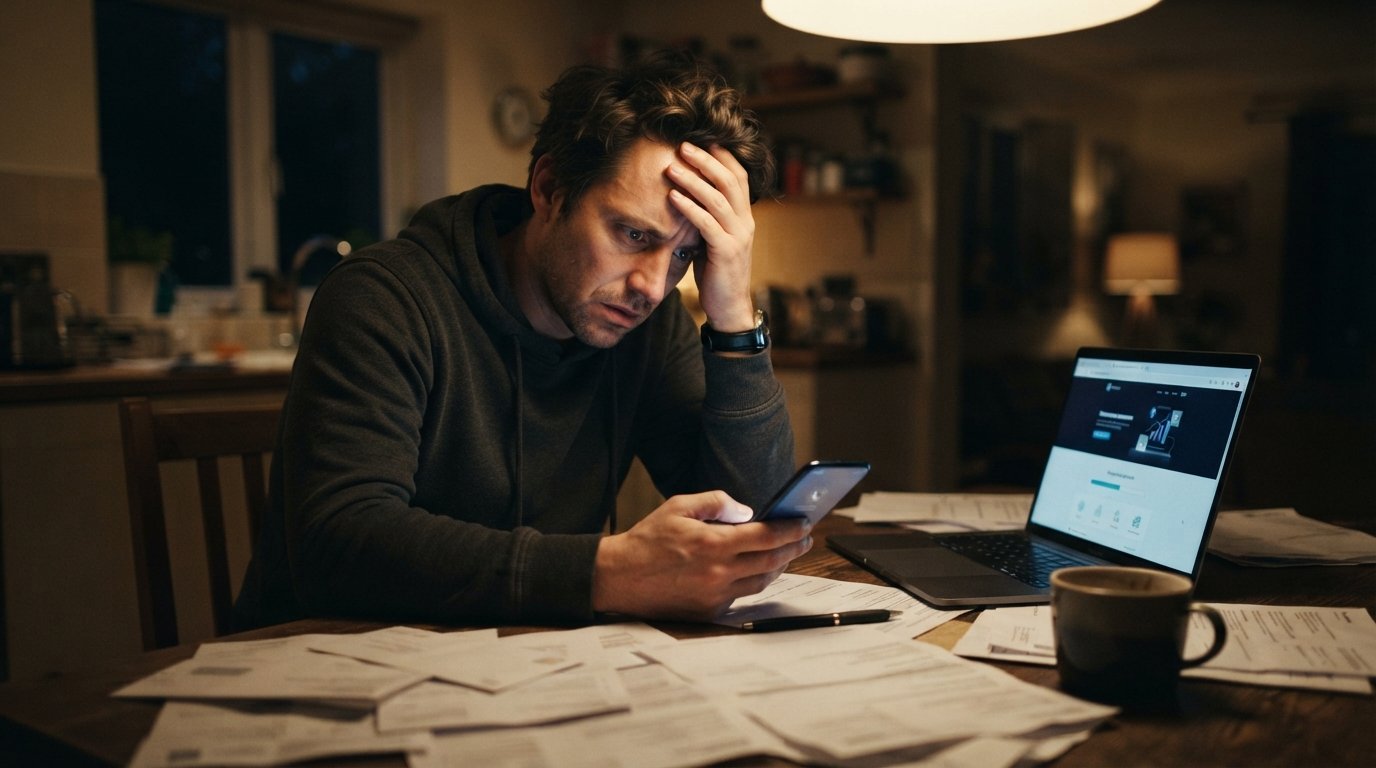
You open an email or answer a call, and the voice on the other end says the offer expires in ten minutes. Your heart races. The car is in the shop, the rent is due, or a medical bill is staring you down. In that moment, it is easy to feel like you have no choice but to say yes. But here is the truth: no legitimate lender should ever pressure you to accept immediately. Understanding what to do if a lender pressures you to accept immediately can protect you from costly mistakes and help you find a better path forward.
High-pressure sales tactics are a red flag, not a courtesy. Whether you are dealing with a payday lender, an installment loan provider, or an online matching service, you have rights. This guide walks you through practical steps to slow things down, verify the terms, and walk away safely if needed. You will learn how to spot manipulation, request written details, document the encounter, and explore safer alternatives. By the end, you will feel confident handling any lender who tries to rush you into a decision.
Why Legitimate Offers Allow Time to Review Terms
Reputable lenders understand that borrowing money is a serious commitment. They want you to read the fine print, ask questions, and make an informed choice. After all, a loan that fits your budget is more likely to be repaid on time, which benefits both you and the lender. That is why legitimate offers come with clear disclosures, written agreements, and a reasonable window to decide. If a lender refuses to give you that time, something is wrong.
Federal and state laws reinforce this principle. For example, the Truth in Lending Act requires lenders to disclose key terms, including the annual percentage rate (APR), finance charges, and repayment schedule, before you sign. Many states also impose cooling-off periods or mandatory waiting times for certain loan types. These rules exist because lawmakers know that rushed decisions often lead to financial harm. When a lender ignores these protections, they are likely more interested in trapping you than helping you.
Think about your own experience with major purchases. When you buy a car or a house, you get days to review contracts and seek advice. Even a cell phone contract comes with a grace period. Short-term loans should be no different. A lender who respects you will say something like, "Take your time, read the terms, and call me with questions." If instead you hear "sign now or lose the offer," consider that a warning sign. Legitimate offers do not evaporate in minutes. They may have deadlines, but those deadlines are usually measured in days, not seconds, and they come with written documentation you can keep.
CashLoanFunded, for instance, operates as a free matching service that connects borrowers with third-party lenders. It does not charge fees and does not pressure users to accept any offer. In fact, the platform explicitly states that users are never obligated to accept a lender's offer. That is the standard you should expect everywhere. If a lender deviates from it, you have every right to pause and protect yourself.
Your Right to Decline Any Offer With No Fee
One of the most important things to know is that you can always say no. No legitimate lender can force you to accept a loan, and you should never pay a fee simply to decline an offer. Unfortunately, some predatory lenders use high-pressure tactics to make you believe otherwise. They might claim that a "processing fee" is nonrefundable, or that backing out now will hurt your credit. These claims are often false or misleading.
Under federal law, you generally have the right to cancel certain loan agreements within a specified period, often three days, without penalty. This is known as the right of rescission. For payday and installment loans, state laws vary, but many provide similar protections. Even if a cooling-off period does not apply, you are never obligated to accept an offer you have not signed. If you have not signed, you have not agreed. It is that simple.
Here is what you can do if a lender tries to charge you for declining:
- Ask for the fee in writing, including the exact reason and the legal basis for it.
- Refuse to pay any fee that was not clearly disclosed before you applied.
- Report the lender to your state's attorney general or financial regulator.
- Keep a record of all communications, including emails and call logs.
Remember, CashLoanFunded and similar legitimate matching services do not charge you for connecting with lenders, and they do not penalize you for walking away. If a lender demands a fee to decline, that is a major red flag. Walk away and report them. Your right to say no is protected, and exercising it costs you nothing with a reputable company.
How to Ask for Written Terms Before Deciding
Verbal promises mean nothing in the lending world. If a lender will not put the terms in writing, you should not do business with them. Asking for written terms is your best defense against pressure tactics. It forces the lender to commit to specific numbers and gives you time to review everything at your own pace. Here is a simple framework to follow.
First, request a written loan agreement or disclosure statement that includes all key details. At a minimum, it should show the loan amount, the APR, the finance charge, the repayment schedule, and any fees or penalties. It should also state the total amount you will repay over the life of the loan. If the lender hesitates or says they cannot provide this until you sign, that is a problem. Legitimate lenders provide these disclosures before you commit.
Second, ask for the terms via email so you have a permanent record. If the lender only wants to talk on the phone, insist on a written follow-up. You can say something like, "I prefer to review everything in writing. Please email me the full terms and I will get back to you." A reputable lender will comply. A predatory one will push back, often with urgency tactics like "the rate will change" or "this offer is only good today." Stand your ground. The offer is not real if it cannot be documented.
Third, take your time reading. Compare the APR to other offers you have received. Check for prepayment penalties, late fees, and balloon payments. Use a loan calculator to see how much the loan will truly cost. If anything is unclear, ask questions in writing and keep the responses. Only after you understand every detail should you consider signing. And if the lender keeps calling while you review, that is another sign to slow down or walk away.
For more insight into how legitimate lenders handle the process from approval to payout, see this guide on how banks process funded loans. It explains the standard steps and timelines, which can help you recognize when a lender is rushing you unfairly.
Documenting Pressure Tactics for a Complaint
If a lender pressures you, document everything. Detailed records are your strongest tool if you need to file a complaint or dispute a charge. Start by keeping a log of all communications. Write down the date, time, and name of the person you spoke with, along with what they said. Save emails, text messages, and voicemails. If you receive a written offer, keep a copy. If you are pressured on a call, take notes in real time or ask for permission to record (if your state allows one-party consent, you can record without asking, but check your local laws).
Focus on specific pressure tactics. Note if the lender:
- Demands an immediate decision or says the offer expires within minutes.
- Threatens legal action or credit damage if you do not sign.
- Refuses to provide written terms or discourages you from reading them.
- Uses aggressive language or calls repeatedly after you ask them to stop.
- Claims you must pay a fee to decline the offer.
Once you have documentation, you can file complaints with several agencies. The Consumer Financial Protection Bureau (CFPB) accepts complaints about predatory lending practices online or by phone. Your state's attorney general office and state financial regulator also handle these issues. If the lender is a bank or credit union, you can complain to the Office of the Comptroller of the Currency or the National Credit Union Administration. Include your documented evidence with each complaint. The more specific you are, the more likely regulators will investigate.
Documentation also protects you if the lender tries to claim you agreed to terms you never accepted. Having a record of the pressure tactics can help you dispute unauthorized charges or incorrect credit reporting. Keep your records organized and stored safely. You never know when you might need them.
Safe Ways to Walk Away and Request New Offers
Walking away from a high-pressure lender is not just safe; it is smart. But you still need funding, so how do you move forward without falling into another trap? The key is to disengage from the pushy lender and seek offers from reputable sources. Start by ending the conversation politely but firmly. You can say, "I am not comfortable making a decision right now. I will contact you if I decide to proceed." Then hang up or stop responding to messages. Do not argue or explain further; you do not owe them an explanation.
Next, consider using a reputable matching service like FreeQuotes.Loans to compare offers from multiple lenders. These platforms let you submit one request and receive personalized loan offers from a network of third-party lenders. You can review the terms side by side and choose the one that fits your needs, without pressure from a single lender. Because these services are not direct lenders, they have no incentive to rush you. They simply connect you with options.
When you request new offers, follow these steps to stay safe:
- Use a matching service that clearly states it does not charge fees and does not obligate you to accept any offer.
- Provide accurate information, but never share more than necessary until you have reviewed the lender's terms.
- Compare APRs, fees, and repayment terms across at least three offers.
- Ask for written disclosures from each lender before making a decision.
- Choose the offer with the lowest overall cost and the most manageable repayment schedule.
Remember that CashLoanFunded operates on this model. It connects borrowers with lenders and emphasizes that users are never obligated to accept an offer. You can use its simple online form to see what options might be available to you, with potential funding as soon as the next business day. That speed should never come at the cost of pressure. If any lender in the network tries to rush you, you can simply decline and move on to another offer.
Finally, consider alternatives to high-cost loans. If you have a little time, explore credit union small-dollar loans, employer advances, or payment plans with service providers. These options may offer lower costs and more flexibility. But if you do need a short-term loan, go in with your eyes open and your rights in hand. You deserve to be treated with respect, and you always have the power to walk away.
Pressure tactics are a sign of a lender you should avoid. By knowing your rights, asking for written terms, documenting everything, and using safe alternatives, you can protect yourself and find funding on your own terms. No legitimate offer disappears in minutes. Take a breath, step back, and choose wisely. Your financial well-being is worth the extra time.