How to Start an Emergency Fund With No Money
Start an emergency fund with no money by finding hidden cash, using windfalls, and automating small transfers. Build a $500 buffer without a second job.
By Isaac Cooper
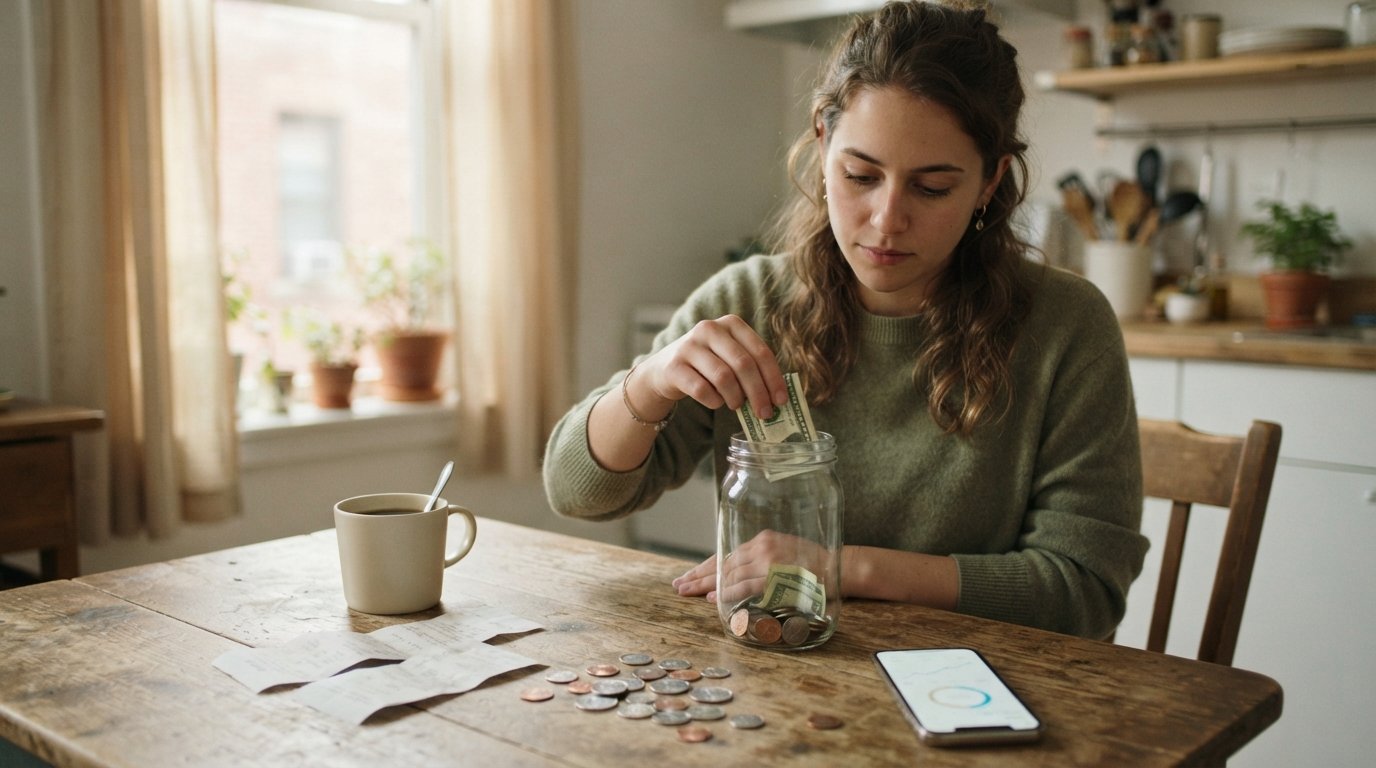
You do not need a windfall or a second job to build a financial safety net. If your bank account shows a balance of zero and an unexpected bill would throw your entire month into chaos, you are exactly who needs an emergency fund the most. The idea of saving when you have nothing left over feels impossible, but it is not. Building an emergency fund with no money is less about finding extra cash and more about changing how you handle the money that already passes through your hands.
The core principle is simple: start absurdly small, automate the process, and protect the fund from yourself. This guide walks you through practical steps that work even when your budget is stretched thin. You will learn how to find hidden money in your current spending, use windfalls strategically, and leverage tools like a trusted cash loan connection service only as a last resort while you build your own buffer.
Why an Emergency Fund Matters More Than You Think
An emergency fund is not about getting rich. It is about avoiding a debt spiral when life goes wrong. A car repair, a medical copay, or a broken phone can derail your entire financial life if you have no cushion. Without savings, you rely on credit cards or high-interest loans, which add fees and interest that make the next month even harder. The cycle repeats until a small setback becomes a long-term crisis.
Research consistently shows that even a few hundred dollars in savings reduces the likelihood of missing a bill payment or taking on predatory debt. The psychological benefit is just as important. Knowing you have a buffer, even a tiny one, reduces stress and helps you make clearer decisions. You stop operating from a place of panic and start planning ahead.
The goal is not to save six months of expenses overnight. That number is intimidating and unrealistic for most people starting from zero. Instead, aim for a starter emergency fund of $500 to $1,000. That amount covers most common emergencies: a tire replacement, a urgent care visit, a plumbing leak. Once you hit that milestone, you can build toward a larger cushion.
How to Find Money When Your Budget Feels Maxed Out
The first objection is always the same: there is nothing left to save. But money is often hiding in plain sight. You do not need to earn more to save more, at least not at first. You need to redirect existing spending toward your emergency fund. This requires a mindset shift: treat savings as a non-negotiable bill, not as whatever is left over at the end of the month.
Start by tracking every dollar for one week. Use a notebook or a free app. You will likely find small leaks: a daily coffee, a subscription you forgot about, a convenience store run. These are not moral failures. They are opportunities. Cancel one subscription and redirect that amount to savings. Skip one takeout meal and transfer the equivalent. These small moves add up faster than you think.
Next, look at your fixed expenses. Can you negotiate a lower rate on your internet or phone plan? Can you adjust your thermostat by a few degrees? Can you carpool or combine errands to save gas? Each reduction, no matter how small, becomes a deposit into your emergency fund. The key is to automate the transfer so you never see the money in your checking account.
Here are five practical ways to find your first $100 without earning extra income:
- Sell unused items: old electronics, clothes, furniture. Even $20 here and there adds up.
- Cancel one subscription service and set that amount to auto-transfer to savings.
- Use cash-back apps or rewards on purchases you already make, then deposit the rewards.
- Reduce one recurring expense by calling your provider and asking for a better rate.
- Set a no-spend week once a month and save the difference.
None of these steps require a second job or a sudden inheritance. They require attention and a willingness to prioritize your future self over momentary convenience. Once you see the balance grow, even by $10, you will feel more motivated to keep going.
Using Windfalls and Unexpected Income Wisely
A windfall is any money you did not expect: a tax refund, a bonus, a gift, a settlement. Most people treat this as free money and spend it immediately. Instead, commit to saving at least half of every windfall. If you get a $500 tax refund, put $250 into your emergency fund and use the rest for something you need or enjoy. This single habit can jumpstart your fund faster than months of scrimping.
Even small windfalls count. A $20 rebate check, a cash gift for your birthday, or a reimbursement from work can all go directly into savings. The key is to make the decision before the money arrives. Tell yourself, "Any unexpected money goes to the emergency fund first." This removes the temptation to spend it on impulse.
If you receive a raise or a new job with higher pay, avoid lifestyle creep. Continue living on your old budget and save the difference. That extra $100 or $200 per month can build a substantial fund within a year. The same applies to side gigs or overtime. Treat that income as a tool for building security, not as a reason to upgrade your lifestyle.
Where to Keep Your Emergency Fund
Your emergency fund needs to be accessible but not too accessible. If it sits in your checking account, you will be tempted to spend it. If it is locked in a long-term investment, you cannot get to it quickly. The sweet spot is a separate high-yield savings account at an online bank. These accounts typically offer higher interest rates than traditional banks and are FDIC insured.
Open a new account specifically for your emergency fund. Do not link it to your debit card. Make transfers manual or set up a recurring automatic transfer from checking. The friction of moving money from one account to another gives you a moment to reconsider non-essential purchases. You want the money to be there when you truly need it, not when you simply want it.
If you have difficulty with self-control, consider a certificate of deposit (CD) or a money market account with limited withdrawals. Just ensure you can access the funds within a day or two for true emergencies. The goal is to balance accessibility with protection from your own spending habits.
For those who have exhausted all other options and face an immediate, unavoidable expense, a short-term loan might be a temporary bridge. In our guide on best emergency funded cash loans for urgent bills, we explain how these options work and what to watch out for. However, these loans should never replace an emergency fund. They are a last resort, not a strategy.
Building the Habit: Small Steps, Big Results
The hardest part of building an emergency fund is starting. Once you begin, momentum takes over. Set a goal that feels almost too easy: save $1 per day. That is $30 per month. After a year, you have $365. That is a real emergency fund. Next year, increase it to $2 per day. The point is to create a habit, not to hit a specific number immediately.
Use visual cues to stay motivated. A simple chart on your fridge where you color in a box for every $50 saved can be surprisingly powerful. Or set a small reward for each milestone: $100, $250, $500. The reward does not need to cost money. It could be a movie night at home or a favorite meal. Celebrate your progress and remind yourself why you are doing this.
Involve your family or a trusted friend. Tell them about your goal. Accountability increases follow-through. If you share your progress, you are less likely to raid the fund for non-emergencies. You might even inspire someone else to start their own fund.
Remember that setbacks happen. You might have to use your emergency fund for an actual emergency. That is what it is for. Do not feel like you failed. Rebuild it as soon as you can. The habit of saving is more important than the balance at any given moment.
When to Consider a Short-Term Loan (and When to Avoid It)
There are situations where you truly cannot cover an expense even after cutting every possible cost. In those cases, a short-term loan from a reputable lender might be a temporary solution. These loans are typically small, repaid quickly, and designed for emergencies. However, they come with high APRs and fees. They are not a substitute for an emergency fund; they are a stopgap.
Before taking a loan, ask yourself: Is this a true emergency? Can I negotiate a payment plan with the creditor? Do I have any other options? If you decide a loan is necessary, borrow only what you need and have a clear plan to repay it on time. Late payments add fees and damage your credit score, making the next emergency even harder.
After you repay the loan, immediately restart your emergency fund. Use the same payment amount you were sending to the lender and redirect it to savings. This way, you turn a temporary fix into a permanent habit. Over time, you will rely less on loans and more on your own buffer.
Building an emergency fund with no money is not about luck or privilege. It is about small, consistent choices. Start where you are, use what you have, and keep going. Your future self will thank you.
For more resources on managing urgent expenses and understanding your options, explore the educational content at CashLoanFunded. They provide clear, transparent information to help you make informed decisions, whether you are saving for the future or facing a temporary gap.