How to Start an Emergency Fund on a Low Income
Start an emergency fund on a low income with small, consistent steps. Call 8335013363 for guidance on emergency funding options.
By Owen Mitchell
Life throws curveballs. A car breaks down. A child gets sick. A layoff happens. When you are living paycheck to paycheck, these events can feel like a knockout punch. But what if there was a way to soften the blow? It is possible to build a financial cushion even when money is tight. You do not need a six-figure salary to start an emergency fund. You need a plan, a few small habits, and a little patience. This guide will walk you through exactly how to start an emergency fund on a low income, step by step. By the end, you will have a clear roadmap to create a safety net that protects you from debt and stress.
Why an Emergency Fund Is Your Financial Airbag
Think of an emergency fund as your financial airbag. You hope you never need it, but if you do, it saves you from disaster. Without savings, any unexpected expense becomes a crisis. You might rely on credit cards, payday loans, or borrowing from friends. These options often come with high interest or strained relationships. An emergency fund breaks that cycle. It gives you options. You can pay for the repair, cover the medical bill, or handle the sudden loss of income without spiraling into debt.
For those with low income, an emergency fund is even more critical. A 2024 Federal Reserve report found that nearly 40 percent of Americans could not cover a $400 emergency with cash. That means millions of people are one flat tire away from financial chaos. Building even a small buffer changes your mindset. You move from surviving to planning. You gain control. The goal is not to become rich overnight. The goal is to stop the bleeding when life cuts you.
Step 1: Set a Realistic Goal That Fits Your Life
Many financial experts suggest saving three to six months of expenses. That advice is solid, but it can feel impossible when you are struggling to pay this month's rent. If you set a goal of $10,000 and you only have $20 left each week, you will quit before you start. The key is to start small. Your first goal is not a full emergency fund. Your first goal is a starter fund. Aim for $500. That amount covers most common emergencies: a minor car repair, a vet visit, or a broken appliance.
Once you hit $500, aim for $1,000. Then, slowly build toward one month of essential expenses. Break it down into mini-milestones. Each time you reach one, celebrate. This approach keeps you motivated. It also builds the habit of saving. Remember, consistency beats intensity. Saving $5 a week is better than saving $50 once and then nothing for months.
Step 2: Find Money You Already Have (Without a Raise)
You might think there is no room in your budget. But often, there is money hiding in plain sight. The trick is to look at your spending without judgment and find small leaks. Start by tracking every dollar for one week. Write down everything: coffee, snacks, subscription fees, impulse buys. You will likely spot at least one or two areas to trim.
Here are some common places to find extra cash:
- Cancel unused subscriptions: Streaming services, gym memberships, or app fees you forgot about.
- Reduce dining out: Packing lunch just twice a week can save $30 or more.
- Lower your bills: Call your internet or phone provider and ask for a better rate. Many will match competitor offers.
- Sell unused items: Clothes, electronics, or furniture you no longer need can bring in quick cash.
- Use cash-back apps: Apps like Fetch or Ibotta give you small rewards for receipts. It adds up.
Even $20 a week adds up to over $1,000 in a year. The point is not to deprive yourself. The point is to redirect money toward your safety net. You are not saying no to fun. You are saying yes to peace of mind.
Step 3: Automate Small, Consistent Deposits
Willpower is unreliable. When you see money in your checking account, you want to spend it. The solution is automation. Set up a separate savings account and schedule automatic transfers. Even $5 or $10 per paycheck helps. You will not miss what you do not see. Many banks offer sub-savings accounts with no minimum balance. Look for one with no monthly fees.
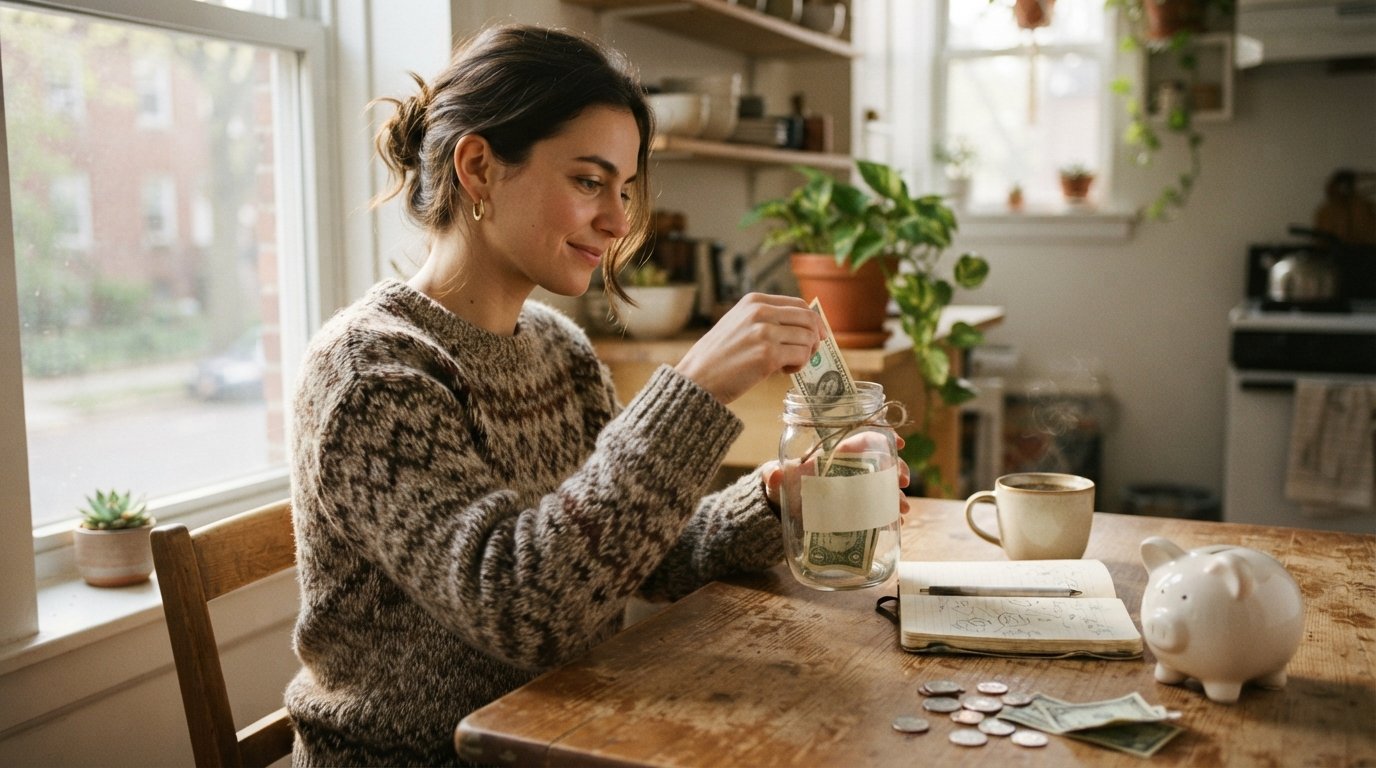
If your employer offers direct deposit, you can often split your paycheck. Send a portion directly to savings. This is the easiest way to save because the money never hits your checking account. If you are paid in cash, create a manual system. Every time you get paid, put a small amount in an envelope labeled "Emergency Fund." Then deposit it weekly. The physical act reinforces the habit.
If you are facing an urgent expense right now and need money before you can build your fund, you might explore short-term options. For example, AdvanceCash connects consumers with third-party lenders for payday, personal, and installment loans. It is not a direct lender, but it can help you compare offers quickly. However, use these options only as a last resort. They carry high APRs and should not replace a long-term savings plan.
Step 4: Use Windfalls Wisely
A windfall is any unexpected money: a tax refund, a bonus, a gift, or an inheritance. When you are low income, windfalls feel like a chance to splurge. But this is the fastest way to stay stuck. Instead, commit to saving at least half of every windfall. If you get a $600 tax refund, put $300 into your emergency fund. Use the rest for something you need or enjoy. This balance keeps you motivated.
If you have high-interest debt, you might be tempted to pay it off first. That is a good goal, but having zero savings is dangerous. You need a starter fund before you aggressively pay debt. Otherwise, you will rely on credit cards again when an emergency hits. Build $500 first, then attack debt. Once debt is gone, you can save faster.
Step 5: Keep Your Fund Separate and Accessible
Your emergency fund should not be in your checking account. If it is, you will spend it. It should not be in a long-term investment either, because you need quick access. A simple savings account at a different bank is ideal. It takes one to two business days to transfer, which deters impulse spending. But it is fast enough for real emergencies.
Look for a high-yield savings account (HYSA). These pay more interest than traditional accounts. Even 4 percent APY on $1,000 earns you $40 a year. That is free money. Avoid accounts with monthly fees or minimum balance requirements. Credit unions often offer better terms than big banks. Do your research and pick one that fits your needs.
Step 6: Define What Counts as an Emergency
Not every unexpected expense is an emergency. A sale on shoes is not an emergency. A vacation is not an emergency. Before you dip into your fund, ask yourself: Is this urgent? Is it necessary? Can I delay it? True emergencies are events that threaten your health, safety, or housing. Examples include:
- Medical bills or prescriptions
- Car repairs needed to get to work
- Emergency home repairs (plumbing, heating)
- Job loss or reduced hours
- Travel for a family emergency
Write down your personal definition and stick it to your savings account. This rule prevents you from draining your fund for non-essentials. It also gives you confidence that the money is there when you truly need it.
Step 7: Rebuild and Grow After You Use It
At some point, you will use your emergency fund. That is what it is for. Do not feel guilty. Instead, make a plan to rebuild. Treat the replenishment like a bill. If you used $200 for a car repair, add $20 extra to your savings each week until it is back. This habit ensures your fund remains ready for the next event.
As your income increases, increase your savings rate. If you get a raise, put half of it toward savings. You will not miss the money if you never adjust your lifestyle. Over time, your fund will grow from $500 to $1,000 to one month of expenses. Each milestone brings more security and less stress.
Overcoming Common Mental Blocks
Many people on low incomes feel that saving is pointless. They think, "What is the use of $10? It won't help." But small amounts matter. A $10 bill can buy a prescription or put gas in your car to get to a job interview. Another block is the fear of deprivation. You might feel like saving means never having fun. That is not true. You can save and still enjoy life. The key is balance.
If you have tried to save before and failed, do not beat yourself up. Start again. Financial progress is not a straight line. It is a series of small decisions that add up. Every dollar you save is a vote for your future self. Keep voting.
When to Consider a Short-Term Loan
Even with an emergency fund, some emergencies exceed your savings. In those moments, you might need outside help. Short-term loans, such as payday or installment loans, can provide quick cash. However, they come with high fees and APRs. They are designed to be repaid quickly, usually on your next payday. If you cannot repay on time, the costs escalate.
If you must borrow, do your research. Compare offers from multiple lenders. Read the terms carefully. Understand the total repayment amount, not just the monthly payment. Never borrow more than you can repay. And always have a plan to pay it back without renewing the loan. Platforms like CashLoanFunded can connect you with lenders, but they are not a substitute for a savings habit. Use them sparingly and responsibly.
For more strategies on building savings from scratch, see our guide on how to start an emergency fund with no money. It covers additional tactics for finding cash when you have none.
Building an emergency fund on a low income is not easy, but it is possible. Start small. Be consistent. Celebrate every milestone. Your future self will thank you.