How To Get Help From a Nonprofit Credit Counselor For Short Term Debt
A nonprofit credit counselor can negotiate lower payments and build a debt management plan to help you escape short term debt without new loans.
By Quinn Turner
You did what you had to do. The car broke down, the medical bill arrived, or the rent came due before the paycheck cleared, and a short term loan bridged the gap. Now the repayment date is looming, the balance feels heavier than expected, and you are wondering whether another loan will fix the problem or make it worse. Before you take on more debt, consider a different path: a nonprofit credit counselor can help you negotiate with lenders, build a realistic repayment plan, and regain control without adding another high interest payment to your monthly load.
What Nonprofit Credit Counseling Actually Includes
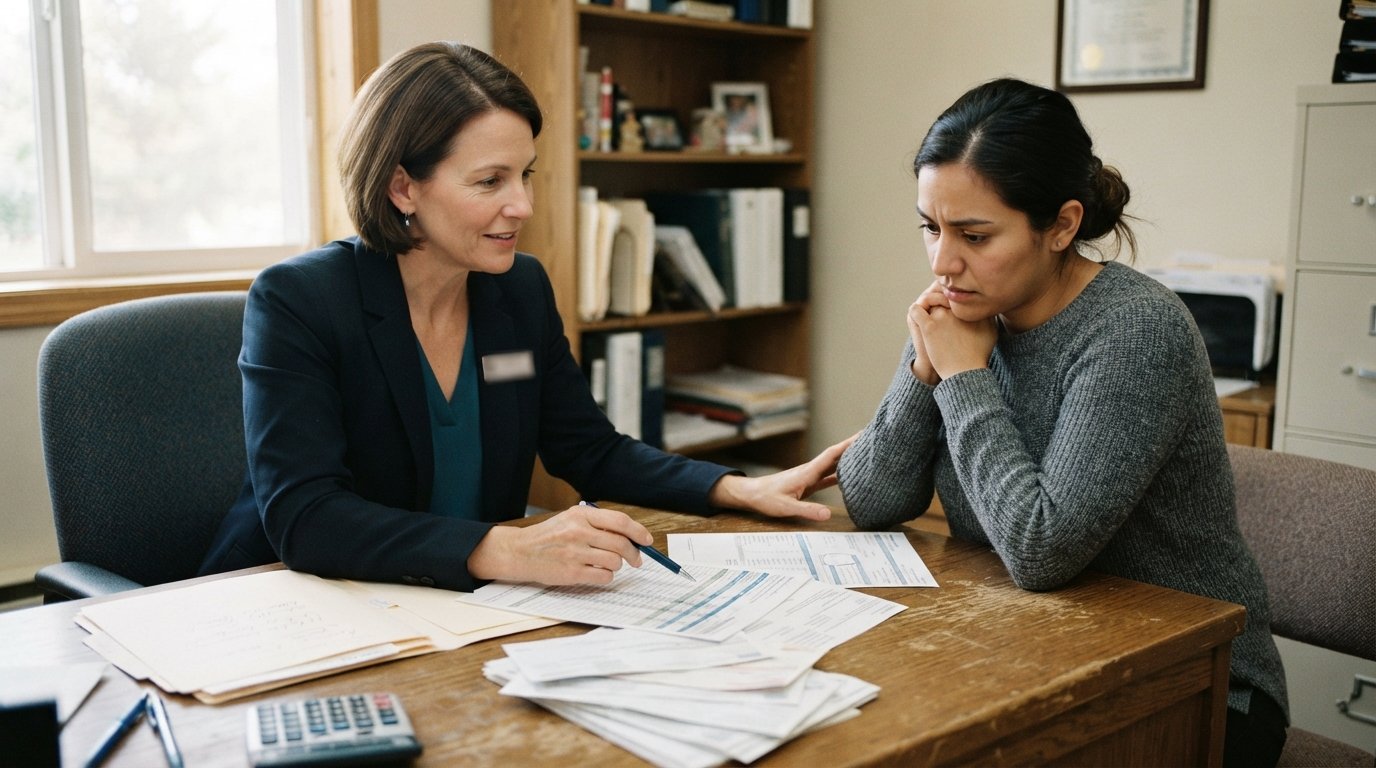
Nonprofit credit counseling is a structured service designed to help consumers understand their financial situation and create a plan to manage debt. These agencies typically operate as 501(c)(3) organizations, which means they are mission driven rather than profit driven. The initial consultation is often free or low cost, and the counselor's job is to review your income, expenses, debts, and credit report with you. They do not judge your choices; they map out options.
A typical session covers your full financial picture, including every short term loan, credit card balance, and recurring obligation. The counselor calculates your debt to income ratio, identifies where your money is going, and explains how your current repayment schedule compares to what you can realistically afford. From there, they outline alternatives: budgeting adjustments, debt management plans, debt consolidation, or in some cases, referrals to legal or housing resources.
Many people assume credit counseling is only for people facing bankruptcy. In reality, it is useful for anyone who feels trapped by high interest obligations. If you have taken out a payday loan, a cash advance, or an installment loan to cover an emergency, a counselor can help you see whether a structured payoff plan is feasible. For background on how funding estimates and loan amounts are determined, see this guide on how accurate funding estimates are; understanding those numbers helps you have a more productive conversation with a counselor about what you actually owe and what you can repay.
Nonprofit status matters because it signals accountability. Legitimate agencies are audited, their counselors are certified, and their fees are disclosed upfront. They also participate in consumer education, which means they should be willing to explain every option, not just the one that generates a fee.
How Counselors Negotiate With Lenders
One of the most valuable services a nonprofit credit counselor provides is direct negotiation with your creditors. This is especially relevant for short term debt, where interest rates and fees can balloon quickly. Counselors have established relationships with many lenders and can often negotiate lower interest rates, waived late fees, or extended repayment terms.
The negotiation process usually works like this: after reviewing your accounts, the counselor contacts each lender to propose a modified repayment plan. They may ask the lender to reduce the interest rate, stop accruing fees, or accept a lower monthly payment over a longer period. Lenders are not obligated to agree, but many do because a structured plan is more attractive than a default or charge off. The counselor documents each agreement and consolidates the terms into a single plan for you to review.
It is important to understand what counselors cannot do. They cannot erase legitimate debt, and they cannot force a lender to accept a settlement. They also cannot make promises on behalf of a lender. What they can do is present your case professionally and advocate for terms that fit your budget. If you are dealing with multiple short term loans, this advocacy can save you significant money in fees and interest over time.
For borrowers who are considering a new loan to cover existing debt, a counselor will often advise caution. Rolling short term debt into another short term loan can create a cycle that is difficult to escape. Instead, the counselor may recommend a debt management plan, which we will cover next.
Debt Management Plans Versus New Loans
A debt management plan, often called a DMP, is a structured repayment program administered by the credit counseling agency. You make one monthly payment to the agency, and the agency distributes payments to your creditors according to the negotiated terms. The plan typically lasts three to five years, depending on the total debt and the terms your creditors agree to.
The alternative, taking out a new loan to pay off old debt, is appealing because it feels fast. But it comes with risks. A new short term loan may carry an even higher annual percentage rate than your existing obligations, and if you cannot repay it on time, you may face additional fees and renewed collection pressure. A DMP, by contrast, is designed around what you can afford, and it usually includes concessions from creditors that you could not obtain on your own.
Here is a simple comparison to help you weigh the options:
- Debt management plan: One monthly payment, negotiated lower interest rates, structured timeline, no new debt, requires discipline and a stable income.
- New short term loan: Fast funding, but higher rates and fees, potential for a debt cycle, does not address the underlying budget gap, may require a credit check.
- Debt consolidation loan: Combines multiple debts into one payment, but approval depends on creditworthiness and income, and the interest rate may still be high.
- Budget counseling only: No new debt, no formal plan, but requires you to negotiate with lenders yourself and may not reduce your balances.
For many people struggling with short term debt, a DMP is the most sustainable path because it removes the temptation to borrow again and provides a clear finish line. However, it is not right for everyone. If your debt is small or your income is unstable, a counselor may recommend a different approach, such as a spending plan or a referral to a local assistance program.
It is also worth noting that some nonprofit agencies offer debt management plans only for unsecured debts like credit cards and personal loans. Payday loans and cash advances may be handled differently, and the counselor will explain what is possible in your state. Regulations vary, and the counselor should be familiar with the rules that apply to your lenders.
Questions To Ask Before Hiring a Counselor
Not all credit counseling agencies operate the same way, and it is wise to ask questions before you share sensitive financial information or sign any agreement. A reputable nonprofit will welcome your questions and answer them clearly. The following list covers the essentials:
- Are you a nonprofit organization? Ask for proof of 501(c)(3) status and check whether the agency is licensed or registered in your state.
- What are your fees? Nonprofit agencies may charge a small setup fee and a monthly fee for a debt management plan, but these should be disclosed upfront and should be reasonable. Ask whether any fees are waived for low income clients.
- Are your counselors certified? Look for certification through a recognized body such as the National Foundation for Credit Counseling or the Financial Counseling Association of America.
- What services do you offer? A good agency provides budgeting help, credit report review, debt management plans, and referrals to other resources. Be wary if the only option presented is a debt management plan with a fee.
- How do you handle negotiations with lenders? Ask for a clear explanation of how they contact creditors, what terms they typically seek, and how they communicate progress to you.
- Will you put our agreement in writing? You should receive a written contract that outlines services, fees, and the terms of any debt management plan before you commit.
These questions help you separate legitimate nonprofits from organizations that use the nonprofit label to mask high fees or aggressive sales tactics. If a counselor pressures you to sign immediately or refuses to answer basic questions, walk away.
It is also helpful to ask about the agency's privacy policy. You will be sharing account numbers, income details, and possibly your Social Security number. A trustworthy agency will explain how your data is protected and will not sell your information without consent.
Spotting For Profit Services That Charge Excessive Fees
The credit counseling industry includes many honest nonprofits, but it also includes for profit companies that mimic the language of nonprofit counseling while charging excessive fees. These companies may advertise "free" consultations that turn into high pressure sales pitches for debt settlement or consolidation loans. Knowing the warning signs can protect you from paying hundreds or thousands of dollars for services you do not need.
One red flag is a company that demands upfront fees before providing any counseling. Legitimate nonprofits may charge a modest fee for a debt management plan, but they do not require large advance payments simply to review your situation. Another red flag is a promise to "eliminate" or "erase" debt. No counselor can legally erase legitimate debt, and any company that makes that claim is misleading you.
Be cautious of organizations that discourage you from contacting your creditors directly or that refuse to provide written information about their fees. Transparency is a hallmark of legitimate counseling. You should also be wary of companies that contact you unsolicited, especially if they claim to have pre approved you for a debt relief program. Reputable agencies do not cold call consumers with guaranteed results.
If you are unsure whether an agency is legitimate, check with your state attorney general's office or the state regulator that oversees credit counseling. You can also ask the agency for its registration number and verify it independently. Taking a few minutes to check credentials can save you from a costly mistake.
For borrowers who ultimately decide that a short term loan is still part of their broader financial strategy, it helps to work with a transparent connection service. FundingCashLoans is a free online connection service that helps U.S. consumers find short term and payday loan options through a network of third party lenders. The site does not make credit decisions and does not charge users fees for matching; any loan terms come directly from the lender. Used responsibly and in combination with counseling, such services can be a bridge during a temporary gap, but they are not a substitute for a long term repayment plan.
Building a Realistic Plan After Counseling
Once you have completed your counseling session and chosen a path, the real work begins. A counselor can help you set up a budget that accounts for your short term debt payments alongside your regular expenses. This budget should include a small emergency cushion, even if it is only a few dollars per week, so that an unexpected expense does not send you back to borrowing.
If you enroll in a debt management plan, make your payments on time and communicate with the agency if your income changes. Most agencies can adjust your plan if you experience a job loss or a medical emergency, but they can only help if you tell them. Keep records of every payment and every communication with your creditors.
If you decide to repay your short term loans without a formal plan, use the negotiation skills your counselor taught you. Contact each lender, explain your situation, and ask for a modified payment schedule. Many lenders prefer a partial payment to no payment at all. Document every conversation and follow up in writing.
Finally, revisit your budget every few months. Life changes, and a plan that worked in January may need adjustment by June. A nonprofit credit counselor can provide follow up sessions, often at low or no cost, to help you stay on track. The goal is not just to pay off this round of debt but to build habits that keep you from needing emergency borrowing in the future.
Getting help from a nonprofit credit counselor for short term debt is a practical step toward financial stability. It replaces guesswork and anxiety with a clear plan, and it gives you an advocate who understands how lenders operate. Whether you choose a debt management plan, a negotiated repayment schedule, or a combination of strategies, the key is to act before the debt spirals. A certified counselor can help you make that decision with confidence.