Essential Documents Checklist for a Fast Online Loan Application
Gather these essential documents before you apply online to avoid delays and get funds as soon as the next business day.
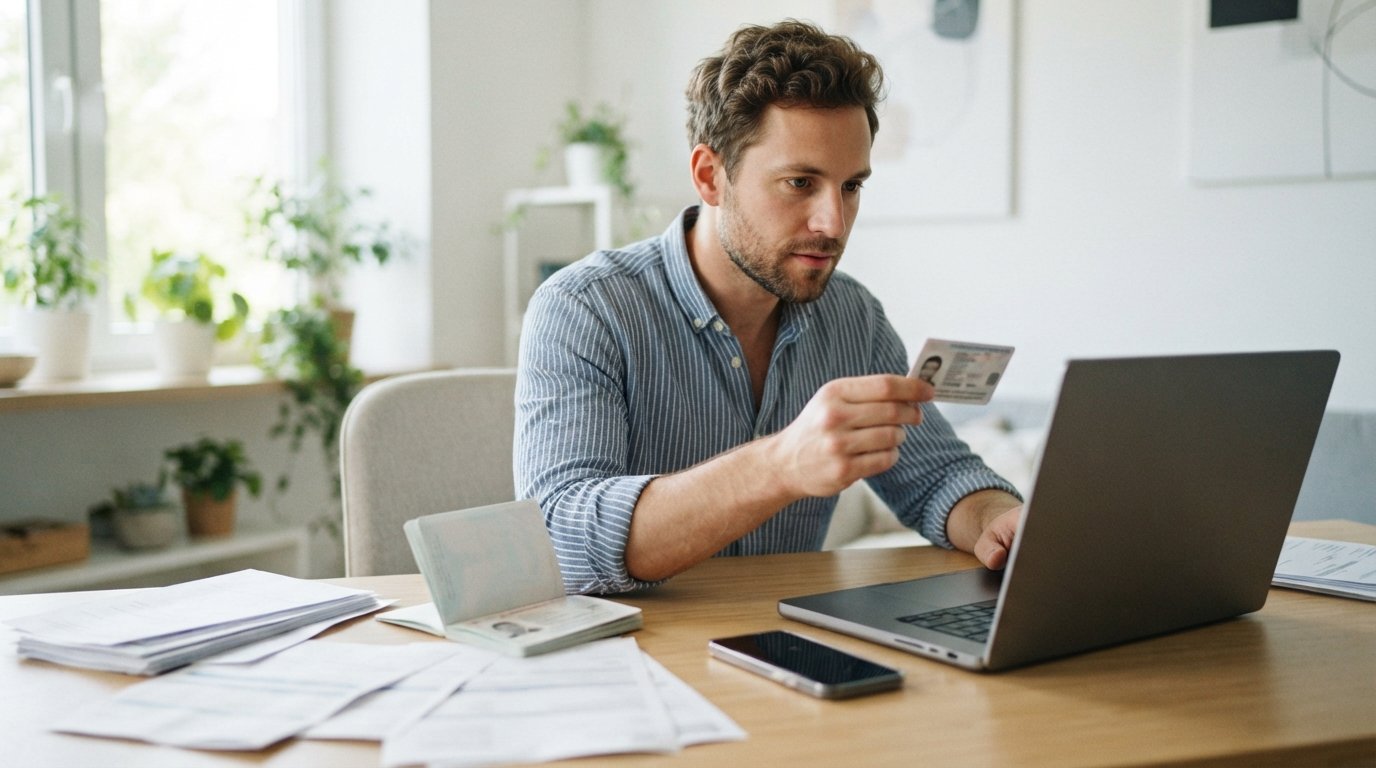
When you need cash quickly, the last thing you want is a delay caused by a missing pay stub or a blurry photo of your ID. Most online loan applications are designed to take just a few minutes, but the process can stall if lenders have to follow up for basic information. The difference between getting funds as soon as the next business day and waiting several days often comes down to preparation. Having a complete set of documents ready before you start can streamline your request and reduce back-and-forth with potential lenders. This guide walks you through the essential documents checklist for a fast online loan application, so you can move through the process with confidence and avoid common holdups.
Why Document Readiness Matters for Online Loan Speed
Online lending platforms, including matching services like CashLoanFunded, rely on third-party lenders to evaluate applications. These lenders need to verify your identity, confirm your ability to repay, and ensure they have accurate banking details for disbursement. When any of these items are missing or unclear, the lender may request additional information, which adds time to the approval process. In many cases, a single missing document can push funding from next business day to several days later.
Preparation also affects your experience with multiple lenders. When you submit a request through a connecting service, your information is shared with a network of lenders. If your file is complete and consistent, lenders can quickly assess your application and present offers. If not, you may receive fewer offers or none at all. Being organized signals responsibility and reduces the risk of errors that could lead to rejection.
Moreover, having documents ready helps you compare offers more effectively. When you know your income and banking details are solid, you can focus on evaluating loan terms, such as APR, repayment schedule, and fees, rather than scrambling to find paperwork. This leads to better borrowing decisions and a smoother overall process.
The Core Documents Lenders Typically Request
Most short-term lenders, including payday, installment, and personal loan providers, ask for a similar set of documents. While specific requirements can vary by lender and state, the following items form the foundation of a fast application. Gathering these in advance will cover the majority of requests.
- Government-issued photo ID: A valid driver's license, state ID, or passport. Ensure the image is clear and all details are legible.
- Proof of income: Recent pay stubs (usually the last 30 days), bank statements showing direct deposits, or other income documentation if self-employed.
- Bank account information: A voided check or bank statement showing your account and routing numbers for direct deposit of funds.
- Social Security number: Needed for identity verification and credit checks.
- Proof of address: A utility bill or lease agreement may be requested, though not always required for small loans.
Keep in mind that lenders may also ask for additional documents depending on your situation, such as a divorce decree for alimony income or a award letter for benefits. However, the five items above are the most common. Having them ready in digital format (PDF or clear photo) will speed up the submission process.
It's also wise to ensure your personal information is consistent across all documents. For example, your name and address on your ID should match the information on your pay stubs and bank statements. Discrepancies can trigger manual reviews and delay funding. If you've recently moved or changed jobs, be prepared to explain any differences.
Identity and Income Verification: Getting the Details Right
Identity verification is a critical step for fraud prevention and regulatory compliance. Lenders need to confirm that you are who you say you are. A clear, color copy of your government-issued ID is usually sufficient. Make sure the expiration date is visible and that there is no glare or shadow obscuring the text. Some lenders may also require a selfie or a second form of ID, but that is less common for small loans.
Proof of income is often the most scrutinized document. Lenders want to see that you have a stable source of income to repay the loan. For traditional employees, recent pay stubs are the standard. Typically, lenders ask for the last two pay stubs or the last 30 days of pay history. If you receive direct deposit, bank statements showing the deposits can also work. Ensure the statements are official, either downloaded from your bank's website or printed at a branch, and that they clearly show your name, account number, and the deposit amounts.
For self-employed applicants, the proof of income format matters significantly. Lenders understand that self-employed individuals may not have traditional pay stubs, but they still need to verify income. Here are some acceptable alternatives:
- Bank statements: At least three months of business or personal bank statements showing consistent deposits.
- Tax returns: The most recent year's tax return, including Schedule C or other self-employment forms.
- Invoices and receipts: A summary of recent invoices or a profit and loss statement prepared by an accountant.
- 1099 forms: If you work as an independent contractor, 1099s can serve as income proof.
When submitting self-employed income documentation, it's helpful to provide a brief explanation of your business and how you receive payments. This context can help lenders assess your income stability more quickly. Avoid sending a disorganized pile of documents; instead, label each file clearly (e.g., "Bank Statement - January 2026") to make review easy.
If you lack a recent pay stub because you started a new job or receive cash payments, don't panic. There are still options. A job offer letter with your start date and salary can sometimes suffice, especially if you have not yet received your first paycheck. Alternatively, you can provide bank statements showing regular cash deposits, though lenders may require additional verification. In some cases, a letter from your employer on company letterhead confirming your employment and income can work. The key is to communicate openly with the lender and provide as much documentation as possible to substantiate your income.
Banking Details and Secure Document Submission
To receive funds, lenders need your banking information. This typically includes your account number and routing number, which you can find on a personal check or in your online banking portal. Some lenders may ask for a voided check to verify the details. Make sure the account is in your name and is active. If you use a savings account, confirm that the lender accepts it; some prefer checking accounts for direct deposit.
Security is paramount when submitting sensitive documents online. Avoid sending documents via text message or unencrypted email, as these methods are not secure and could expose your personal information to interception. Instead, use the lender's secure portal or upload system. CashLoanFunded, for example, uses 256-bit SSL encryption to protect your data during transmission. When you submit a request through a matching service, ensure the site is secure (look for "https" in the URL) and read the privacy policy to understand how your information is handled.
If a lender requests documents via email, check if they offer a secure upload link. If not, consider using a secure file-sharing service that encrypts files and requires a password. Never include your Social Security number or bank account details in the body of an email. When uploading documents, use a scanner or a scanning app to produce clear, high-resolution images. Avoid taking photos with your phone in low light, as blurry images may be rejected and require resubmission, causing delays.
Additionally, be cautious about who you share your documents with. Only provide information to lenders you have verified as legitimate. If you're using a connecting service, ensure it is transparent about its role and does not charge upfront fees. Reputable services like CashLoanFunded never ask for payment to process your request. If you encounter a lender or service that demands payment before funding, treat it as a red flag.
What to Do If You Lack a Recent Pay Stub or Other Documents
Not everyone has a recent pay stub readily available. If you are between jobs, recently started a new position, or work in the gig economy, you may need to get creative. Start by contacting the lender or the matching service's customer support to explain your situation. Many lenders have alternative verification methods, such as verbal employment verification or accepting bank statements that show consistent deposits.
If you are self-employed and haven't filed taxes recently, consider creating a profit and loss statement. You can use accounting software or a simple spreadsheet to summarize your income and expenses for the last few months. Have it signed and dated to add credibility. Alternatively, you can provide a signed affidavit of income, though this is less common and may not be accepted by all lenders.
For those who receive government benefits, such as Social Security or disability, an award letter or recent benefit statement can serve as proof of income. Similarly, if you receive alimony or child support, a court order or divorce decree combined with bank statements showing the deposits can work. Always check with the lender about what they accept before submitting.
If you are missing a document entirely, ask the lender if they can proceed with alternative verification. Some lenders may accept a combination of documents that together prove your identity and income. For example, a utility bill in your name plus a bank statement showing regular deposits might suffice. The key is to be proactive and communicate clearly. If your application is denied due to missing documents, you can often reapply once you have them ready. For more guidance on what to do after a denial, see our article on what happens after a loan application denial.
Organizing Your Documents for a Smooth Application
Before you sit down to apply, take a few minutes to organize your documents digitally. Create a folder on your computer or cloud storage and label it with your name and the date. Inside, save each document as a separate PDF or image file with a clear name, such as "ID_JohnDoe" or "PayStub_Jan2026." This makes it easy to upload the correct files when prompted. If you are applying through a service that connects you with multiple lenders, you may need to submit documents more than once; having them organized saves time.
Also, check the expiration dates on your ID and any other documents. An expired ID will not be accepted, so renew it if necessary before applying. Ensure your bank statements are recent, typically within the last 30 to 60 days. If you have moved recently, update your address with your bank and employer to avoid inconsistencies.
Finally, consider the format requirements. Most lenders accept PDF, JPG, and PNG files. Avoid sending files that are too large (over 10MB) or too small (under 100KB), as they may be rejected. If you are scanning documents, use a resolution of at least 300 DPI to ensure clarity. Following these steps will minimize the risk of technical issues that could delay your application.
For those who want to compare loan offers from multiple lenders, using a service like FreeQuotes.Loans can be a convenient way to submit one request and receive personalized offers. Just ensure you have your document checklist ready before you start. Remember, CashLoanFunded is a free connecting service that does not charge you fees, and you are never obligated to accept any offer. By preparing your documents in advance, you can speed up the process and increase your chances of getting the funds you need quickly.