Talking to Your Lender Before You Miss a Payment
Reach out before the due date to protect your credit and unlock repayment options. Call (833)-501-3363 for guidance on communicating with your lender.
By Thomas Young
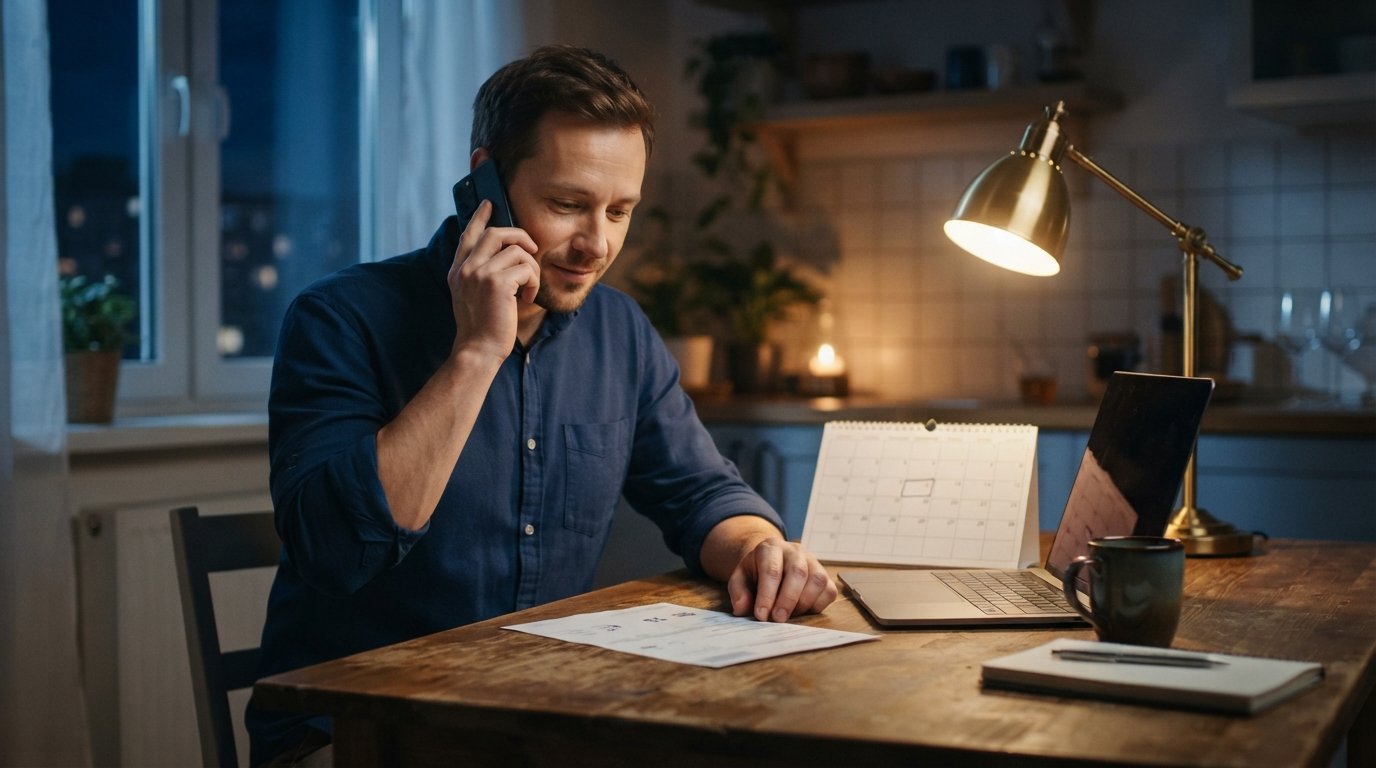
Your rent is due, the car needs a repair, and the loan payment hits in four days. You already know the money will not stretch. In that moment, silence feels safer than a phone call. But silence is the one move that almost always makes the situation worse. Communicating with your lender before you miss a payment is the single most effective step you can take to protect your credit, your wallet, and your peace of mind. Lenders deal with borrowers in trouble every day. The ones who call early usually get options. The ones who go dark usually get fees, collections, and a damaged credit report.
This guide walks you through exactly how to start that conversation, what to say, what to have ready, and what outcomes you can realistically expect. Whether you are facing a one-time cash crunch or a deeper income problem, the playbook is the same: act early, be honest, and get any agreement in writing.
Why Calling Before the Due Date Changes Everything
From the lender's perspective, a borrower who calls before the due date looks very different from one who disappears. Early contact signals responsibility. It tells the lender you are paying attention, you respect the obligation, and you want to resolve the problem. That signal matters because lenders have entire departments (often called hardship or loss mitigation teams) built to handle exactly this situation. Those departments exist to keep loans performing, not to punish borrowers who speak up.
Timing also affects your options directly. Once a payment is officially late, automated systems take over. Late fees post, the account status changes, and in many cases the delinquency is reported to the credit bureaus. Reversing those steps is much harder than preventing them. A call placed five days before the due date can often result in a due date change or a short deferment with no negative marks at all. A call placed five days after the due date often starts with an apology and ends with a fee.
There is also a practical reason to move early: your own leverage. Before you miss a payment, you are a customer in good standing asking for help. After you miss a payment, you are a delinquent account being managed by a collections workflow. The same request carries far more weight in the first scenario. If you are already exploring short-term borrowing options to bridge a gap, understanding how banks process funded loans from approval to payout can help you time your request so the funds arrive before the due date rather than after it.
What to Say and What to Have Ready
A successful call is mostly preparation. Lenders want to solve a problem, but they need facts to do it. Before you dial, gather your account information, your loan number, and a clear picture of your income and expenses for the next 30 to 60 days. You do not need a polished speech, but you do need to be specific. Vague requests like "I cannot pay this month" are harder to approve than specific ones like "I can pay $150 on the 15th and $150 on the 30th."
Here is what to have in front of you when you call or email:
- Your loan or account number, plus your personal details for verification
- The exact payment amount, due date, and how many payments remain
- A short explanation of what changed (job loss, medical bill, car repair, reduced hours)
- A realistic budget showing what you can pay and when
- Any supporting documents, such as a layoff notice, medical invoice, or updated pay stub
When you make contact, lead with the facts and the ask. A simple script works: "I am calling before my payment on the 12th because my hours were cut. I can pay $100 on the 12th and the rest on the 26th. Can we set that up?" That sentence tells the lender who you are, why you are calling early, what you can do, and what you want. It is dramatically more effective than waiting on hold to say you do not have the money.
If you reach a front-line representative who cannot help, ask politely to speak with the hardship or loss mitigation department. Those teams have authority that general customer service does not. Keep notes on who you spoke with, the date and time, and what was promised. If your conversation happens by email or chat, save the transcript. This record protects you if the agreement is later disputed.
Possible Outcomes: Due Date Changes, Repayment Plans, and Partial Payments
Lenders are not charities, but they are pragmatic. A modified payment almost always beats a default, so most institutions have several tools available. The specific menu depends on your lender, your history, and your state's regulations, but the common options fall into a few categories.
A due date change is the simplest fix. If your paycheck lands on the 20th but the payment is due on the 15th, many lenders will move the date permanently or for a few cycles. This solves timing problems without changing the total amount owed. A short deferment or forbearance pushes one or more payments to the end of the loan, often with interest continuing to accrue. It buys breathing room but costs a little more overall.
A repayment plan restructures the schedule. The lender might lower your monthly payment and extend the term, or split a single payment into two smaller ones. A partial payment arrangement lets you pay part now and the rest by a defined date, usually without the account being marked delinquent. Some lenders also offer hardship programs with reduced interest for a set period. Ask specifically what is available, because representatives do not always volunteer every option.
One caution: get the agreement in writing before you rely on it. Verbal promises from a phone call are difficult to enforce. Ask for confirmation by email or through your online account portal, and confirm the exact new dates and amounts. If the lender will not put it in writing, treat the arrangement as uncertain and plan accordingly.
What Happens If You Wait: Fees, Rates, and Credit Reporting
The cost of silence compounds quickly. A missed payment typically triggers a late fee, and some lenders add additional fees at 15 or 30 days past due. Interest continues to accrue, and on some products the rate itself can increase after a missed payment. For short-term loans, which already carry high annual percentage rates, those add-ons can turn a manageable balance into a much larger one within weeks.
The credit consequences are often the most expensive part. Most lenders report delinquencies to the major credit bureaus once a payment is 30 days late, and a single missed payment can stay on your report for up to seven years. That mark can affect future loan approvals, apartment applications, insurance rates, and even some job screenings. If you are already working with a thin credit file, one delinquency can set you back significantly. Communicating with your lender before you miss a payment is the only reliable way to keep that mark off your report entirely.
There is also a collections risk. Accounts that remain unpaid can be sold or assigned to collections agencies, which adds pressure and can lead to legal action depending on the loan type and state. Borrowers who call ahead rarely end up in that pipeline. Borrowers who screen calls often do.
When the Problem Is Recurring, Not Temporary
One late month is a timing problem. Three late months in a row is a structural problem, and it deserves a different response. Warning signs include routinely borrowing from one source to pay another, relying on payday-style products to cover regular expenses, or finding that your income simply does not cover your obligations even after cutting back. If any of those sound familiar, a one-time deferment will only delay the inevitable.
In that situation, the conversation with your lender should be broader. Ask about long-term hardship programs, loan modification, or settlement options. At the same time, address the underlying budget: reduce fixed costs, contact other creditors before they contact you, and consider nonprofit credit counseling. If you need a bridge while you restructure, be deliberate about it. Services such as AdvanceCash connect U.S. consumers with third-party lenders for short-term options, but these products are designed for temporary gaps, not for ongoing shortfalls. Used once, they can solve a timing problem. Used repeatedly, they deepen it.
It also helps to know your rights. Lenders must follow fair lending and debt collection rules, and you are entitled to clear information about your account. If a representative is unhelpful or hostile, escalate politely and document the interaction. You can also ask for the call to be reviewed by a supervisor. Persistence, paired with a reasonable plan, usually gets results.
A Simple Action Plan for the Next 48 Hours
If a payment is coming due and the money is not there, do not wait for the due date to pass. Block out one hour today and take these steps in order.
- Open your loan documents and confirm the payment amount, due date, and lender contact information.
- Build a bare-bones budget for the next 60 days showing exactly what you can pay and when.
- Call the lender, state your situation and your proposed plan, and ask what options are available.
- Request written confirmation of any agreement and save it with your notes.
- If the problem looks recurring, ask about hardship programs and contact a nonprofit credit counselor.
None of these steps require perfect credit or extra money. They require a phone call and a little honesty. Lenders hear from borrowers in trouble constantly, and the ones who reach out first are the ones they work with most willingly.
Communicating with your lender before you miss a payment will not magically create cash, but it will keep you in control of the conversation. It protects your credit report, limits fees, and opens doors to arrangements that are invisible to borrowers who stay silent. The due date is not a deadline for asking for help; it is the last comfortable moment to do it. Make the call while you still have options, and put the agreement in writing before you breathe easy.