Steps to Take Immediately If You Suspect an Online Loan Scam
Act fast if you suspect an online loan scam. Call 8335013363 for guidance on protecting your money and identity.
By Owen Mitchell
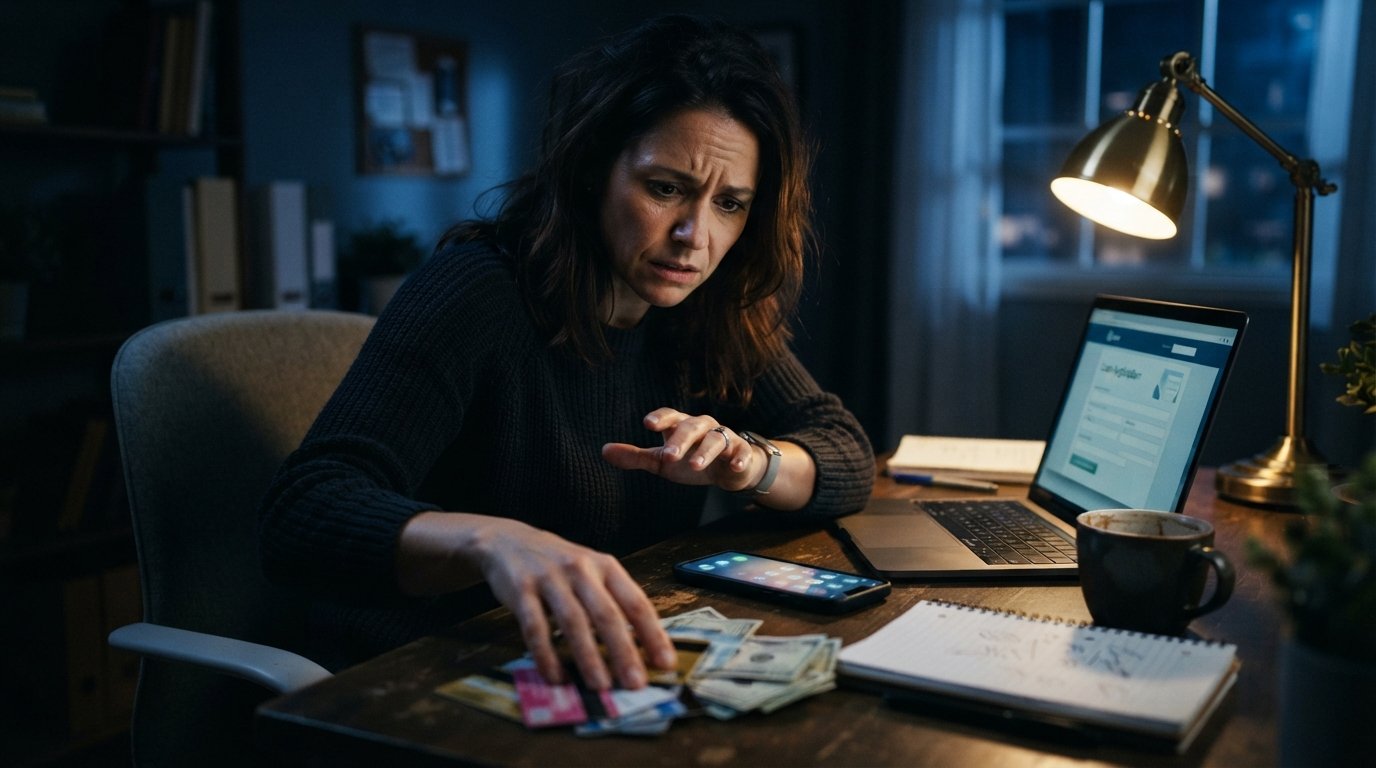
You submitted an online loan request, paid a fee, and now the lender has vanished. Or perhaps you received an approval call demanding gift cards before disbursement. In that moment of rising panic, your next actions matter enormously. Moving quickly and deliberately can limit financial damage, protect your identity, and preserve your ability to recover funds. This guide walks you through the exact steps to take immediately if you suspect an online loan scam, from cutting contact to filing reports, and explains how legitimate services like AdvanceCash operate differently so you can spot the warning signs earlier next time.
Step 1: Stop All Communication and Do Not Send More Money
The single most important action is to halt contact with the suspected scammer. Scammers rely on urgency, fear, and repeated small requests that escalate over time. If you have already sent money, sending more in hopes of unlocking a larger loan is a classic trap. Legitimate lenders do not ask for upfront fees to release funds, and no real loan requires payment via gift cards, wire transfers, or cryptocurrency.
Block the phone number, email address, and any messaging app handles the scammer used. Do not click additional links they send, and do not download attachments. If they threaten you with legal action or arrest, recognize that these are empty intimidation tactics. Real law enforcement and courts do not operate through threatening text messages or demand immediate payment through unusual channels. Cutting contact prevents further manipulation and gives you mental space to act rationally.
Step 2: Document Everything Before You Forget Details
Memory fades quickly under stress, so capture the evidence while it is fresh. Take screenshots of every text message, email, chat transcript, and social media interaction. Save the loan offer page, the application form you filled out, and any documents the scammer sent (even if they appear fake). Note the exact dates and times of each contact, the phone numbers used, email addresses, and any names or company names mentioned.
If you provided banking information, log into your account and download recent transaction records. If you shared your Social Security number or driver's license details, make a written note of what was disclosed and when. This documentation becomes essential when you file reports with banks, credit bureaus, and law enforcement. It also helps you prove your case if the scammer tries to dispute your account of events.
Step 3: Contact Your Bank or Credit Union Immediately
Speed is critical when money has left your account. Call your bank's fraud department right away and explain that you were the victim of a suspected online loan scam. If you authorized a payment, ask whether the transaction can be stopped or reversed. If the scammer used your account information without authorization, the bank may treat it as fraud and initiate an investigation. In many cases, you have limited time to dispute charges, so do not delay.
Request that your account be frozen or monitored for suspicious activity. If you used a debit card, ask about provisional credit while the dispute is resolved. If you sent money through a wire transfer, the bank may be able to recall it if you act within hours. For payments made through apps like Zelle, Venmo, or Cash App, contact the app's support team separately, but understand that recovery is harder because these transfers are often instant and final. Your bank can guide you on next steps specific to your situation.
Step 4: Report the Scam to the Right Authorities
Filing official reports creates a paper trail that can help you recover funds and helps authorities track scam operations. Several agencies handle different aspects of online loan fraud, and reporting to more than one is often wise.
- Federal Trade Commission (FTC): Report at ReportFraud.ftc.gov. The FTC collects data on scams and can share it with law enforcement nationwide.
- FBI Internet Crime Complaint Center (IC3): File at ic3.gov if the scam involved internet communications, which is almost always the case.
- Consumer Financial Protection Bureau (CFPB): Submit a complaint at consumerfinance.gov if the scammer posed as a lender or financial institution.
- State Attorney General: Your state's AG office handles consumer protection and can take action against fraudulent businesses operating within its jurisdiction.
- Local Police: Filing a local report may be required by your bank or insurer and can help if the scammer is later identified.
Keep copies of every report you file. Include the report numbers in your documentation. When you contact your bank or credit bureaus, having these reports demonstrates that you took the scam seriously and acted responsibly.
Step 5: Protect Your Identity and Credit
If you shared personal information such as your Social Security number, date of birth, or bank account details, assume that identity theft is a real risk. Place a fraud alert or credit freeze with all three major credit bureaus: Equifax, Experian, and TransUnion. A fraud alert lasts one year and requires lenders to verify your identity before extending credit. A credit freeze is more restrictive and prevents new accounts from being opened in your name until you lift it.
Review your credit reports for unauthorized inquiries or new accounts. You can obtain free reports at AnnualCreditReport.com. If you spot anything suspicious, dispute it immediately with the bureau. Consider enrolling in identity theft protection if you want ongoing monitoring, though many basic protections are free. Change passwords on any accounts that shared the same email or password as the loan application, and enable two-factor authentication wherever possible.
Step 6: Watch for Follow-Up Scams
Scammers often share or sell victim information to other criminals. After an initial scam, you may receive calls from someone claiming to be a recovery specialist, a government agent, or a lawyer who can get your money back for a fee. These are almost always secondary scams. Legitimate recovery services do not demand upfront payment, and government agencies do not call demanding immediate action.
Be skeptical of any unsolicited contact that references your recent scam experience. Do not provide additional personal or financial information. If someone claims to be from your bank, hang up and call the bank directly using the number on your card or statement. Awareness of follow-up tactics is part of the steps to take immediately if you suspect an online loan scam because it prevents a bad situation from getting worse.
Step 7: Understand How Legitimate Lenders Operate
One of the best defenses against future scams is knowing what a real lending process looks like. Legitimate online lending platforms, including services like online funding approval service, connect borrowers with third-party lenders and do not charge upfront fees to consumers. They clearly disclose that they are not direct lenders, provide terms before you sign, and never ask for payment via gift cards or wire transfers.
When you submit a request through a reputable platform, you can review offers from multiple lenders, compare APRs and repayment terms, and choose whether to accept. You are never obligated to take a loan. Funds are typically disbursed after you e-sign the lender's terms, and the money arrives in your bank account through normal channels, not through a prepaid card you must purchase yourself.
Step 8: Learn the Red Flags So You Can Spot Them Early
Prevention is always better than recovery. Scammers often use similar tactics, and recognizing them early can save you time, money, and stress. Here are common warning signs of an online loan scam.
- Upfront fees: Requests for insurance, processing, or verification fees before loan disbursement are illegal in many jurisdictions and are a major red flag.
- Guaranteed approval: No legitimate lender can guarantee approval before reviewing your information, especially if you have bad credit.
- Pressure tactics: High-pressure calls, threats, or demands for immediate action are designed to prevent you from thinking clearly.
- Unusual payment methods: Gift cards, cryptocurrency, wire transfers to individuals, or peer-to-peer apps are preferred by scammers because they are hard to trace.
- No physical address or license: Legitimate lenders provide a physical business address and are licensed in the states where they operate.
If any of these elements appear, step back and verify the lender independently. Search for the company name plus the word scam, check with your state's financial regulator, and look for a clear privacy policy and terms of service. Trust your instincts: if something feels off, it probably is.
Step 9: Know Your Rights and Legal Options
Consumer protection laws exist to help victims of fraud. Depending on your state, you may have the right to sue the scammer for damages, though identifying and locating them can be difficult. The Fair Credit Billing Act and Electronic Fund Transfer Act offer limited protections for certain types of transactions, but they do not cover all scam scenarios. Your bank's policies and the payment method used will determine what recourse is available.
If you used a credit card, you have stronger dispute rights than with debit cards or wire transfers. Contact your card issuer immediately and dispute the charge in writing. For unauthorized electronic transfers, notify your bank within two business days to limit your liability. Keep records of all communications. In some cases, filing a complaint with the CFPB or your state attorney general can lead to broader investigations that help other victims as well.
Step 10: Take Care of Your Financial and Emotional Well-Being
Falling victim to a scam is stressful and can feel embarrassing, but it is not your fault. Scammers are professionals who design their schemes to exploit trust and urgency. Acknowledge the emotional toll and give yourself permission to seek support. Talk to a trusted friend or family member, or contact a consumer advocacy organization that helps fraud victims.
Rebuilding financial stability takes time. Focus on the steps you can control: monitoring your accounts, communicating with your bank, and gradually restoring your credit if it was affected. If you need a legitimate loan for an emergency, work with a reputable platform that connects you with licensed lenders, discloses all terms upfront, and never demands payment before funding. By staying informed and cautious, you can protect yourself and move forward with confidence.
Taking the steps to take immediately if you suspect an online loan scam is about more than damage control. It is about reclaiming your power, protecting your future, and helping authorities stop the criminals who prey on people in need. Act quickly, document thoroughly, and use the legitimate resources available to you.