Psychology of Debt: How to Make Smarter Borrowing Decisions
Master the psychology of debt and how to make smarter borrowing decisions. Call 8335013363 for guidance on responsible borrowing.
By Owen Mitchell
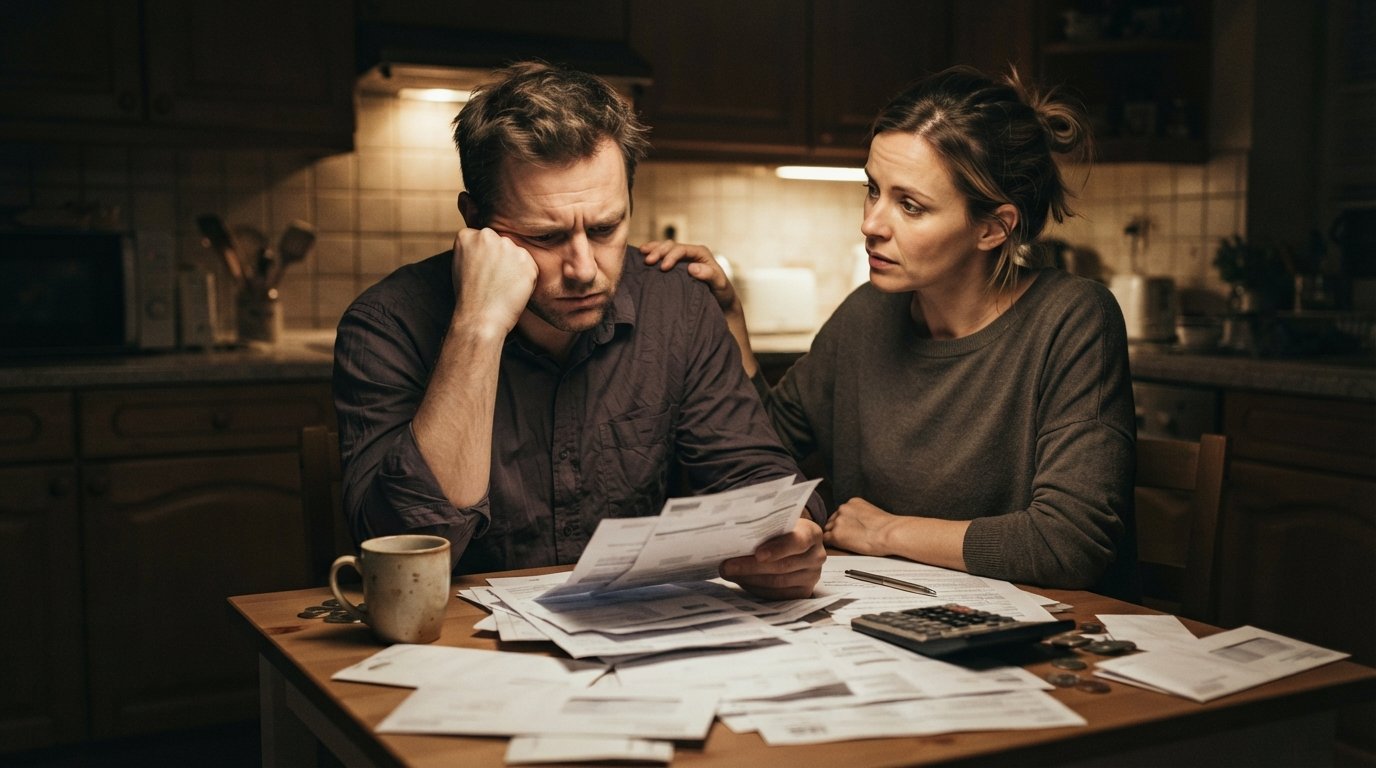
Your heart races when the car breaks down, the medical bill arrives, or the rent is due before your paycheck clears. In that moment of financial pressure, the brain does something predictable: it seeks the fastest escape route. That escape route often looks like a loan. Understanding the psychology of debt and how to make smarter borrowing decisions is not about willpower or spreadsheets alone. It is about recognizing the mental shortcuts, emotional triggers, and cognitive biases that shape every financial choice you make, especially when you are stressed, rushed, or uncertain about the future.
The field of behavioral economics has spent decades documenting how humans deviate from the perfectly rational borrower model. We discount the future in favor of immediate relief. We anchor on the first number we see. We convince ourselves that a small monthly payment is affordable without calculating the total cost. These tendencies are not character flaws; they are deeply wired survival mechanisms that served our ancestors well but can sabotage modern financial health. When you understand why your brain behaves this way, you gain the ability to pause, evaluate, and choose borrowing options that actually improve your situation rather than deepen the hole.
Why Your Brain Treats Debt Differently Than Other Risks
Debt occupies a strange psychological space. Unlike a physical threat, it does not trigger an immediate fight-or-flight response. Instead, it activates what researchers call temporal discounting, the tendency to value immediate rewards far more than delayed consequences. When you need $500 today to fix your transmission, the future cost of repaying $650 over the next few months feels abstract and distant. The brain prioritizes the here and now, releasing tension the moment you secure the funds. That relief is real, but it comes with a hidden price tag that your emotional brain conveniently ignores.
Another powerful force is the optimism bias. Most borrowers genuinely believe they will repay on time, even when their income is irregular or their expenses are unpredictable. This bias leads people to underestimate the true cost of borrowing and overestimate their future ability to manage payments. Lenders understand this psychology and design products that feel manageable in the moment (small minimum payments, extended terms) while maximizing total interest collected over time. Recognizing this asymmetry is the first step toward making smarter decisions.
Finally, debt carries a social and emotional stigma that can cloud judgment. Many people avoid reading the fine print because they fear what they will find. Others feel ashamed to comparison shop or negotiate, worried that asking questions signals desperation. These emotional barriers prevent borrowers from gathering the information they need to make rational choices. The antidote is not to suppress emotion but to acknowledge it, then deliberately shift into a analytical mindset before signing anything.
The Hidden Biases That Drive Bad Borrowing Choices
Cognitive biases are mental shortcuts that usually help us navigate a complex world, but they become dangerous when applied to financial products. One of the most common is anchoring. If a lender advertises a loan with a 24% APR, that number becomes your reference point. When a second lender offers 36%, it feels expensive by comparison, even though both rates are extremely high relative to mainstream credit. Without an external benchmark, you have no way to know whether 24% is reasonable or predatory.
Present bias is another culprit. It explains why borrowers choose a payday loan with a lump-sum repayment over an installment loan with smaller, spread-out payments. The payday loan feels simpler and faster, and the full repayment is weeks away. The installment loan requires ongoing attention and multiple payments, which feels burdensome right now. But the payday loan often carries a much higher effective annual rate and a balloon payment that can trigger a cycle of reborrowing. Present bias favors the option that requires the least immediate effort, not the one that costs the least overall.
Social proof and scarcity also play significant roles. When a website displays messages like "3 people are viewing this offer right now" or "funds available for a limited time," they activate a fear of missing out. This pressure short-circuits deliberate thinking. Legitimate lenders do not need to manufacture urgency. If you feel rushed, that is a signal to slow down, not speed up.
To counteract these biases, try this simple framework before accepting any loan offer:
- Calculate the total repayment amount, not just the monthly payment. Multiply the payment by the number of payments and compare that to the principal.
- Convert all rates to APR so you can compare apples to apples across different loan types and terms.
- Identify the emotional trigger that is pushing you toward a quick decision (fear, urgency, shame, exhaustion) and name it out loud.
- Wait 24 hours before accepting any offer, unless it is a genuine emergency where delay causes immediate harm.
- Ask what happens if you cannot repay on the original schedule. Understand rollover fees, late penalties, and collection practices before you sign.
This framework does not eliminate emotion, but it creates a deliberate pause between stimulus and response. That pause is where smarter borrowing decisions live.
How Emotions Shape the Loan Application Process
The moment you click "apply" on a loan website, you are often in a heightened emotional state. Financial stress activates the amygdala, the brain region responsible for threat detection, and suppresses activity in the prefrontal cortex, which handles long-term planning and impulse control. This neurological shift explains why people make financial decisions under stress that they would never make when calm. They accept the first offer. They skip reading the terms. They borrow more than they need because the extra amount is available.
Lenders and lead-generation platforms are aware of this psychology. Some design their interfaces to minimize friction and maximize conversion, which can be helpful when you are genuinely in a bind. But it also means you must bring your own guardrails. Before you submit any application, write down three numbers: the exact amount you need, the maximum total repayment you can afford, and the latest date by which you must have the funds. These three anchors keep you grounded when the application process tries to pull you toward larger amounts or longer terms.
It also helps to understand the difference between a need and a want in the context of borrowing. A need is an expense that, if not paid, causes immediate and severe harm: eviction, utility shutoff, medical emergency, or loss of transportation to work. A want is an expense that improves your quality of life but can be delayed, reduced, or financed through other means. The psychology of debt often blurs this line because stress makes everything feel urgent. A written list of genuine needs versus deferrable wants can restore clarity.
Practical Steps for Smarter Borrowing Decisions
Making smarter borrowing decisions requires more than awareness; it requires a repeatable process. The process begins before you ever need a loan. Building a small emergency fund, even $500, creates a psychological buffer that reduces the desperation that leads to poor choices. It also gives you time to research options rather than accepting the first offer that appears.
When you do need to borrow, start by exploring all available channels. Traditional banks and credit unions often offer lower rates but may have stricter eligibility requirements. Online lenders and connecting services like AdvanceCash can provide access to a network of third-party lenders who work with a wider range of credit profiles. These platforms are not direct lenders; they connect you with lenders who may present offers. The key is to request offers from multiple sources and compare them side by side.
For those exploring debt consolidation as a strategy, our guide on personal loans for debt consolidation explains how combining high-interest debts into a single loan can simplify repayment and potentially reduce your overall interest rate. However, consolidation only works if you address the underlying spending patterns that created the debt in the first place. Otherwise, you risk running up the same balances again while carrying a new loan payment.
Here is a step-by-step process for evaluating any loan offer:
- Define your borrowing limit. Decide in advance the maximum amount you will borrow and the maximum monthly payment you can sustain without disrupting essential expenses.
- Gather at least three offers. Use a connecting service or contact multiple lenders directly to see a range of APRs, terms, and fees.
- Read the full terms. Look for origination fees, prepayment penalties, late fees, rollover options, and the consequences of default.
- Calculate the total cost of credit. Add all fees and interest to the principal to see the true price of the loan.
- Check your credit report. Knowing your score and history helps you predict which offers you qualify for and avoid unnecessary hard inquiries.
- Make a repayment plan before you accept. Identify the exact source of funds for each payment and set calendar reminders.
- Commit to no new debt until this loan is repaid. This rule prevents the debt stacking that traps many borrowers.
Following this process takes time, but it transforms borrowing from a reactive scramble into a deliberate financial decision. The goal is not to avoid debt entirely, since some borrowing can be a rational tool for managing cash flow. The goal is to ensure that every loan you take moves you closer to stability, not further from it.
Recognizing When a Loan Is the Wrong Tool
Not every financial problem should be solved with a loan. The psychology of debt can trick you into borrowing for expenses that would be better handled through negotiation, budgeting, or temporary lifestyle adjustments. Before you apply, ask whether the expense can be reduced, delayed, or paid in installments directly to the service provider. Many medical providers, landlords, and utility companies offer payment plans that do not involve interest or credit checks.
Short-term loans, including payday loans and cash advances, are designed for temporary financial gaps. They carry high APRs and fees, and they are not intended as long-term solutions. If you find yourself relying on them repeatedly, that is a signal that your income and expenses are misaligned in a way that a loan cannot fix. In those cases, the smarter decision may be to seek financial counseling, negotiate with creditors, or explore nonprofit debt management programs.
It is also important to recognize when a loan offer is predatory. Red flags include pressure to act immediately, unclear fee structures, required access to your bank account for automatic withdrawals, and no consideration of your ability to repay. Legitimate lenders will provide clear terms, give you time to review them, and never promise guaranteed approval before reviewing your information.
Understanding the psychology of debt and how to make smarter borrowing decisions ultimately comes down to self-awareness and preparation. Your brain is wired to seek relief from financial stress, and that wiring can lead you toward expensive, high-risk products if you are not careful. By naming your emotional triggers, calculating total costs, comparing multiple offers, and planning repayment before you sign, you shift from reacting to choosing. That shift does not eliminate financial challenges, but it ensures that when you do borrow, you do so on terms that support your long-term stability rather than undermine it.