Prepayment Penalty on Short Term Loan: What Borrowers Should Know
Understand prepayment penalties on short term loans. Call (833)-501-3363 for guidance on avoiding surprise fees and saving money.
By Owen Mitchell
You have scraped together the cash to pay off your short term loan early, only to discover a clause in your contract that imposes an extra fee for doing so. This frustrating scenario is more common than many borrowers realize, and it can turn a smart financial move into an unexpected expense. Understanding how prepayment penalties work on short term loans is essential before you sign any agreement or send that final payment. This guide walks you through what these penalties are, where they are restricted, how to spot them in your contract, and the exact steps to take if you want to pay off your loan ahead of schedule without triggering unnecessary costs.
What Is a Prepayment Penalty and Why Do Lenders Charge It?
A prepayment penalty is a fee that some lenders charge when you pay off a loan before its scheduled maturity date. On a short term loan, such as a payday loan, installment loan, or personal loan, this penalty is typically a percentage of the remaining principal, a flat fee, or a specified number of months worth of interest. The penalty is not universal; it depends entirely on the lender and the terms you agreed to in your contract. Lenders justify these fees by pointing to the lost interest income they would have collected if you had made payments according to the original schedule. When you pay early, the lender earns less profit than projected, so the penalty helps offset that shortfall.
For borrowers, the penalty creates a conflict. Paying off debt early is generally considered a responsible financial move because it reduces the total interest you pay and frees up your monthly budget. However, if the penalty is steep enough, it can erase the savings you would have gained. For example, a $1,500 installment loan with a 20 percent prepayment penalty would cost you $300 just to pay it off early, which might be more than the interest you would save by eliminating the remaining payments. The key is to run the numbers before making any decisions.
It is also important to distinguish between a prepayment penalty and simple interest. With simple interest loans, you only pay interest for the days you actually hold the money. If you pay early, you naturally pay less interest. A prepayment penalty is an additional charge layered on top of that, not a replacement for interest. Some lenders structure their loans so that interest is front-loaded, meaning most of your early payments go toward interest rather than principal. In those cases, paying off the loan early may not save you as much as you expect, even without a formal penalty.
Where Prepayment Penalties Are Restricted or Banned
The legality of prepayment penalties varies significantly depending on the type of loan and the state where you live. In the United States, federal law prohibits prepayment penalties on certain mortgage loans, but short term loans fall under a patchwork of state regulations. Some states have strict consumer protection laws that ban prepayment penalties on payday loans and small installment loans, while others allow them with few restrictions. For instance, California has some of the strongest protections against prepayment penalties on consumer loans, whereas states like Texas and Florida have more permissive rules. If you are considering a short term loan, it is crucial to check your state's specific regulations. The Consumer Financial Protection Bureau (CFPB) provides resources that outline consumer rights, but state-level laws often provide the most direct guidance.
Even in states where prepayment penalties are allowed, they are more common on certain loan types than others. Payday loans, which are typically due in a single payment within 30 days, rarely carry prepayment penalties because the loan term is so short that early payoff offers little benefit to the borrower. Installment loans, which are repaid over several months, are more likely to include a prepayment penalty clause. Personal loans from online lenders may also include such fees, though many reputable lenders advertise no prepayment penalties as a selling point. Auto title loans and pawn loans sometimes have their own rules, but the general trend is that the shorter the loan term, the less likely a prepayment penalty will apply, simply because there is less interest at stake.
It is also worth noting that some lenders do not charge a formal penalty but instead use a precomputed interest method. With precomputed interest, the total interest for the entire loan term is calculated upfront and added to your principal. If you pay early, you are still responsible for all that precomputed interest, which functions like a penalty even if it is not labeled as one. Always ask your lender whether the loan uses simple interest or precomputed interest, as this distinction can have a major impact on your early payoff savings.
How to Check Your Lender Agreement for Early Payoff Language
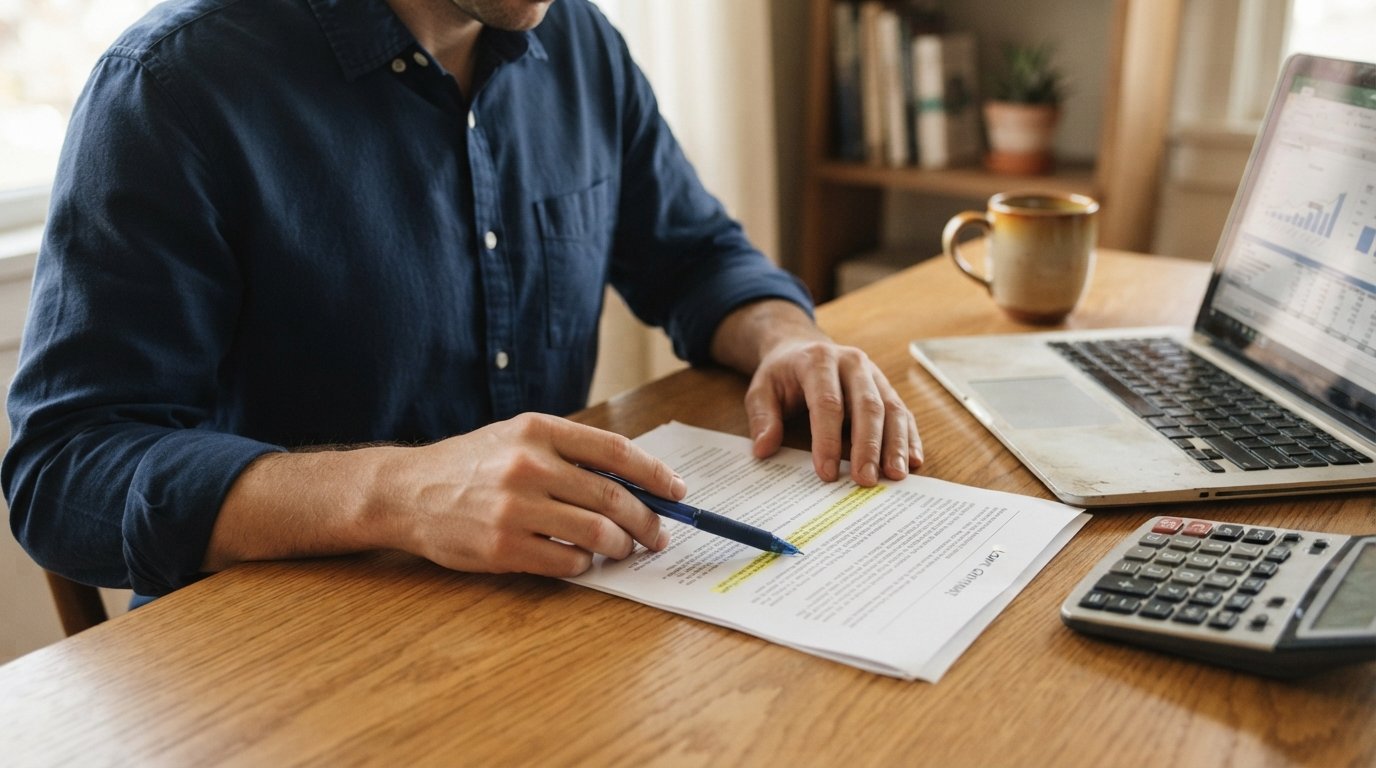
Before you sign any loan agreement, take the time to read the fine print specifically looking for prepayment terms. The language may not always use the phrase "prepayment penalty." Instead, it might say something like "early payoff fee," "prepayment charge," or "minimum interest charge." Look for sections titled "Prepayment," "Early Repayment," or "Fees." If you already have a loan, dig out your copy of the contract and review it carefully. If you cannot find your copy, request one from your lender; they are required to provide it upon request. Pay attention to whether the penalty is a flat fee, a percentage of the remaining balance, or a required minimum amount of interest. Also, check whether the penalty applies only during a certain window, such as the first six months, or for the entire life of the loan.
If you are shopping for a short term loan, ask the lender directly about prepayment penalties before you submit an application. A trustworthy lender will disclose this information clearly. If a lender is evasive or claims there is no penalty but then presents a contract with vague language, consider that a red flag. In our guide on how accurate funding estimates are, we explain how to evaluate loan offers and understand the true cost of borrowing, which includes checking for hidden fees like prepayment penalties. Remember that CashLoanFunded connects you with third-party lenders, and each lender sets its own terms, so always review the specific agreement from the lender making the offer.
When reading the contract, pay special attention to the following clauses, which often contain prepayment terms:
- Prepayment clause: Directly states whether you can pay early and what fee, if any, applies.
- Interest calculation method: Tells you if interest is simple, precomputed, or accrues daily, which affects your savings.
- Default provisions: Sometimes a prepayment penalty is triggered if you refinance or pay off the loan using funds from another lender.
- Payoff quote requirements: Some lenders require you to request a written payoff quote before sending a final payment, and failing to do so may result in an incomplete payoff.
If you find a prepayment penalty in your contract, do not panic. You still have options. You can calculate whether paying early makes financial sense, negotiate with the lender to waive the fee, or simply continue with the original payment schedule if the penalty outweighs the savings. The worst thing you can do is ignore the clause and send a payment that you think pays off the loan, only to find out later that you still owe a penalty and possibly additional interest.
When Paying Early Saves Money Versus When It Does Not
Paying off a short term loan early can be a smart move, but only if the math works in your favor. To determine whether you will actually save money, you need to compare the total cost of the loan if you stick to the original schedule versus the total cost if you pay early including any penalty. Start by finding out your payoff amount, which is the remaining principal plus any accrued interest and fees. Then add the prepayment penalty, if applicable. Compare that sum to the total of all remaining scheduled payments. If the early payoff amount is lower, you save money. If it is higher, you are better off sticking to the schedule.
Here is a simple framework to evaluate your situation:
- Gather your loan documents. Find the original loan amount, interest rate, repayment schedule, and any prepayment penalty details.
- Request a written payoff quote. Contact your lender and ask for the exact amount required to pay off the loan today. This quote should include any penalties or fees.
- Calculate remaining scheduled payments. Multiply your monthly payment by the number of payments left. This gives you the total you would pay if you do not pay early.
- Compare the two totals. If the payoff quote is less than the total remaining payments, paying early saves you money. If it is more, you may want to reconsider.
In many cases, paying early on a simple interest loan with no prepayment penalty will save you money because you avoid interest that would have accrued over the remaining months. However, if the loan has a prepayment penalty equal to several months of interest, the savings may vanish. For example, suppose you have a $2,000 installment loan with a 24 percent annual percentage rate (APR) and 12 months remaining. The total remaining payments might be around $2,260. If you pay off early with a $200 penalty, your payoff amount could be $2,100, saving you $160. But if the penalty is $400, you would actually pay more than if you had just made the scheduled payments. Always run the numbers for your specific loan.
Another factor to consider is your credit score. Paying off a loan early can have a mixed impact. On one hand, reducing your debt load can improve your credit utilization ratio, which is a positive. On the other hand, closing an installment account early may shorten your credit history length, which can slightly lower your score. The effect is usually minor, but it is worth keeping in mind. If you are planning to apply for a major loan soon, such as a mortgage, you may want to consult a financial advisor before making early payoff decisions.
Steps to Request a Written Payoff Quote Before Sending Final Payment
One of the most common mistakes borrowers make is sending a payment they believe will pay off the loan in full, only to discover later that they still owe a small balance or a penalty. To avoid this, always request a written payoff quote from your lender before you send any final payment. A payoff quote is an official statement that tells you the exact amount needed to satisfy the loan as of a specific date. It typically includes the remaining principal, accrued interest, and any prepayment penalties or other fees. Because interest accrues daily on many loans, the payoff amount can change from day to day, so you need a quote that is valid for the date you plan to send the payment.
Here is a step-by-step process to request and use a payoff quote:
- Contact your lender. Call the customer service number on your loan statement or log into your online account. Ask for a written payoff quote. Some lenders allow you to request this online, while others require a phone call.
- Provide the necessary information. You may need to verify your identity with your account number, Social Security number, or other details.
- Specify the payoff date. Tell the lender the date you intend to send the payment. The quote will be calculated based on that date.
- Review the quote carefully. Check that it includes all fees and that the daily interest rate is correct. If you see a prepayment penalty, confirm that it matches your contract.
- Send the payment as instructed. Use the payment method specified by the lender (wire transfer, certified check, etc.) and send it in time to arrive by the payoff date. Keep a copy of the quote and your payment confirmation.
- Confirm the loan is closed. After the payment clears, contact the lender to confirm that your loan balance is zero and that no further payments are due. Ask for a written confirmation of payoff.
Following these steps protects you from overpaying or underpaying. If you send too little, the loan remains open and interest continues to accrue. If you send too much, you may have to wait for a refund, which can take weeks. A written payoff quote eliminates the guesswork. Additionally, if you are working with a lender through a connection service like 4Payday, which connects consumers with short-term loan options, the lender should provide clear instructions on how to obtain a payoff quote. Always deal directly with the lender that holds your loan, as the connection service does not manage repayments.
If you encounter resistance from a lender when requesting a payoff quote, remind them that you have a right to this information. Most states require lenders to provide a payoff statement within a reasonable timeframe, often within 5 to 10 business days. If the lender fails to comply, you can file a complaint with your state's attorney general or the Consumer Financial Protection Bureau.
Negotiating a Prepayment Penalty Waiver
If your loan contract includes a prepayment penalty, you might be able to negotiate it away, especially if you are a good customer with a history of on-time payments. Lenders are often willing to waive fees to retain customer goodwill or to encourage early repayment, which reduces their risk. Before you send your payoff, call the lender and explain that you want to pay off the loan early but the penalty is a barrier. Ask if they can waive or reduce the fee. Be polite and persistent. If the first representative says no, ask to speak with a supervisor. Sometimes a simple request is all it takes.
You can also use competition as leverage. If you have received a better offer from another lender, mention it. Some lenders will match or beat a competitor's terms to keep your business. However, be careful not to refinance a short term loan with another short term loan unless you have a clear plan to repay it quickly. Refinancing can lead to a cycle of debt if not managed responsibly. Short term loans are designed for temporary financial gaps, not as long-term solutions, and they often carry high APRs. If you are struggling to repay, consider contacting a nonprofit credit counseling agency for guidance.
Another option is to time your payoff strategically. Some lenders only charge a prepayment penalty during the first few months of the loan. If you can wait until that window passes, you may avoid the fee entirely. Check your contract for the specific timing rules. If the penalty applies only to the first 90 days, for example, waiting until day 91 could save you hundreds of dollars. Just be sure to factor in the additional interest you will pay during that waiting period to ensure it is still worth it.
Final Thoughts on Protecting Yourself
Prepayment penalties on short term loans can be a hidden trap for borrowers who are trying to do the right thing by paying off debt early. The key to protecting yourself is education and vigilance. Always read your loan agreement thoroughly, ask questions about prepayment terms before signing, and request a written payoff quote before sending any final payment. Understand your state's laws regarding prepayment penalties, and do not hesitate to negotiate if you find an unfair fee. Remember that CashLoanFunded is not a direct lender; it connects you with third-party lenders who set their own terms. By taking these steps, you can avoid surprise fees and make informed decisions that align with your financial goals. If you are considering a short term loan, visit CashLoanFunded to explore your options and access educational resources that help you borrow responsibly.