Payday Loan vs Personal Loan for Travel Emergency
Compare payday loan vs personal loan for travel emergency and choose the right option. Call 8335013363 for guidance on fast funding.
By Asher Sanchez
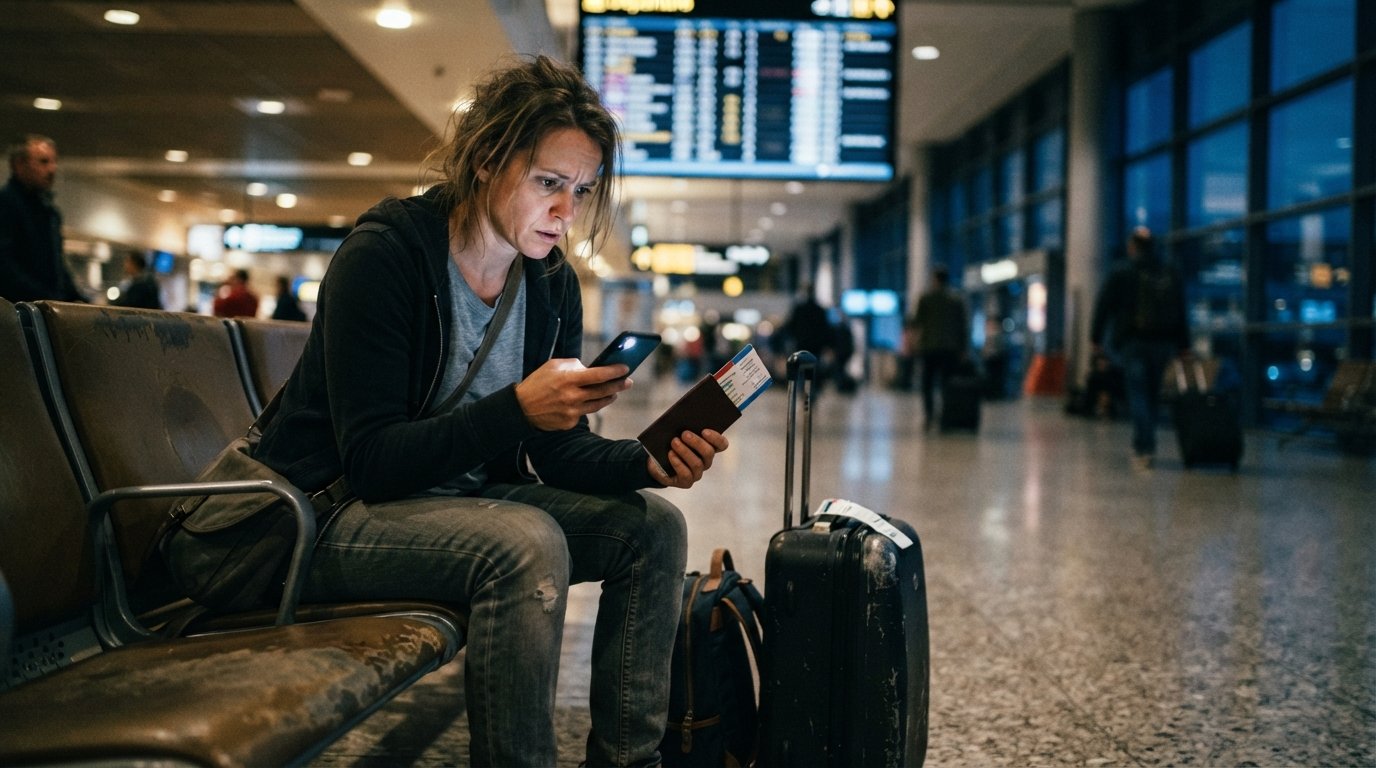
A canceled flight, a sudden medical bill abroad, or a lost wallet can turn a dream vacation into a financial nightmare. When you are stranded far from home and your emergency fund is not enough, the pressure to find fast cash is overwhelming. You might be weighing a payday loan against a personal loan, wondering which option will get you home without ruining your finances. The choice you make in that stressful moment can affect your budget for months, so understanding the real differences is critical.
Travel emergencies are unique because they often require immediate funds for expenses you cannot postpone: a rental car, a last-minute hotel stay, or a replacement passport fee. Unlike routine bills, these costs are unpredictable and urgent. That urgency pushes many people toward the first available option, which is often a payday loan. However, a personal loan might offer lower interest and a more manageable repayment timeline if you can wait a little longer for approval. This article breaks down how each loan type works, compares their costs and risks, and helps you decide which path fits your situation best.
Before you apply for any loan, it helps to understand the broader landscape of cash loans versus personal loans. If you are new to these terms, a guide on cash loan versus personal loan differences can clarify the basics. The key is to match the loan product to your timeline, your ability to repay, and the total cost you will face.
How Payday Loans Work for Travel Emergencies
A payday loan is a short-term, high-cost borrowing option designed to cover expenses until your next paycheck. These loans are typically small, often under $1,000, and are backed by your future income rather than collateral. When you take out a payday loan, you usually agree to repay the full amount plus a fee on your next payday, which is often within 30 days. Some lenders offer rollover options, but these can trap you in a cycle of debt if you cannot repay on time.
For a travel emergency, a payday loan might seem appealing because approval is fast. You can often apply online and receive funds the same day or the next business day. Lenders typically require proof of income, a bank account, and valid identification. If you are stranded and need cash immediately, this speed can feel like a lifeline. However, the convenience comes at a steep price. Payday loans carry annual percentage rates (APRs) that can exceed 400 percent in some states, turning a $500 loan into a $575 or $600 repayment within weeks.
Imagine you are on vacation and your car breaks down in a remote area. The repair shop needs $600 upfront, and you do not have that cash. A payday loan could cover it, but if you cannot repay the full amount by your next payday, you might need to roll the loan over, incurring additional fees. What started as a $600 emergency could balloon into a much larger debt. That is why payday loans are best reserved for situations where you are absolutely certain you can repay on time and the alternative is worse, such as missing a flight home.
It is also important to note that payday loans are not available in all states. Some states have strict regulations or outright bans, while others allow high fees and interest rates. If you are traveling domestically, you might not be able to access a payday loan from a local lender if you are not a resident. Online lenders may offer payday loans across state lines, but you must verify their licensing and legality in your home state.
How Personal Loans Work for Travel Emergencies
A personal loan is an installment loan that you repay in fixed monthly payments over a set term, usually one to five years. These loans can range from $1,000 to $15,000 or more, depending on the lender and your creditworthiness. Unlike payday loans, personal loans typically have much lower APRs, often ranging from 6 percent to 36 percent, although borrowers with bad credit may see higher rates. Because personal loans are unsecured, you do not need collateral, but your credit score and income play a major role in approval and pricing.
For a travel emergency, a personal loan can provide a larger sum of money with a more predictable repayment schedule. If your emergency involves a significant expense, such as a medical evacuation or a last-minute international flight, a personal loan might be the only way to cover the cost without maxing out credit cards. The application process is usually online, and funds can be deposited directly into your bank account, often within one to three business days. That is slightly slower than a payday loan, but the lower interest and longer repayment term can save you hundreds or thousands of dollars.
Consider a scenario where you are abroad and need $3,000 for emergency medical treatment. A payday loan would require you to repay the full amount plus fees within weeks, which is likely impossible if you are still traveling and not earning income. A personal loan, on the other hand, lets you spread the cost over 12 to 36 months, making the monthly payment manageable. You can focus on your recovery or your trip without the crushing pressure of a lump-sum repayment.
However, personal loans are not instant. You will need to provide documentation, undergo a credit check, and wait for approval. If your credit score is low, you might be denied or offered a high interest rate. In that case, you may need to explore other options, such as a loan from a credit union or a family member. Still, for many travelers, a personal loan is a far safer and more affordable choice than a payday loan.
Key Differences: Cost, Speed, and Repayment Terms
The most striking difference between payday loans and personal loans is cost. Payday loans are notorious for their exorbitant APRs, which can be several hundred percent. Personal loans, while not cheap, are significantly less expensive because they are regulated like traditional installment loans. Over the life of the loan, you could pay back two or three times the amount you borrowed with a payday loan, whereas a personal loan might cost you only 10 to 20 percent more than the principal.
Speed is another factor. Payday loans are designed for speed, with approval and funding often happening within hours. Personal loans take longer because lenders need to verify your information and assess your credit risk. If you need money in your hand in the next hour, a payday loan might be your only option. But if you can wait a day or two, a personal loan is almost always the better financial decision.
Repayment terms also differ dramatically. Payday loans require a single lump-sum payment on your next payday, which can be difficult if your emergency expenses have already strained your budget. Personal loans offer fixed monthly payments over a longer period, giving you breathing room to recover financially. Here is a quick comparison of the main features:
- Loan amount: Payday loans are usually $100 to $1,000; personal loans range from $1,000 to $15,000 or more.
- Repayment: Payday loans are due in full on your next payday; personal loans are repaid in monthly installments over 12 to 60 months.
- APR: Payday loans can exceed 400 percent; personal loans typically range from 6 percent to 36 percent.
- Approval speed: Payday loans can be approved within minutes; personal loans may take one to three business days.
- Credit check: Payday loans often do not require a hard credit check; personal loans almost always do.
These differences mean that the right choice depends on your specific circumstances. If you have a small, short-term gap and are confident you can repay quickly, a payday loan might work. But if you need a larger sum or cannot repay in a few weeks, a personal loan is the more responsible option.
It is also worth noting that some lenders offer alternatives that blend features of both. For example, installment loans can provide a middle ground, with larger amounts than payday loans but shorter terms than personal loans. If you are exploring options, you might consider a service like AdvanceCash, which connects borrowers with third-party lenders for various loan types. Always read the terms carefully and compare offers before committing.
When a Payday Loan Might Be Your Only Option
There are rare situations where a payday loan could be the only viable choice. If you are stranded in a foreign country and your bank card is not working, and you have no access to a personal loan or credit card, a payday loan from an online lender might be the fastest way to get funds. Similarly, if you have very bad credit and cannot qualify for a personal loan, a payday loan might be the only lender willing to work with you. However, these scenarios should be treated as last resorts, not first choices.
Even in these cases, you must be honest with yourself about your ability to repay. If you cannot repay the loan on time, you risk falling into a debt cycle that could damage your credit and lead to collection calls. Before taking a payday loan, ask yourself: Will I have the full repayment amount by my next payday? If the answer is no, you should exhaust all other options first, such as borrowing from a friend, using a credit card, or contacting a local embassy or consulate for emergency assistance.
Another consideration is that payday loans can be difficult to obtain if you are traveling abroad. Most online payday lenders require a U.S. bank account and a U.S. address, and they may not be able to verify your information if you are overseas. In contrast, a personal loan from a U.S. bank or credit union might be easier to secure remotely, especially if you have an existing relationship with the institution.
When a Personal Loan Is the Better Choice
For most travel emergencies, a personal loan is the smarter financial move. If your emergency costs more than you can repay in a few weeks, or if you need more than $1,000, a personal loan gives you the flexibility to repay over time without incurring exorbitant fees. Even if you have less-than-perfect credit, you may still qualify for a personal loan, though you might pay a higher interest rate. That is still far better than the triple-digit APRs of payday loans.
Personal loans also help you avoid the stress of a looming lump-sum payment. When you are dealing with a travel crisis, the last thing you need is the pressure of finding hundreds or thousands of dollars in a matter of days. A fixed monthly payment allows you to budget and plan, so you can focus on resolving your emergency rather than worrying about debt collectors.
Additionally, personal loans can help you build or rebuild your credit if you make on-time payments. Payday loans, on the other hand, are rarely reported to credit bureaus unless you default, so they do not help your credit score. If you are trying to improve your financial health, a personal loan is a more constructive tool.
Of course, a personal loan is not without risks. If you lose your job or face another emergency, you could struggle to make payments. Late payments can hurt your credit score and lead to fees. That is why it is essential to borrow only what you can afford to repay and to have a plan for making those monthly payments.
How to Apply for a Personal Loan for a Travel Emergency
If you decide that a personal loan is the right choice, you will need to move quickly but carefully. Start by checking your credit score and gathering your financial documents, such as pay stubs, bank statements, and identification. Then, research lenders that offer fast funding and competitive rates. Many online lenders specialize in emergency loans and can approve you within a day.
The application process typically involves the following steps:
- Fill out an online application with your personal and financial information.
- Wait for the lender to review your application and run a credit check.
- Receive a loan offer with terms, including the interest rate and monthly payment.
- Review the offer carefully and compare it with other lenders if possible.
- Sign the loan agreement electronically and receive funds in your bank account, often within one to three business days.
Before you sign, make sure you understand the total cost of the loan, including any origination fees, prepayment penalties, or late fees. Ask yourself if the monthly payment fits comfortably into your budget. If not, consider borrowing less or looking for a longer term to lower the monthly payment, though this may increase the total interest you pay.
It is also wise to explore multiple offers. Different lenders have different criteria, and you might be surprised by how much rates vary. Even a small difference in APR can save you a significant amount over the life of the loan. Do not accept the first offer without comparing at least two or three options.
Alternatives to Consider Before Borrowing
Before you commit to any loan, consider whether there are other ways to cover your travel emergency. Credit cards can be a quick source of funds, especially if you have available credit and can pay the balance off within a month or two. However, if you carry a balance, the interest rate can be high, though still lower than a payday loan. A credit card cash advance is another option, but it often comes with a fee and a higher interest rate than regular purchases.
You might also ask friends or family for a short-term loan. While it can be uncomfortable, it is often the cheapest option if they are willing to help. Just be sure to agree on a repayment plan and stick to it to preserve the relationship. Another option is to contact your bank or credit union about a small personal line of credit. If you have a good relationship with them, they might offer a lower rate than an online lender.
Finally, if you are traveling abroad, check whether your travel insurance or credit card provides emergency assistance. Some policies cover trip interruptions, medical emergencies, or lost luggage, and they might reimburse you for expenses. Contact your provider immediately to see what is covered and how to file a claim. This could reduce the amount you need to borrow.
Understanding the Risks and Responsibilities
Regardless of which loan you choose, borrowing money comes with responsibilities. You must repay the loan according to the terms, or you risk damaging your credit score, incurring late fees, and facing collection actions. Payday loans are particularly risky because they can lead to a cycle of debt if you cannot repay on time. Personal loans are safer but still require discipline to make monthly payments.
Before you borrow, create a repayment plan. Calculate how much you can afford to pay each month and make sure it aligns with your loan terms. If you are using a personal loan, consider setting up automatic payments so you never miss a due date. If you are using a payday loan, mark your calendar and ensure the funds are in your account before the lender withdraws the payment.
It is also important to understand that loan offers and terms are determined by third-party lenders, not by connecting services. If you use a platform to find a loan, read the lender's terms carefully and contact them directly if you have questions. Do not rely solely on the connecting service for details about APR, fees, or repayment schedules.
Lastly, remember that short-term loans are not a long-term financial solution. They are designed to cover temporary gaps, not to fund ongoing expenses. If you find yourself relying on loans to make ends meet, it may be time to seek financial counseling or create a budget to address the root cause of your financial stress.
Travel emergencies are stressful, but they do not have to derail your finances. By understanding the differences between payday loans and personal loans, you can make an informed decision that protects your wallet and your peace of mind. Whether you choose a payday loan for its speed or a personal loan for its lower cost, borrow responsibly and plan for repayment from the start.