Loan Payment Due With No Funds: Your 2026 Action Plan
A loan payment is due and you have no funds. Call the lender before the due date, ask for an extension or partial payment, and avoid fees and credit damage.
By Asher Sanchez
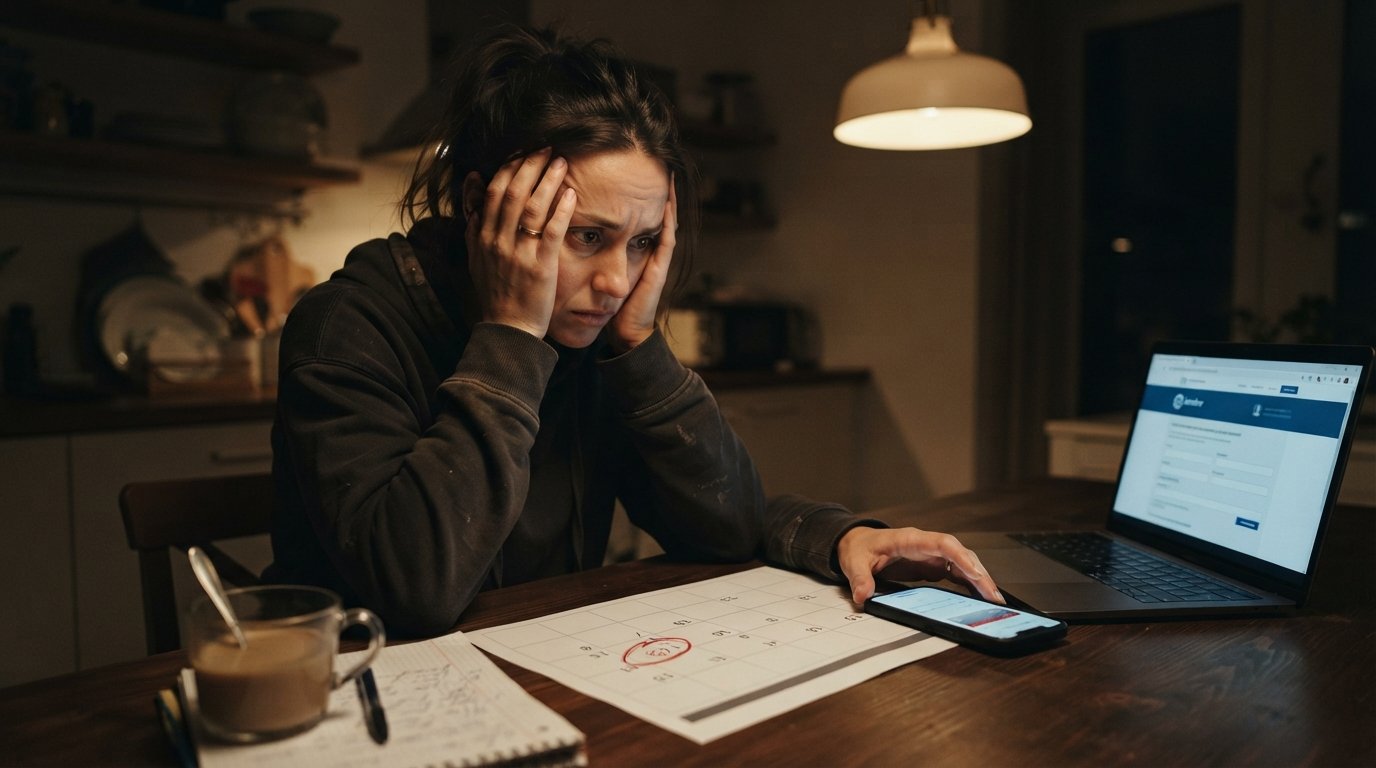
The due date is circled on your calendar, the balance in your checking account is far too low, and the clock is ticking. That sinking feeling when a loan payment is due and you have no funds is one of the most stressful moments in personal finance, but panic is not a strategy. What you do in the next 24 to 48 hours matters far more than how you feel right now. Lenders have procedures for this exact situation, and most would rather work with you than watch a payment fail. This guide walks you through a practical, step-by-step action plan so you can protect your credit, minimize fees, and buy yourself the breathing room you need.
Act Before the Due Date, Not After
The single most important move you can make is to contact your lender before the payment date passes. A phone call or secure message sent two days before the due date signals responsibility and gives you options. Waiting until after a missed payment limits what the lender can offer and often triggers automatic late fees that no one can reverse. When you reach out, be direct: state that you are experiencing a temporary cash shortfall, that you want to honor the obligation, and that you need to discuss alternatives. Ask for a supervisor or the hardship department if the first representative cannot help.
Keep a record of every conversation. Note the date, time, the name of the representative, and what was promised. If you communicate in writing, save copies of the messages. This documentation protects you if a fee appears later or if there is a dispute about what was agreed. Lenders operate on notes in their systems, and your own record is your best defense.
Before you call, gather a few facts so the conversation is productive: your loan account number, the exact amount due, the due date, and a realistic picture of when you will have funds. If you can pay part of the amount now, say so. Lenders respond better to a specific plan than to a vague promise. For borrowers exploring repayment structures in specific states, resources like a guide to loan repayment options in California can clarify what flexibility typically looks like.
Options Lenders May Offer When You Cannot Pay
Contrary to popular belief, many lenders have formal programs designed for short-term hardship. The options available depend on the lender, the loan type, and your payment history, but the most common accommodations fall into a few categories. Asking specifically for each one by name shows you understand the process and increases the chance of a workable solution.
- Due date extension or deferment: The lender moves your payment date forward, often by one to two weeks, sometimes without a fee for a first-time request.
- Partial payment arrangement: You pay a portion now and the remainder on a defined date, with the understanding that the account stays current.
- Revised payment schedule: For installment loans, the lender may re-amortize the loan, lowering the monthly amount and extending the term.
- Hardship or forbearance program: A temporary reduction or pause in payments for borrowers facing documented financial difficulty.
Each option has trade-offs. An extension may add interest. A revised schedule may increase the total cost of the loan. A hardship program may require documentation such as pay stubs or a hardship letter. Ask the representative to explain the total cost of each option before you agree, and get the terms in writing. Never accept a verbal promise alone, because verbal agreements are difficult to enforce if the account later shows a late mark.
If your lender is a short-term or payday-style provider, flexibility may be narrower than with a bank or credit union. Still, many online lenders offer at least one extension per year, and some will accept partial payments. If you are comparing where to turn for a small, fast loan while you stabilize, a digital connection service such as LendersCashLoan can present offers from multiple third-party lenders through a single request, which lets you compare terms instead of accepting the first option you see.
Why Letting a Payment Fail Is a Costly Mistake
Some borrowers assume that if the money is not there, the payment simply will not happen and that is the end of it. In reality, a failed payment sets off a chain of consequences that can compound quickly. The moment an automatic debit bounces, the lender may assess a returned payment fee, and your bank may charge a nonsufficient funds fee on top of it. Those two charges alone can add $60 or more to a problem that was already difficult.
The credit damage is often worse than the fees. A payment reported 30 or more days late can appear on your credit reports and linger for up to seven years. Payment history is the largest factor in credit scoring models, so a single late mark can drop a good score by dozens of points and make future borrowing more expensive. If the account is eventually sent to collections, the damage deepens and can affect rental applications, insurance rates, and even some job prospects.
There is also a practical trap: once a payment fails, the lender may retry the debit, sometimes multiple times, generating a new fee with each attempt. If you know the funds will not be there, canceling the automatic debit and calling the lender is far better than letting the system retry. A proactive call costs nothing; a failed payment costs money and credit.
Short-Term Ways to Cover Part of the Payment
Sometimes the gap is smaller than it looks. Before you borrow more money to solve a money problem, work through the resources already available to you. The goal is to cover as much of the payment as possible without creating a second crisis, because stacking a new high-cost loan on top of an existing payment often makes the next month harder.
- Tap flexible spending you already own: Check for unused gift cards, cash-back balances, or funds sitting in a flexible spending account that can be reimbursed.
- Ask for a billing shift, not a loan: Request a due date change on a utility or subscription to free up cash this week, or ask a service provider about a payment plan.
- Sell something quickly: A marketplace listing for an unused phone, tool, or piece of furniture can often net $50 to $200 within a day or two.
- Request a partial payroll advance: Some employers offer earned wage access, letting you draw pay you have already earned before the scheduled payday.
- Ask your bank about a small overdraft line: If you have a relationship with your bank, a short-term overdraft buffer may be cheaper than a payday loan, though fees still apply.
Each of these options buys time without adding a new long-term obligation. If none of them closes the gap, and you are considering a short-term loan to bridge the difference, be honest about the math. A new loan payment will come due next month, and if your budget could not handle the current payment, adding another one requires a plan for how both will be paid. Short-term loans carry high annual percentage rates and are designed for temporary gaps, not ongoing shortfalls.
When to Bring In a Nonprofit Credit Counselor
If this is not the first time you have faced a due date with no funds, the problem may be structural rather than temporary. A nonprofit credit counseling agency can review your entire budget, negotiate with creditors on your behalf, and help you build a debt management plan. These services are often low-cost or free, and they are offered by organizations that do not profit from selling you new loans. Look for agencies affiliated with the National Foundation for Credit Counseling or a similar accredited body.
Credit counselors are especially useful when you have multiple obligations competing for the same paycheck. They can help you prioritize payments, identify expenses to cut, and communicate with lenders in a way that carries more weight than a single borrower call. If your hardship is likely to last more than a month or two, a counseling session is worth scheduling before the situation escalates into collections.
Hardship programs are the other formal path. Many lenders, including credit card issuers and personal loan providers, maintain programs that reduce interest, waive fees, or lower payments for a defined period. These programs usually require proof of hardship, such as a layoff notice or medical bill, and they may temporarily note the arrangement on your account. The trade-off is worth understanding: a hardship program can protect your credit from a late mark, but it may close the account or restrict new charges. Ask exactly how the program will be reported before you enroll.
Build a Buffer So This Does Not Repeat
Once the immediate crisis passes, the real work begins. The goal is to create a small cushion so that the next unexpected expense does not become a missed payment. Start with a target of $500, which covers most car repairs and urgent bills, and fund it automatically with even $20 per paycheck. A dedicated savings account separate from your checking account makes the money harder to spend and easier to protect.
Review your payment dates as well. If multiple bills land in the same week as your paycheck, ask lenders to move due dates to the days after you are paid. Many lenders allow this once per year at no cost. Aligning due dates with cash flow is one of the simplest and most effective changes a borrower can make.
Finally, treat this experience as information. A payment due with no funds is a signal that the budget has no margin, and the fix is rarely a bigger loan. It is usually a smaller fixed cost, a more realistic payment schedule, or a slightly larger emergency fund. Lenders, counselors, and budgeting tools all exist to help you get there, but the first step is always the same: pick up the phone before the due date passes.