Installment Loan for Home Repairs Without Equity
An installment loan for home repairs without equity lets you fix critical damage with fixed payments, even with bad credit. Compare offers and costs here.
By Asher Sanchez
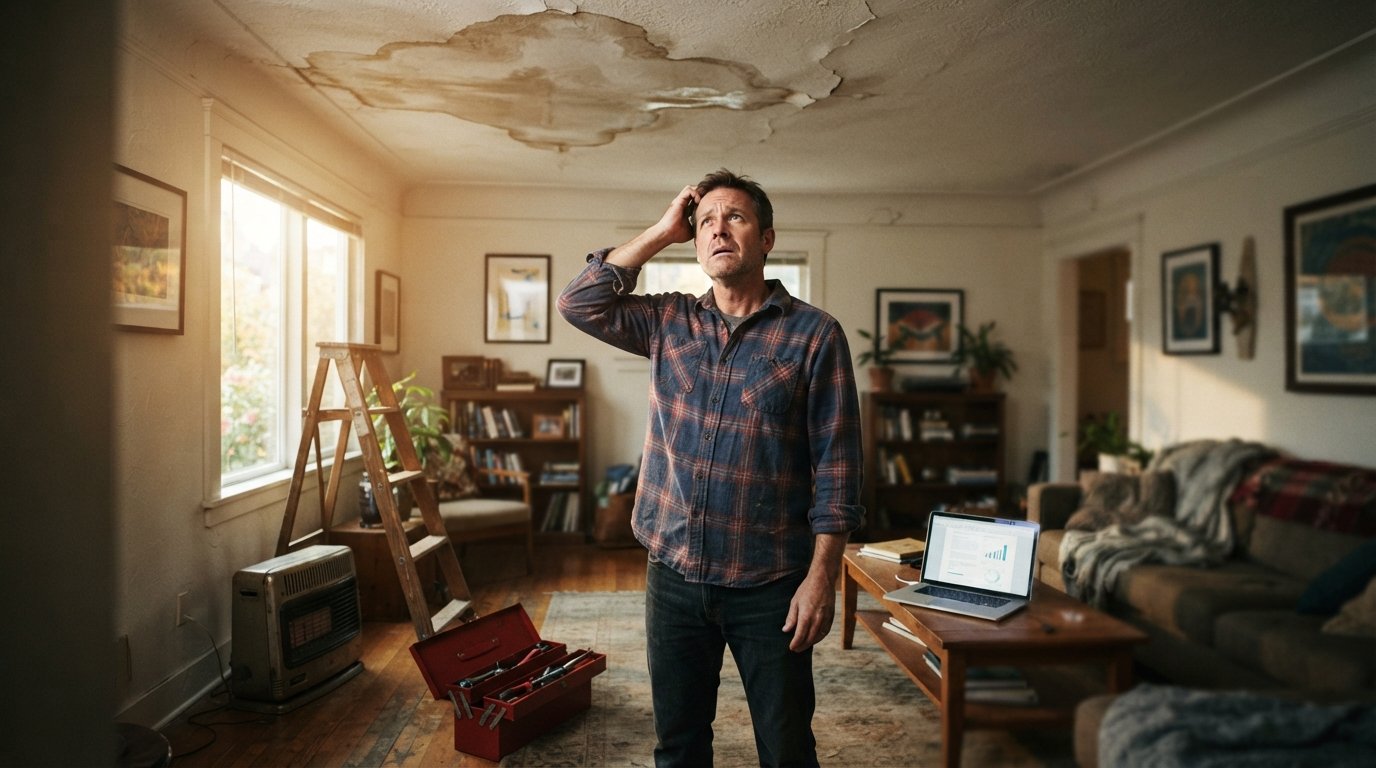
Your furnace dies in January. Your roof starts leaking after a spring storm. The repair quote lands in your inbox, and it is more than your entire emergency savings. You own your home, but most of your wealth is trapped in it, and you have not built enough equity to qualify for a traditional home equity loan or HELOC. This is a frustrating and surprisingly common position, especially for newer homeowners, people who bought with low down payments, or anyone whose property value dipped after purchase. The good news is that you still have options. An installment loan for home repairs without equity lets you borrow a fixed sum, repay it in predictable monthly installments, and keep your home out of the collateral equation entirely.
This guide walks through how these loans work, when they make sense, what they cost, and how to choose the right one for your situation. We will also cover how to apply, what lenders look for, and how to avoid the traps that turn a smart repair decision into a long-term financial headache.
What an Installment Loan for Home Repairs Without Equity Actually Is
An installment loan is a lump sum of money you borrow and repay over a set schedule, usually in equal monthly payments across a fixed term. Unlike a credit card, which has a revolving balance and variable minimum payments, an installment loan has a defined end date and a predictable payment. When the loan is unsecured, meaning it is not tied to your home or any other asset, your equity position is irrelevant to approval. The lender evaluates you, not your property.
That distinction matters for homeowners who need repairs but cannot access home equity products. A HELOC or home equity loan requires a certain loan-to-value ratio, typically 80 to 85 percent, meaning you need substantial equity before a lender will consider you. If you bought recently or your market has softened, you may be locked out of those options even with excellent credit. An unsecured installment loan bypasses that requirement entirely.
These loans are also different from payday loans. Payday loans are short-term, usually due in full on your next payday, and carry extremely high fees that translate to triple-digit APRs. Installment loans spread repayment across months or years, which lowers the monthly burden and gives you time to recover from the repair expense. That structure is a better fit for home repairs, which are rarely cheap and often come with related costs like permits, inspections, or temporary housing.
CashLoanFunded connects borrowers with third-party lenders who offer installment loans and other short-term funding options. The platform is not a direct lender, but it lets you submit one request and review offers from multiple lenders, which saves time when you are dealing with a pressing repair. You can learn more about how the process works by visiting AdvanceCash, a similar connecting service for short-term loans.
When an Unsecured Installment Loan Makes Sense for Home Repairs
Not every repair should be financed with an installment loan. If you have access to a low-interest credit card with a long 0 percent introductory period, or if you can cover the cost with savings, those routes are usually cheaper. But there are situations where an unsecured installment loan is the most practical choice available.
Consider these scenarios:
- Your home needs a critical repair (roof, HVAC, plumbing, electrical) that cannot wait, and you do not have the cash on hand.
- You have limited equity because you bought recently, made a low down payment, or your home value has not appreciated enough to support a HELOC.
- Your credit is fair or poor, and you need a lender who evaluates income and stability rather than just a score.
- You want a fixed monthly payment and a clear payoff date instead of revolving debt that lingers for years.
- You need funds quickly, often within a few business days, because the damage is worsening or a contractor is ready to start.
In each case, the key is that the repair is necessary, the cost is manageable within your budget, and you have a plan to repay the loan without straining your finances. If the repair is cosmetic or optional, financing it with a high-APR loan is rarely wise. But when a failed water heater or a leaking roof threatens your home's value and your family's safety, an installment loan can be a responsible bridge.
It is also worth checking whether you qualify for any special programs. Some states and municipalities offer low-interest repair loans or grants for homeowners, especially for energy efficiency upgrades, accessibility modifications, or emergency repairs. These programs often have income limits and waiting lists, but they are worth exploring before you commit to a private loan.
How Lenders Evaluate You Without Home Equity
When a loan is unsecured, the lender cannot seize your home if you default. That increases their risk, which is why unsecured installment loans typically carry higher interest rates than secured home equity products. To offset that risk, lenders focus heavily on your ability and willingness to repay. Understanding what they look for can help you strengthen your application.
Most lenders consider the following factors:
- Income: You need a stable, verifiable source of income. This can be employment, self-employment, retirement, disability, or other regular payments. Lenders often want to see that your income comfortably covers the new loan payment plus your existing obligations.
- Credit history: Your credit score matters, but it is not the only factor. Lenders also look at your payment history, the number of recent inquiries, and whether you have any recent bankruptcies or collections. Some lenders specialize in working with borrowers who have bad credit, as long as the income criteria are met.
- Debt-to-income ratio: This compares your total monthly debt payments to your gross monthly income. A lower ratio signals that you have room in your budget for another payment. Many lenders look for a DTI below 40 to 50 percent, though requirements vary.
- Bank account and stability: A valid checking account in good standing is usually required so the lender can deposit funds and set up automatic payments. Lenders may also look at how long you have lived at your address and worked in your field.
- Collateral (or lack thereof): Since the loan is unsecured, there is no collateral to evaluate. That puts more weight on the factors above.
If your credit is damaged, do not assume you are disqualified. Many lenders in the short-term loan space consider applicants with bad credit, repossession, or bankruptcy history, provided they can demonstrate a stable income and a bank account without negative transaction history. The trade-off is that you may pay a higher interest rate or receive a smaller loan amount. If you want to explore options for imperfect credit, this guide on emergency home repair loans for bad credit walks through where to turn and what to expect.
Typical Costs, Terms, and Repayment Structures
Installment loans for home repairs without equity come in a range of sizes and terms. Because they are unsecured, loan amounts are often smaller than what you might get with a HELOC. Many lenders offer amounts from $1,000 to $5,000, though some go higher depending on your income and credit profile. Terms typically range from a few months to several years. Shorter terms mean higher monthly payments but less interest paid overall. Longer terms lower the monthly payment but increase the total cost.
Interest rates vary widely based on your creditworthiness, income, loan amount, term, and the lender's own criteria. Unsecured installment loans can carry APRs from the low double digits to well over 100 percent in some cases, especially for borrowers with poor credit. That is a wide range, and it is why comparing offers carefully is essential. A loan that looks affordable on a monthly basis can become very expensive over time if the APR is high and the term is long.
Here is what to examine in any offer:
- APR: This is the annualized cost of the loan, including interest and most fees. It is the single best number for comparing offers.
- Monthly payment: Make sure the payment fits comfortably in your budget, not just for the first month but for the entire term.
- Term length: A longer term lowers the payment but increases the total interest. Choose the shortest term you can afford.
- Fees: Look for origination fees, prepayment penalties, late fees, and any other charges. Some lenders charge a fee just to process the loan.
- Prepayment policy: You want the ability to pay off the loan early without penalty, so you can save on interest if your finances improve.
Always read the loan agreement carefully before signing. If anything is unclear, ask the lender to explain it. A reputable lender will welcome your questions and provide clear answers. If a lender pressures you to sign quickly or refuses to put terms in writing, that is a red flag.
How to Apply and What to Prepare
Applying for an installment loan through a connecting service like CashLoanFunded is designed to be simple and fast. The online request form typically takes less than five minutes to complete. You provide basic personal and financial information, submit the request, and then review offers from participating lenders. If you accept an offer, you e-sign the terms, and funds may be deposited as soon as the next business day.
To speed up the process, gather the following before you start:
- Personal identification: You must be at least 18 years old and have a valid government-issued ID, such as a driver's license or passport.
- Proof of income: Pay stubs, bank statements, tax returns, or other documentation showing a stable source of income.
- Bank account information: A checking account in your name, in good standing, so the lender can deposit funds and set up repayment.
- Contact details: Your address, phone number, and email address.
- Social Security number: Required for identity verification and a credit check.
Once you submit your request, you may receive multiple offers. Compare them side by side, focusing on APR, monthly payment, term, and fees. Do not accept the first offer just because it is fast. A few minutes of comparison can save you hundreds or thousands of dollars over the life of the loan.
Remember that submitting a request may involve a credit check, which can slightly impact your credit score. However, many connecting services use a soft credit pull for initial prequalification, which does not affect your score. Check the service's policy before you submit.
Pros and Cons of Using an Installment Loan for Home Repairs
Like any financial tool, an unsecured installment loan has advantages and drawbacks. Understanding both helps you decide whether it is the right fit for your situation.
Pros:
- No home equity required, so you can qualify even if you have little or no equity.
- Fixed monthly payments and a set payoff date make budgeting easier.
- Faster funding than many secured loan options, often within one to two business days.
- Available to borrowers with bad credit, as long as they meet income and banking criteria.
- Your home is not used as collateral, so you are not risking it if you default (though default still has serious financial consequences).
Cons:
- Higher interest rates than secured home equity loans or HELOCs.
- Smaller loan amounts, which may not cover major repairs like a full roof replacement.
- Fees can add up, especially if you miss payments or pay late.
- Applying may involve a credit check that temporarily lowers your score.
- Some lenders in the short-term space have aggressive collection practices, so choose carefully.
The key is to borrow only what you need, choose the shortest term you can afford, and repay on time. If you can do that, an installment loan can be a useful tool for handling a necessary repair without draining your savings or risking your home.
Alternatives to Consider Before You Borrow
An unsecured installment loan is not the only option for homeowners without equity. Depending on your situation, one of these alternatives might be cheaper or more suitable.
Contractor financing: Many HVAC, roofing, and remodeling companies offer financing through third-party lenders. These programs sometimes have promotional rates or longer terms. Ask your contractor if they have a financing partner.
Store credit cards: Home improvement stores like Home Depot and Lowe's offer credit cards with promotional financing on certain purchases. If you qualify, you may get 0 percent interest for a set period, which can be a great deal if you pay it off before the promotional period ends.
Personal loans from banks or credit unions: If you have good credit, a personal loan from a traditional financial institution may offer a lower APR than a short-term lender. Credit unions in particular often have competitive rates for members.
Government or nonprofit programs: Some states, counties, and cities offer low-interest repair loans or grants for homeowners. These programs may have income limits and waiting lists, but they are worth investigating. The U.S. Department of Housing and Urban Development (HUD) and local housing agencies are good starting points.
Family and friends: Borrowing from loved ones can be interest-free, but it can also strain relationships. If you go this route, put the agreement in writing and stick to a repayment plan.
Each of these options has trade-offs. The best choice depends on your credit, your timeline, the size of the repair, and how much you can afford to pay each month.
How to Avoid Predatory Loans and Protect Yourself
The short-term lending space includes many reputable lenders, but it also attracts bad actors. Protecting yourself starts with education and vigilance. Here are some warning signs to watch for:
- Pressure to act immediately: Legitimate lenders give you time to review terms and ask questions.
- No written terms: If a lender will not provide a clear loan agreement, walk away.
- Upfront fees: It is illegal for lenders to charge fees before you receive a loan in many cases. Be wary of anyone who asks for payment before funding.
- Unclear APR or hidden fees: The lender should disclose the APR and all fees clearly before you sign.
- No physical address or contact information: Reputable lenders have a verifiable presence and responsive customer service.
Before you borrow, check the lender's reputation with the Better Business Bureau and your state's attorney general or financial regulator. Read reviews, but be aware that some reviews may be fake. Trust your instincts: if something feels off, it probably is.
Also, understand your rights. The federal Truth in Lending Act requires lenders to disclose key terms, including the APR, finance charge, amount financed, and total of payments. If a lender does not provide these disclosures, that is a violation.
Making the Decision: Is an Installment Loan Right for You?
An installment loan for home repairs without equity can be a lifeline when you need to fix a critical problem and do not have the cash or home equity to cover it. It offers predictability, speed, and access for borrowers with imperfect credit. But it also comes with higher costs than secured options, and it should not be used for discretionary projects or as a long-term financial solution.
Before you apply, ask yourself these questions:
- Is the repair necessary to protect my home's safety, value, or habitability?
- Can I comfortably afford the monthly payment for the entire term?
- Have I explored all cheaper alternatives, including contractor financing, store credit, and government programs?
- Do I understand the APR, fees, and total cost of the loan?
- Do I have a plan to repay the loan on time and avoid late fees?
If you can answer yes to these questions, an unsecured installment loan may be a reasonable choice. If not, consider waiting, saving, or pursuing a different option. The goal is to fix your home without breaking your budget or jeopardizing your financial stability.
When you are ready to explore offers, a connecting service like CashLoanFunded can help you compare options from multiple lenders with a single request. The process is free, there is no obligation to accept any offer, and you can review terms before committing. Just remember that short-term loans carry high APRs and are intended for temporary financial gaps, not as a long-term solution. Borrow responsibly, and your home, and your wallet, will thank you.