How to Identify and Report Deceptive Loan Marketing
Spot guaranteed approval claims, hidden fees, and pressure tactics, then file a report that regulators can act on and protect your wallet.
By Thomas Young
You see an ad promising a $5,000 loan with guaranteed approval, no credit check, and zero fees, all funded in minutes. For anyone facing an urgent car repair or medical bill, that offer can feel like a lifeline. But deceptive loan marketing is built on exactly that pressure: it targets people who need money fast and counts on them not reading the fine print. The result can be a costly cycle of fees, a stolen identity, or a loan that costs far more than advertised. Knowing how to identify and report deceptive loan marketing protects your wallet and helps shut down the operations that prey on borrowers.
This guide breaks down the warning signs, the phrases that should make you pause, and the exact steps to document and report a misleading loan offer. The more consumers who report bad actors, the harder it becomes for them to keep operating.
Why Deceptive Loan Marketing Is So Common
Short-term lending is a high-demand, high-pressure market. When people need cash quickly, they tend to make fast decisions, and scammers know it. Some deceptive offers come from outright fraudsters who collect your personal information and disappear. Others come from legitimate-looking lenders or lead generators that use misleading claims to get you to submit an application, only to reveal the real costs later.
The stakes are high. A misleading payday or installment loan offer can bury a borrower in fees, trigger repeated bank charges, or damage credit if payments are impossible to meet. Because loan offers and terms are regulated at the state and federal level, deceptive marketing can also violate consumer protection laws. That is why reporting matters: regulators track patterns, and enough complaints can trigger investigations or enforcement actions.
It also helps to understand the difference between a lender and a connection service. Platforms like 4Payday connect borrowers with third-party lenders rather than issuing loans directly, which means the advertised terms come from the lender, not the matching site. Legitimate matching services are transparent about this distinction. Deceptive marketers blur it on purpose.
Red Flags: How to Identify Deceptive Loan Marketing
Deceptive loan ads tend to reuse the same playbook. Once you know the patterns, they become easy to spot. The following red flags cover the most common tactics, from impossible promises to pressure tactics designed to stop you from thinking clearly.
- Guaranteed approval claims. No legitimate lender can guarantee approval before reviewing your income, debts, and credit history. Phrases like "everyone approved" or "bad credit? no problem, guaranteed" are classic bait.
- No credit check promises. Most regulated lenders run at least a soft or hard credit inquiry. An ad that promises funds with zero credit check is either misleading or pointing you toward an unlicensed operation.
- Upfront fees. Legitimate lenders deduct fees from the loan proceeds or disclose them in the agreement. Anyone asking you to pay a fee before receiving funds, especially via gift card, wire transfer, or crypto, is running a scam.
- Pressure to act now. Countdown timers, "last chance" language, and repeated calls urging you to sign immediately are designed to prevent comparison shopping.
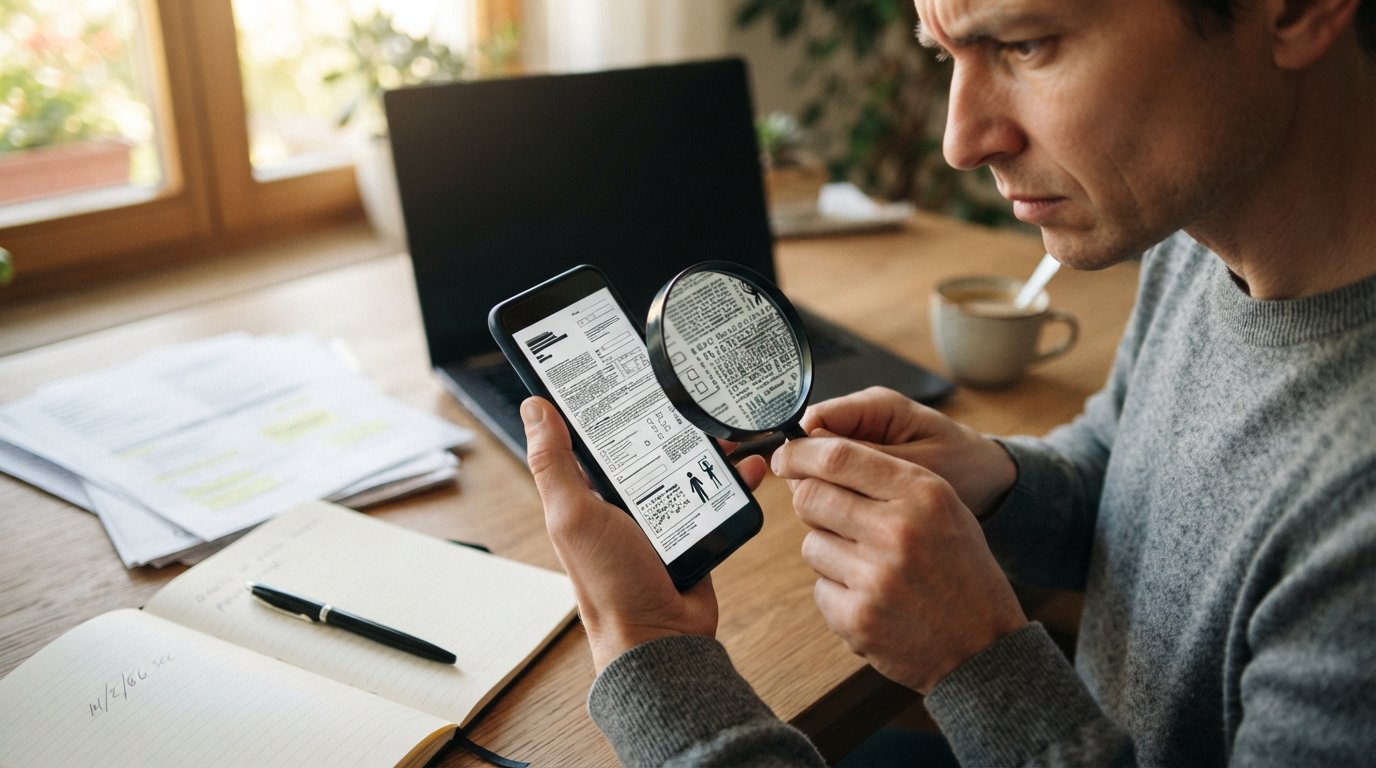
- Vague or missing APR disclosures. A real offer states the annual percentage rate, finance charges, and repayment schedule. If you cannot find the APR, assume the cost is high and hidden.
None of these red flags alone proves fraud, but two or more together should stop you cold. A legitimate lender will answer questions about rates and terms without hesitation, and it will never rush you into signing.
Watch These Deceptive Phrases Closely
Certain phrases appear so often in deceptive loan marketing that they deserve special scrutiny. "Guaranteed approval" tops the list because it is almost always false. "No fees" is another one: some lenders advertise no application fees but charge origination, late, or prepayment penalties that dwarf any upfront savings. Before you accept any offer, ask for a full fee schedule in writing. If the answer is vague, walk away.
"Pre-approved" is another phrase that gets stretched. A pre-approval is not a final approval, and it does not lock in your rate. Deceptive marketers use the term to make you feel selected, then change the terms after you apply. Similarly, "instant funding" often means "instant application," not instant cash in your account. Treat every superlative as a question to verify, not a fact to trust.
How to Keep Records of a Misleading Offer
If an offer feels deceptive, your first instinct might be to delete it and move on. Resist that urge. A paper trail is what turns a vague complaint into an actionable report, and regulators need specifics to investigate. Start documenting the moment something feels off.
- Save the ad itself. Take screenshots of the website, social media post, text message, or email, including the URL, date, and time.
- Record the sender. Note the company name, phone number, email address, and any representative you speak with.
- Keep the offer documents. Save the application, disclosure statements, and any terms you were shown, even if you did not sign.
- Log your communications. Write down what was promised, when, and by whom, along with any fees or rates quoted.
- Preserve payment requests. If anyone asks for an upfront fee, keep the request and note the payment method they demanded.
Organize everything in one folder, digital or physical, and label it clearly. If you later file a complaint, you will be asked for dates, amounts, and names, and having them ready speeds up the process. It also protects you if a lender disputes your account of what happened.
Where to Report Deceptive Loan Marketing
Several agencies accept consumer complaints about loan marketing, and filing with more than one increases the chance your report reaches the right investigator. The best starting point depends on what happened, but you can file with multiple agencies without penalty.
- The Consumer Financial Protection Bureau (CFPB). The CFPB accepts complaints about lenders, loan servicers, and financial products, and it forwards them to the company for a response.
- The Federal Trade Commission (FTC). Report fraud, deceptive advertising, and scam offers at ReportFraud.ftc.gov. The FTC uses these reports to build cases against bad actors.
- Your state attorney general. State AGs enforce consumer protection laws and often act quickly on local lending complaints.
- Your state financial regulator. Most states license lenders and accept complaints about unlicensed or abusive lending activity.
- The FBI Internet Crime Complaint Center (IC3). Use this for online scams, phishing loan offers, and identity theft tied to fake lenders.
When you file, include your documentation: the ad, the company name, the dates, and a clear description of what was promised versus what was delivered. Keep a copy of each complaint and note the reference number. Follow up if you do not hear back within a few weeks, and respond promptly if an agency asks for more information.
Protect Yourself Before You Apply
Reporting is important, but prevention saves you the most trouble. Before you submit an application to any lender, verify that the company is licensed in your state, read the full loan agreement including the APR and fee schedule, and confirm how and when repayment will be collected. A legitimate lender will never ask for payment before funding, and it will not threaten you for asking questions.
It also pays to compare offers rather than accepting the first one you see. Even a few minutes of comparison can reveal that one offer carries a far lower APR or more flexible repayment terms. If you are unsure what a specific charge means, ask before signing. Understanding costs like the loan origination fee for short term loans can help you spot when an advertised "no fee" claim is hiding real costs.
Finally, remember that urgency is a tool. Real emergencies push people to skip due diligence, and deceptive marketers depend on that. Slowing down, reading the disclosures, and keeping records are simple habits that neutralize most of their tactics.
Deceptive loan marketing thrives on confusion and speed, but it cannot survive scrutiny. Learn the warning signs, document anything that feels misleading, and report it to the agencies that enforce consumer protection. Every complaint you file makes it harder for bad actors to target the next borrower who is simply trying to get through a tough month.