How to E-Sign a Loan Agreement Online Safely
E-signing a loan agreement online safely requires verifying the lender, reading the fine print, and knowing when to pause. Protect your finances before you click sign.
By Ethan Harper
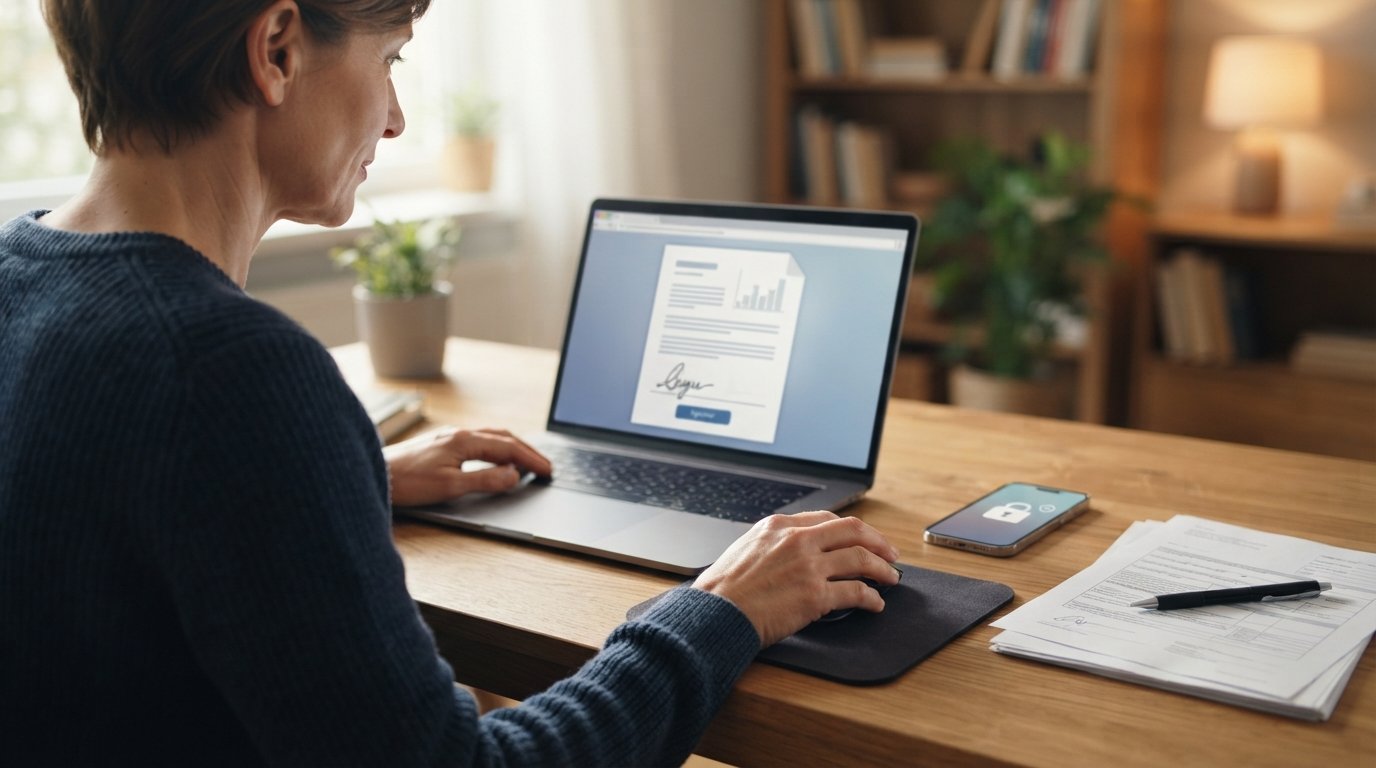
You have been approved for a loan, and the lender has sent a digital agreement for your signature. The convenience is undeniable, but the moment you click that sign button, you are entering a legally binding contract. Understanding how to e-sign a loan agreement online safely is not just about the click itself; it is about verifying the lender, reading the fine print, and knowing exactly what you are committing to before the funds hit your account.
What Is an E-Signature and Why Is It Legally Binding?
An e-signature is an electronic process that allows you to sign documents digitally. It is not just a typed name or a scanned image of your handwriting; it is a secure, auditable transaction that captures your intent to sign and the integrity of the document. Under the federal Electronic Signatures in Global and National Commerce (ESIGN) Act, e-signatures carry the same legal weight as pen-and-paper signatures for most transactions, including loan agreements. This means that once you e-sign, you are bound by the terms just as if you had signed in ink.
Lenders use e-signature platforms that employ encryption, audit trails, and authentication methods to ensure that the person signing is indeed you. These systems record the time, date, IP address, and sometimes even a biometric signature or a one-time passcode. For you as a borrower, this is a protective measure: it creates a verifiable record that you agreed to the terms. However, it also means you cannot later claim you did not sign or did not understand the agreement if you clicked without reading.
When you receive a loan agreement to e-sign, it is typically delivered through a secure portal or a link sent to your email. The document itself is usually a PDF or a web-based form that includes all the disclosures required by law, such as the Annual Percentage Rate (APR), finance charge, amount financed, and repayment schedule. Your e-signature will be applied to the document, and you will often receive a signed copy for your records. The entire process can take just minutes, but the implications last for the life of the loan.
Before You Sign: What to Read in the Loan Agreement
The excitement of approval can make it tempting to skim the agreement and click sign immediately. Resist that urge. The loan agreement contains critical details that determine how much you will pay and what happens if you miss a payment. Before you e-sign, take the time to read and understand the following key elements.
APR and Finance Charge
The APR is the cost of credit expressed as a yearly rate. It includes not just the interest rate but also any fees charged by the lender. For short-term loans, the APR can be very high, sometimes exceeding 400 percent when annualized. The finance charge is the total dollar amount you will pay to borrow the money. Both numbers should be clearly disclosed in the agreement. If they are not, or if they seem too good to be true, ask the lender for clarification. For a deeper dive into spotting red flags in loan contracts, see our guide on how to read the fine print on a payday loan agreement.Due Dates and Repayment Schedule
The agreement will specify when payments are due and how they will be applied. Pay attention to whether payments are due weekly, biweekly, or monthly, and whether there are any grace periods. For payday loans, the entire balance is often due on your next payday, while installment loans have multiple scheduled payments. Missing a due date can trigger late fees and additional interest, so mark these dates on your calendar immediately.Renewal and Rollover Terms
Some short-term loans include renewal or rollover options, which allow you to extend the loan by paying a fee. While this might seem helpful, it can trap you in a cycle of debt if you are not careful. The agreement should clearly state whether renewal is available, what the fees are, and how many times you can renew. If you do not see this information, ask the lender before signing. Remember that CashLoanFunded is not a direct lender and does not set these terms; they are determined by the third-party lender you are matched with.Prepayment Penalties and Other Fees
Check if there are any penalties for paying off the loan early. Some lenders charge a prepayment penalty, which means you pay extra for saving them interest. Also, look for origination fees, processing fees, or any other charges that might be deducted from your loan amount. These fees reduce the actual amount you receive and increase the effective cost of borrowing.If any part of the agreement is unclear, do not sign. Contact the lender and ask for an explanation. A legitimate lender will be happy to clarify the terms. Signing without understanding is one of the most common mistakes borrowers make, and it can lead to financial strain.
How to Verify the Lender and the Document Link Are Legitimate
Phishing scams and fraudulent lenders exist, and they often target individuals who are in urgent need of cash. Before you click on any link to e-sign a loan agreement, take steps to verify that the lender is legitimate and that the document is genuine.
Check the Lender's Credentials
Start by confirming that the lender is licensed to operate in your state. You can usually do this by checking your state's financial regulatory website. Legitimate lenders will provide their license number or a link to verify their status. If you are using a matching service like ExpressCash, ensure that the service is transparent about connecting you with third-party lenders and does not charge you fees for the matching service. CashLoanFunded, for example, is a free loan matching service that connects borrowers with a network of independent lenders, and it does not charge users any fees for its service.Examine the Email and Link
Phishing emails often mimic legitimate lenders but use slightly altered email addresses or URLs. Hover over the link in the email to see the actual URL before clicking. It should match the lender's official domain, not a generic or suspicious one. Also, check for spelling errors, generic greetings, and urgent language that pressures you to act immediately. A legitimate lender will not rush you into signing without giving you time to review the documents.Look for Secure Connection and Authentication
When you click the link, ensure that the website uses HTTPS (look for the padlock icon in your browser). The e-signature platform should require you to authenticate your identity, often through a one-time passcode sent to your phone or email, or by answering security questions. This protects both you and the lender. If the process seems too simple or does not require any verification, it could be a red flag.Verify the Document's Integrity
Legitimate e-signature platforms will provide an audit trail that shows when the document was created, sent, viewed, and signed. They may also include a tamper-evident seal. If you have any doubts, you can contact the lender directly using a phone number you independently verified (not one provided in the suspicious email) to confirm that they sent the document.Taking these verification steps might add a few minutes to the process, but they are essential for protecting your personal information and financial well-being. Identity theft and loan fraud can have long-lasting consequences, so it is worth being cautious.
What Happens After You E-Sign?
Once you click the sign button and complete any required authentication, the agreement is executed. The lender will typically provide you with a signed copy of the agreement for your records, either immediately on the screen or via email. You should save this copy in a secure place. This document outlines your rights and obligations, and you may need to refer to it later.
The lender will then process the loan disbursement. According to the terms you agreed to, the funds will be deposited into your bank account, often as soon as the next business day. The repayment schedule you reviewed will go into effect, and your first payment will be due on the date specified. Some lenders may automatically withdraw payments from your account, so ensure you have sufficient funds on the due dates to avoid overdraft fees and late charges.
It is also important to understand that e-signing does not mean the loan is finalized until the funds are disbursed. In some cases, the lender may still conduct final verification steps, such as confirming your bank account details or income. If any issues arise, the lender will contact you. However, once the money is in your account, the loan is active, and you are responsible for repaying it according to the terms.
Keep an eye on your bank account and email for confirmation of the deposit and any additional instructions. If you do not receive the funds within the expected timeframe, contact the lender directly. Do not rely on the matching service for loan servicing, as they are not the lender and cannot answer questions about disbursement or repayment.
When to Pause and Ask Questions Instead of Signing Under Pressure
Urgency is a common tactic used by unscrupulous lenders to get you to sign without reading. If you feel pressured to sign immediately, that is a signal to slow down. A legitimate lender will give you time to review the agreement and ask questions. Here are some situations where you should pause and seek clarification.
If the lender refuses to provide written copies of the agreement before you sign, or if they insist on a wire transfer or prepaid card for fees, these are major red flags. Legitimate lenders do not ask for upfront fees to secure a loan. Similarly, if the APR or fees are not clearly disclosed, or if the terms seem inconsistent with what you were told earlier, do not sign. Ask for a full explanation in writing.
Another time to pause is if you do not understand the repayment terms. For example, if you are unsure whether the loan is installment or revolving, or if you do not know how much your monthly payment will be, ask the lender to clarify. You can also seek advice from a financial counselor or a trusted friend before signing. Remember, once you e-sign, you are legally bound. It is far better to delay signing than to commit to a loan you cannot afford.
Additionally, if you are feeling emotional or stressed about your financial situation, take a step back. High-pressure sales tactics are designed to exploit urgency. Give yourself at least a few hours to review the documents calmly. If the lender is legitimate, they will respect your need to review the terms. If they pressure you, consider walking away.
Best Practices for Safe E-Signing
To ensure a safe and secure e-signing experience, follow these best practices:
- Use a secure device and network: Avoid signing loan agreements on public Wi-Fi or shared computers. Use a private, password-protected device and a trusted internet connection.
- Keep your credentials private: Never share your e-signature login details or one-time passcodes with anyone. The lender will not ask for your password via email or phone.
- Save copies of all documents: Download and store the signed agreement, disclosures, and any correspondence with the lender. This documentation is crucial if a dispute arises.
- Monitor your accounts: After signing, regularly check your bank account and credit report for any unauthorized activity. Report discrepancies immediately.
- Know your rights: Familiarize yourself with consumer protection laws, such as the Truth in Lending Act, which requires lenders to disclose key terms. If you believe a lender has violated your rights, contact your state attorney general or the Consumer Financial Protection Bureau.
By following these practices, you can reduce the risk of fraud and ensure that your e-signing experience is smooth and secure.
Final Thoughts
E-signing a loan agreement online can be a convenient and efficient way to access funds when you need them. However, safety should always come first. By understanding the legal binding nature of e-signatures, reading the agreement carefully, verifying the lender's legitimacy, and knowing when to pause and ask questions, you can protect yourself from fraud and make informed borrowing decisions. Remember that CashLoanFunded is here to connect you with reputable lenders, but the final responsibility for reviewing and signing the agreement rests with you. Take your time, stay informed, and sign with confidence.