Financial Habits to Avoid Needing Short Term Loans
Build financial habits to avoid needing short term loans and gain a cash buffer for emergencies. Call 8335013363 for guidance today.
By James Morgan
Unexpected expenses have a way of arriving at the worst possible time. A transmission fails, a medical bill appears, or a paycheck lands later than expected. When that happens, many people turn to short term loans as a quick fix. These products can be useful in a genuine emergency, but relying on them repeatedly often signals that everyday money habits need attention. The good news is that building a few deliberate routines can reduce how often you need to borrow, and when you do need help, you can approach it from a stronger position. This guide walks through practical financial habits to avoid needing short term loans, with steps you can start using this week.
Why People Rely on Short Term Loans
Short term loans, including payday loans, cash advances, and small installment loans, are designed for temporary financial gaps. They are typically small, unsecured, and repaid quickly. For someone facing an urgent car repair or an unexpected medical copay, they can provide fast access to cash when traditional banks may take days to respond. The appeal is understandable: speed, convenience, and fewer barriers to approval.
The problem is that these loans often carry high annual percentage rates and fees. According to consumer protection guidance, they work best when repaid on time and in full, and they become costly when rolled over or extended. When a borrower takes a new loan to cover an old one, the cycle can deepen quickly. That is why prevention matters more than reaction. The habits below focus on reducing the likelihood that you ever reach that point.
Build an Emergency Fund Before You Need It
An emergency fund is the single most effective buffer against short term borrowing. Even a small cushion can cover a tire replacement or a prescription without forcing you into a high-cost loan. The goal is not to save thousands overnight. It is to start, automate, and let consistency do the work. Many financial educators suggest aiming for at least $500 as a starter fund, then growing toward one month of essential expenses.
To make saving realistic, treat it like a bill. Set an automatic transfer from checking to savings on payday, even if the amount is $10 or $20. If your income varies, save a percentage of each deposit instead of a fixed amount. Keep the fund in a separate account so it is slightly less convenient to spend. Name the account something specific, like "car repair" or "medical buffer," so you remember why it exists.
When you do use the fund, replenish it as soon as possible. The habit is not just saving; it is rebuilding after a withdrawal. Over time, this rhythm reduces the panic that leads people to search for fast cash.
Create a Realistic Monthly Budget
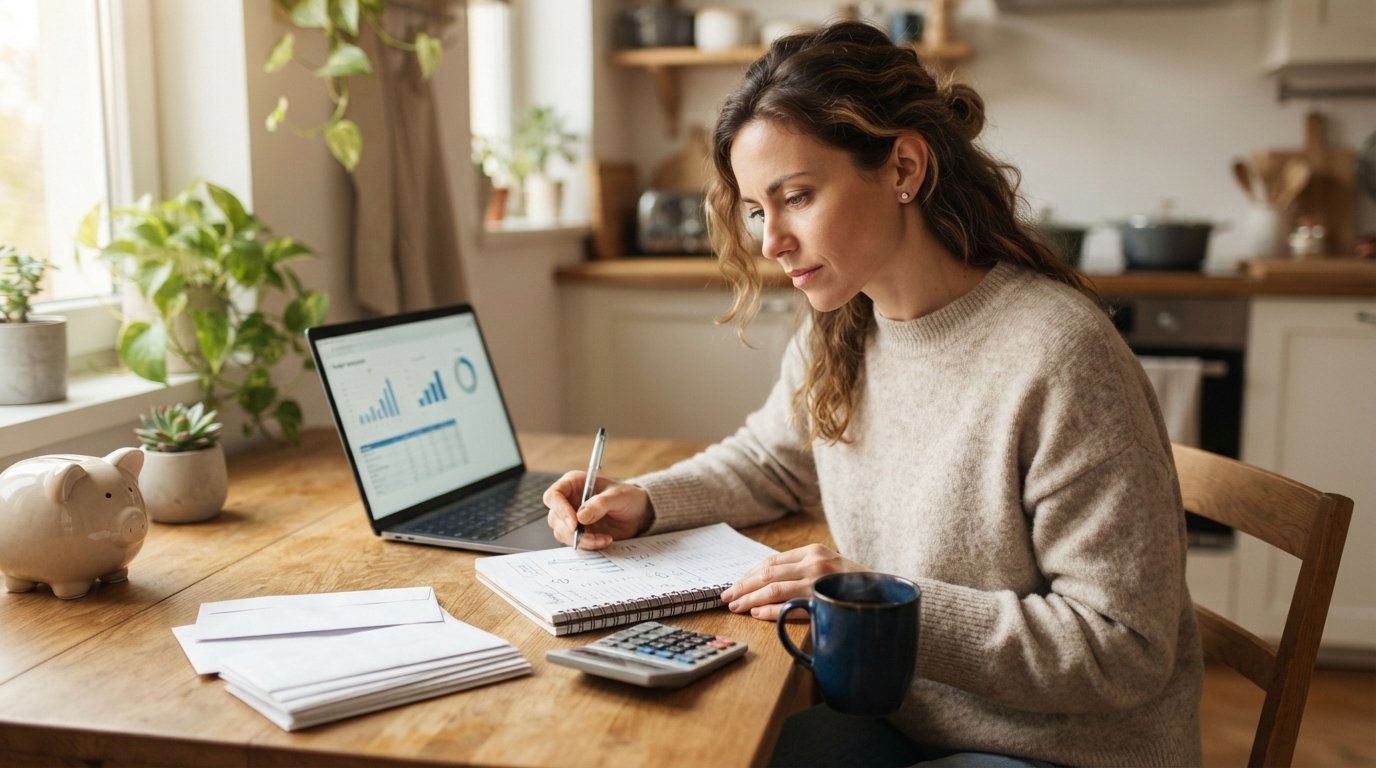
A budget is not a restriction. It is a plan that tells your money where to go before it disappears. Many people avoid budgeting because they think it requires complex spreadsheets, but a simple zero-based or 50/30/20 approach can work well. The key is to track what actually comes in and what actually goes out for at least one month.
Start by listing fixed costs such as rent, utilities, insurance, and loan payments. Then list variable costs like groceries, gas, and dining. Compare the total to your income. If expenses exceed income, you have found the gap that short term loans often fill. Closing that gap, even partially, reduces your reliance on borrowing. Look for subscriptions you forgot about, fees you can avoid, and recurring charges that no longer serve you.
Once you have a baseline, assign every dollar a job. Include a small amount for fun so the plan is sustainable. Review the budget weekly, not just monthly, so you can adjust before a shortfall becomes a crisis. A budget you actually use is worth more than a perfect one you ignore.
Pay Yourself First and Automate Savings
One of the most reliable financial habits is to save before you spend. This is often called paying yourself first. When savings happen automatically, you remove the need for willpower. Set up transfers for the day after payday, when the money is most likely to be available. If your employer offers direct deposit, you may be able to split a portion directly into savings.
Automation also helps with irregular income. If you are self-employed or work gig jobs, transfer a percentage of each payment as soon as it arrives. Even 5 percent adds up. The goal is to make saving the default, not an afterthought. When an emergency appears, you will have options that do not involve a high-cost loan.
Consider creating multiple savings buckets: one for emergencies, one for planned expenses like car maintenance, and one for goals. This structure makes it easier to see progress and reduces the temptation to raid your emergency fund for non-emergencies.
Reduce and Manage Debt Strategically
High-interest debt is a major reason people seek short term loans. When a large portion of your income goes to minimum payments, there is little left for surprises. Reducing debt frees up cash flow and lowers stress. Start by listing every debt with its balance, interest rate, and minimum payment.
Two common strategies are the snowball method (paying the smallest balance first for momentum) and the avalanche method (paying the highest interest rate first to save money). Both work. Choose the one you will stick with. If you can consolidate high-interest debt into a lower-rate personal loan, that may reduce monthly pressure, but read the terms carefully. Consolidation only helps if you stop adding new debt.
Also, contact creditors before you miss a payment. Many lenders offer hardship programs, modified due dates, or temporary reductions. A short conversation can prevent late fees and credit damage. Avoiding the problem is what leads to expensive borrowing later.
Improve Your Credit Score Over Time
A stronger credit score gives you more options when you need money. It can mean lower rates on personal loans, better terms on credit cards, and sometimes approval for amounts that cover a real emergency. Improving your score is not mysterious. It comes down to paying on time, keeping balances low relative to limits, and letting accounts age.
Start by checking your credit reports for errors. Dispute anything inaccurate. Then set up automatic payments for at least the minimum on every account. If you carry balances, focus on paying them down. Avoid opening several new accounts in a short period, since that can lower your average account age and trigger multiple inquiries.
If you have bad credit, you can still build positive history. Secured cards, credit-builder loans, and on-time utility payments reported to bureaus can all help. Over months, these habits expand your access to mainstream credit, which reduces reliance on short term loans.
Plan for Irregular and Seasonal Expenses
Many financial emergencies are predictable if you look ahead. Car registration, insurance premiums, holidays, back-to-school costs, and annual subscriptions arrive on a schedule. When you know they are coming, you can save a little each month instead of scrambling when the bill lands.
Create a sinking fund for each irregular expense. Divide the annual cost by 12 and save that amount monthly. For example, a $600 car insurance premium becomes $50 per month. This turns a shock into a planned expense. The same approach works for home maintenance, medical deductibles, and travel.
Seasonal income changes also deserve a plan. If your hours drop in winter or your gig work slows in summer, build a buffer during peak months. Knowing your lean seasons helps you avoid borrowing during them.
Use Credit and Loans Responsibly When Needed
Avoiding short term loans does not mean never borrowing. It means borrowing deliberately, with a repayment plan in place before you sign. If you face a genuine emergency and your savings are not enough, compare options carefully. Personal loans, installment loans, and credit union products may offer lower rates than payday loans. If you are exploring fast funding options, a service like Funded Cash Loans Near Me can connect you with lenders, but always review the terms and total cost.
Before accepting any offer, calculate the total repayment amount, not just the monthly payment. Check the APR, fees, and due dates. Make sure the payment fits your budget without squeezing essentials. If it does not, consider a smaller amount or a different product. Never borrow more than you need.
For those who want to explore short term options through a connecting service, platforms like AdvanceCash allow you to submit a single request and review offers from third-party lenders. Remember that these services are not direct lenders, and loan terms are set by the lenders. Use them as a last resort, not a habit.
Track Spending and Review Your Progress
You cannot improve what you do not measure. Set aside 15 minutes each week to review your spending, savings, and upcoming bills. Look for patterns: Are you eating out more than planned? Did a subscription renew unexpectedly? Are you on track for your emergency fund goal? Small adjustments each week prevent big problems each month.
Use a simple system that works for you, whether it is a notebook, a spreadsheet, or an app. The tool matters less than the routine. Over time, you will see where money leaks and where you can redirect it. This awareness alone reduces the likelihood of needing a short term loan.
Celebrate progress. Paying off a small debt, hitting a savings milestone, or going three months without borrowing are wins worth noting. Positive reinforcement makes the habits stick.
Build a Support Network and Seek Guidance
Financial stress is easier to manage when you are not alone. Talk with a trusted friend, family member, or financial counselor. Nonprofit credit counseling services can help you create a budget, negotiate with creditors, and explore debt management plans. Many offer free or low-cost sessions.
If you are a homeowner, you may have additional options such as home equity lines of credit, though these carry their own risks. For renters and others, community programs, faith-based organizations, and local assistance funds can sometimes help with one-time emergencies. Knowing where to turn before a crisis hits expands your choices.
Finally, be honest with yourself about your finances. Ignoring a problem does not make it disappear. Facing it early gives you more time to adjust and less reason to rely on high-cost borrowing.
Building financial habits to avoid needing short term loans is not about perfection. It is about progress. Start with one habit, such as automating a small savings transfer or tracking your spending for a week. Add another next month. Over time, these routines create a buffer that turns emergencies into inconveniences rather than crises. You will still face surprises, but you will face them with more options and less stress.