Emergency Home Repair Funding Options for Homeowners
Explore emergency home repair funding options for homeowners, from fast loans to grants. Call 8335013363 for guidance on your next steps.
By Owen Mitchell
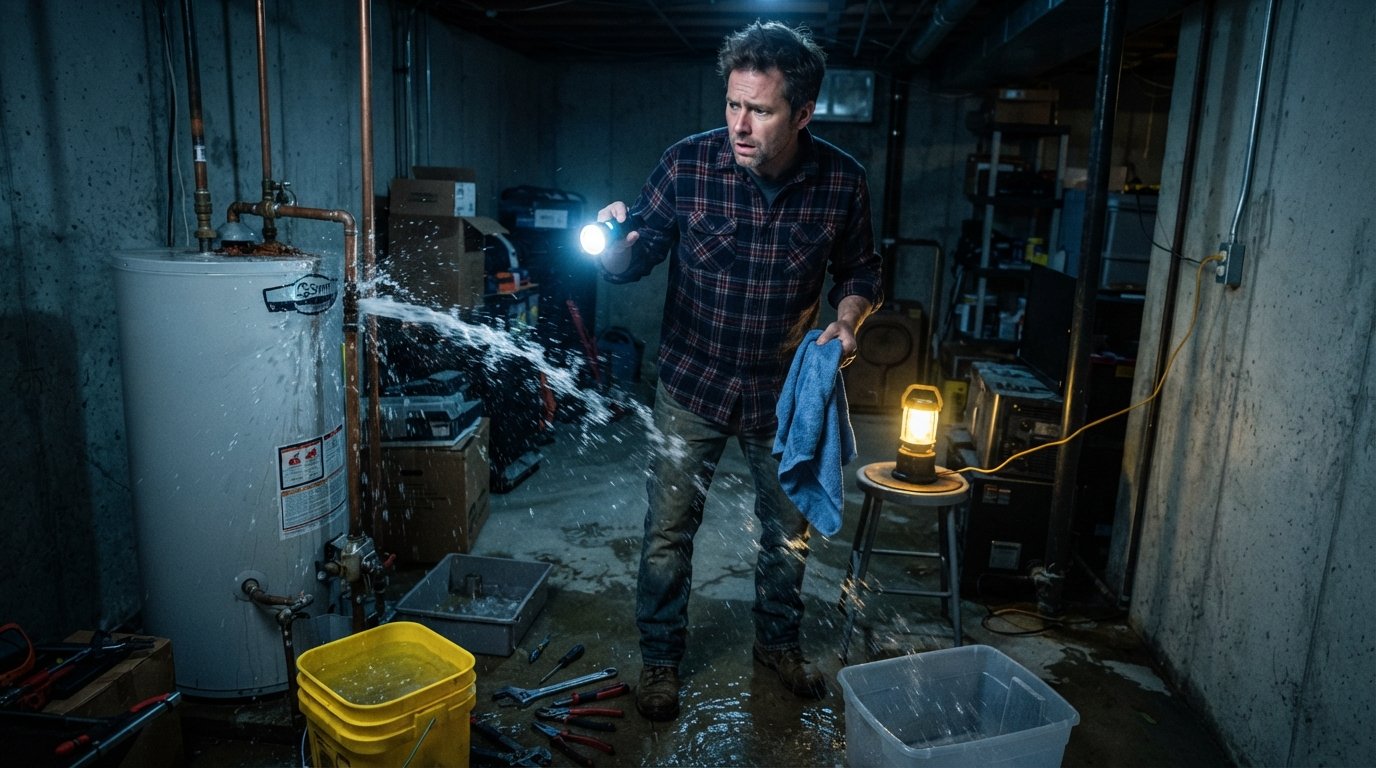
A burst pipe at 2 a.m. A furnace that quits during the first cold snap. A roof leak that turns a quiet afternoon into a scramble with buckets and towels. When a home emergency hits, the repair bill rarely waits for payday, and most homeowners do not have thousands of dollars sitting idle for the occasion. The good news is that you have more paths to fast cash than you might think, and knowing them ahead of time can mean the difference between a quick fix and a long, stressful recovery.
This guide walks through the realistic emergency home repair funding options for homeowners in 2026, from specialized loans to insurance claims to assistance programs. Along the way, you will see how each option works, who tends to qualify, and which trade-offs matter most when your goal is speed.
Start With the True Cost and Urgency of the Repair
Before you apply for anything, put a number on the problem. A failed water heater and a cracked foundation are both emergencies, but they demand very different budgets. Call two or three licensed contractors for quick estimates, and ask each one what happens if the repair waits a week. Some issues, like active water intrusion or a gas leak, get worse by the hour and justify premium pricing. Others, like a cosmetic fence repair, can wait for a cheaper weekday appointment.
Write down three figures: the lowest credible estimate, the highest, and a contingency amount of 10 to 20 percent for surprises found once work begins. That range becomes your funding target. Having a target keeps you from borrowing more than you need, which matters because most emergency repair financing carries interest.
You should also separate needs from wants during this stage. If the HVAC system is dead in July, a full replacement might be necessary, but a temporary window unit could buy you two weeks to compare financing offers calmly. That breathing room often saves hundreds of dollars in rushed decisions.
Emergency Home Repair Funding Options for Homeowners at a Glance
Most homeowners end up choosing from a handful of categories, and each one fits a different mix of speed, cost, and credit requirements. The list below covers the main routes, ordered roughly from fastest to slowest.
- Short-term and personal loans: unsecured cash that can arrive as soon as the next business day, best for smaller repairs under $5,000.
- Home equity lines and loans: lower rates secured by your house, but approval and closing can take weeks.
- Credit cards and store financing: instant purchasing power, though promotional rates expire.
- Insurance claims and FEMA aid: essential when damage is sudden, accidental, or disaster-related.
- Government and nonprofit assistance: grants and low-cost loans for qualifying incomes, veterans, and seniors.
Notice that the fastest options are usually unsecured, meaning the lender does not take a claim on your home. That speed comes with higher APRs, so these products work best for genuine emergencies rather than planned renovations. Slower options cost less over time but require paperwork, equity, and patience you may not have when water is pouring through a ceiling.
Short-Term Loans and Personal Loans for Urgent Repairs
When the repair cannot wait and you lack a large emergency fund, an unsecured loan is often the most practical answer. These loans do not require collateral, so your home stays out of the deal, and the application process is typically fully online. If you are weighing this route, our guide on loan funding options for homeowners explains how different products compare for urgent expenses.
Personal loans usually range from $1,000 to $15,000 with fixed monthly payments over one to several years. Installment loans sit at the smaller end, often under $5,000, and are repaid in a set number of scheduled payments. Payday-style cash advances are the smallest and shortest, usually under $1,000 with terms of about 30 days, and they are designed strictly to bridge a temporary gap, not to fund a major project.
Because these products often carry high APRs, treat them as a bridge rather than a destination. Borrow only what the repair requires, confirm the repayment schedule before signing, and make the first payment a priority in your budget. Platforms like AdvanceCash connect U.S. consumers with third-party lenders for short-term options such as payday loans, personal loans, and installment loans, which can be useful when you need to compare offers quickly after a household emergency.
What You Typically Need to Qualify
Eligibility for unsecured emergency loans is broader than many homeowners expect. Lenders generally look for a steady income, a valid bank account, and basic identification rather than a perfect credit score. A history of bankruptcy, repossession, or past due accounts does not automatically disqualify you if your income is stable and verifiable. That said, weaker credit usually means a higher APR, so it pays to compare at least a few offers side by side.
Gather your documents before you apply: government ID, proof of income such as recent pay stubs, your bank routing and account numbers, and your Social Security number. A complete application submitted once moves faster than a partial one that triggers follow-up calls. Also confirm whether the lender performs a hard credit check, since multiple applications in a short window can ding your score.
Home Equity Options When You Have Time and Equity
If your repair is urgent but not an active disaster, and you have built equity, a home equity line of credit (HELOC) or home equity loan can be the cheapest money available. Because the loan is secured by your house, rates are typically far lower than unsecured products. A home equity loan delivers a lump sum with fixed payments, while a HELOC works like a credit line you can draw from as invoices arrive.
The catch is timing. Appraisals, underwriting, and closing can take two to six weeks, which is too slow for a flooded basement but fine for a failing septic system you have been watching for months. There is also real risk: if you fall behind, the lender can foreclose, so never borrow more against your home than you can comfortably repay.
Homeowners with strong credit sometimes qualify for a cash-out refinance instead, which replaces your existing mortgage with a larger one and hands you the difference. This can be efficient if current rates are favorable, but closing costs are significant, so run the numbers before committing.
Credit Cards, Store Financing, and Contractor Payment Plans
For repairs in the hundreds or low thousands, a credit card can be the simplest tool you already own. Many cards offer 0 percent introductory APR periods, which effectively creates an interest-free loan if you pay the balance before the promo ends. The risk is that standard rates afterward are steep, and a large balance can quietly grow if you only make minimum payments.
Contractors and home improvement retailers frequently offer their own financing, sometimes with deferred interest for 6 to 24 months. Read the fine print carefully: deferred interest deals can retroactively charge interest from day one if you miss the payoff deadline by even a small amount. Ask the contractor whether they offer a payment plan directly, since some established companies will spread a large job across several months at no extra cost.
A practical hybrid works well here: use a 0 percent card for the portion you can repay within the promo window, and reserve a short-term loan for the remainder. This keeps total interest low while still getting the work started immediately.
Insurance Claims and Disaster Assistance
If the damage came from a covered event, such as a fire, storm, burst pipe, or falling tree, your homeowners insurance is often the first place to look. Report the claim promptly, document everything with photos and receipts, and keep a written log of every conversation with your adjuster. Many policies also cover temporary lodging or mitigation costs, such as boarding up a window or renting a dehumidifier, so ask specifically about additional living expenses.
Insurers may issue an advance payment for urgent mitigation work before the final claim settles. This can cover emergency tarping, water extraction, or temporary repairs that prevent further damage. Keep every receipt, because unreimbursed mitigation spending is usually recoverable.
When a federally declared disaster is involved, FEMA and the Small Business Administration (SBA) may offer grants or low-interest disaster loans to homeowners, including renters and landlords in some programs. These are not quick payouts, but they can fund repairs that insurance does not fully cover. Apply even if you are unsure about eligibility, since the process itself is free.
Grants and Assistance Programs for Qualifying Homeowners
Not every funding source needs to be repaid. Several programs exist specifically to help homeowners who cannot absorb a sudden repair bill. The trick is knowing where to look and applying early, because funds are limited.
- Weatherization Assistance Program: federally funded upgrades for energy-related repairs, prioritized for low-income households.
- USDA Section 504 loans and grants: for very low-income rural homeowners, covering repairs that improve safety or remove health hazards.
- VA and state veteran programs: some offer grants or low-cost loans for accessibility and emergency repairs.
- Local housing and community development agencies: many cities run emergency repair programs with income limits and waiting lists.
- Nonprofit and faith-based groups: organizations like Rebuilding Together and Habitat for Humanity affiliates sometimes assist with critical repairs.
Start with your city or county housing department and your state housing finance agency, then ask local nonprofits for referrals. Be prepared to document income, ownership, and the nature of the emergency. Approval can take weeks, so pair these applications with a faster funding source if the repair cannot wait.
A Step-by-Step Plan for Funding an Emergency Repair
When the pressure is on, a simple sequence keeps you from making an expensive mistake. Work through these steps in order, adjusting for how quickly the damage is spreading.
- Stabilize and document: stop the damage if you safely can, then photograph everything for insurance and estimates.
- Get two or three estimates: confirm the scope, timeline, and total cost, including contingency.
- Check insurance and assistance first: file claims and applications early, since they take the longest.
- Compare fast funding offers: review short-term and personal loan terms side by side, watching APRs and repayment schedules.
- Borrow only the gap: subtract insurance payouts, savings, and grants from the total before you sign anything.
After funding is in place, set a repayment calendar immediately. Mark every due date, automate payments where possible, and contact the lender before you miss a payment rather than after. Late payments can trigger fees, higher rates, and credit damage, all of which make the next emergency harder to handle.
Finally, treat the repair as a lesson for next time. Once the dust settles, build a small home emergency fund, even $500 to start, and review your insurance coverage for gaps. Homeowners who plan ahead need emergency financing far less often, and when they do, they borrow less and repay faster.
Emergencies will happen, but they do not have to derail your finances. With a clear picture of your options, from quick unsecured loans to insurance and assistance programs, you can fund the repair, protect your home, and move forward with confidence.