Emergency Cash for Homeowners Facing Property Tax Deadlines
Facing a property tax deadline? Compare county payment plans, home equity options, personal loans, and assistance programs to secure emergency cash for homeowners.
By Lucas Ramirez
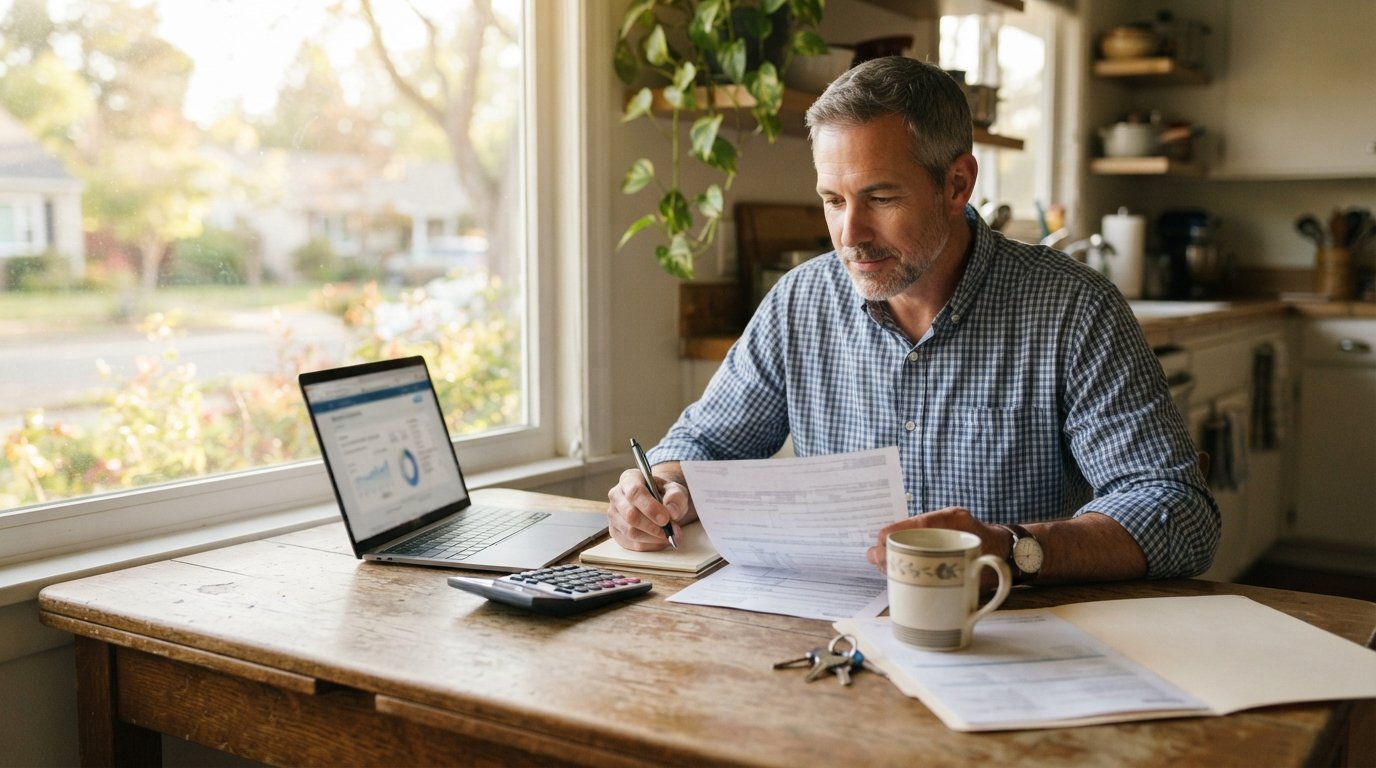
The county tax collector's notice is sitting on your kitchen counter, the due date is less than two weeks away, and your savings account will not cover the bill. This is a scenario that thousands of American homeowners face every year, and the stress is real: property tax delinquency can trigger penalties, interest, and in extreme cases, a tax lien or foreclosure. The good news is that you have more options than you might think. From payment plans with your local tax office to home equity products, personal loans, and state-run assistance programs, there are legitimate pathways to emergency cash for homeowners to pay property taxes without resorting to panic borrowing. This guide walks through each option, compares the costs and risks, and helps you choose the route that protects both your home and your financial health.
Start With the County: Payment Plans and Deferral Programs
Before you borrow a single dollar from a lender, contact your county tax collector's office. Most jurisdictions would rather set up a payment arrangement than push a homeowner into delinquency. Many counties offer installment plans that let you split the annual tax bill into monthly or quarterly payments, sometimes with a small administrative fee and modest interest. The application process is usually straightforward: you submit a request, sometimes in writing, and agree to a schedule. The key advantage is that you avoid third-party borrowing entirely and keep the debt at government-regulated rates, which are typically far lower than any commercial loan product.
Several states also offer property tax deferral programs for qualifying homeowners, including seniors, veterans, and individuals with disabilities. These programs allow you to postpone payment, with the deferred amount becoming a lien on the property that is settled when the home is sold or the owner passes away. California, for example, runs a Property Tax Postponement Program through the State Controller's Office that accepts applications during a specific window each year. Florida, Texas, and several other states have similar provisions, though eligibility rules vary widely. Check your state's Department of Revenue or your county assessor's website for details, and apply early because these programs often have limited funding and strict deadlines.
If you do not qualify for a formal deferral, ask about a hardship plan. County tax offices sometimes have discretionary authority to waive penalties or extend deadlines for homeowners facing documented hardship, such as a medical emergency or sudden job loss. Bring documentation and be persistent: a phone call and a follow-up letter can sometimes buy you the time you need without any borrowing at all.
Home Equity Options: Tapping What You Already Own
For homeowners with accumulated equity, a home equity line of credit (HELOC) or a home equity loan can be one of the least expensive ways to raise emergency cash for property taxes. Because these products are secured by your home, interest rates are typically much lower than unsecured personal loans or payday products. A HELOC works like a credit card: you draw only what you need, when you need it, and pay interest only on the outstanding balance. A home equity loan, by contrast, delivers a lump sum with a fixed rate and fixed repayment schedule, which can be easier to budget for.
The tradeoff is speed and risk. HELOCs and home equity loans require an application, a credit check, an appraisal in many cases, and closing costs. Approval can take several weeks, which may be too slow if your tax bill is due in days. More importantly, these products are secured by your home: if you fail to repay, you risk foreclosure. That is a serious consideration when the underlying obligation is a property tax bill that, on its own, would take years of delinquency to trigger a tax sale. Borrowing against your home to pay taxes can make sense if you have stable income and a clear repayment plan, but it is not a decision to make in a panic.
Reverse mortgages are another option for homeowners aged 62 and older. These allow you to convert home equity into cash without monthly payments, with the loan repaid when you sell, move out, or pass away. Reverse mortgages carry upfront costs and complex terms, so they are best explored with a HUD-approved counselor rather than as a last-minute fix.
Personal Loans and Short-Term Options: Speed Versus Cost
When the deadline is imminent and home equity is not accessible, unsecured personal loans and short-term lending products become the practical fallback. Personal loans from banks, credit unions, and online lenders typically range from $1,000 to $15,000 or more, with fixed rates and installment repayment over one to five years. For a property tax bill in the low thousands, a personal loan can spread the cost into manageable monthly payments. Approval usually takes a day or two, and funds can arrive by the next business day in many cases. Credit unions are often the most borrower-friendly source, especially if you already have a relationship with one.
For homeowners with damaged credit or an urgent same-day need, the landscape shifts toward short-term products: payday loans, cash advances, and small installment loans. These are the options most heavily marketed as emergency cash for homeowners to pay property taxes, and they are also the ones that require the most caution. Payday loans are typically under $1,000, due in full on your next payday, and carry annual percentage rates that can exceed 400 percent when annualized. Installment loans under $5,000 spread repayment over several scheduled payments, which is gentler than a single balloon payment but still expensive. If you explore this route, use a platform that connects you with multiple vetted lenders so you can compare offers rather than accepting the first one. Services like ExpressCash function as matching platforms that let you submit one request and review offers from participating lenders, which is a safer approach than responding to a single unsolicited offer. Similarly, our guide on emergency cash loans with no wait options explains how same-day and next-business-day funding works in practice, including what documentation you will need and how lender networks differ from direct lenders.
Whatever short-term product you consider, read the terms before you e-sign. Look at the APR, not just the fee per $100 borrowed. Check whether the lender reports to credit bureaus and what happens if you pay late. And confirm that the total repayment fits comfortably within your budget: a tax bill paid with a loan that you then cannot repay simply converts one financial problem into two.
Assistance Programs and Local Resources
Do not overlook homeowner assistance programs, which are often underused because eligible homeowners simply do not know they exist. The federal Homeowner Assistance Fund, created during the pandemic, has wound down in most states, but many state housing finance agencies still administer property tax relief programs, foreclosure prevention counseling, and emergency grants. Local nonprofits, community action agencies, and Area Agencies on Aging can also point you toward resources, particularly if you are a senior or a low-income homeowner.
Several categories of aid are worth investigating:
- State property tax relief programs: Many states offer homestead exemptions, circuit breaker credits, or rebates for qualifying homeowners, sometimes retroactively.
- Senior and disability deferrals: Postponement programs that let eligible homeowners delay taxes until the property is sold.
- Nonprofit hardship grants: Local charities and housing counseling agencies sometimes provide one-time grants for tax delinquencies.
- Foreclosure prevention counseling: HUD-approved counselors can negotiate with tax authorities and help you build a repayment plan.
Apply for these programs even if you think you will not qualify. The application process itself often surfaces options you did not know existed, and counselors can sometimes intervene with the county on your behalf. The key is to act before the delinquency escalates: once a tax lien is sold or a tax deed auction is scheduled, your options narrow dramatically.
Building a Repayment Plan That Actually Works
Once you have secured emergency cash for homeowners to pay property taxes, the next challenge is repaying it without falling into a new cycle of debt. Start by writing down the exact repayment terms: the amount borrowed, the interest rate, the due dates, and any fees. Then map those obligations against your income and fixed expenses. If the payment is more than you can comfortably handle, contact the lender before you miss a payment. Many lenders offer hardship programs, modified payment schedules, or deferments, but these are almost always easier to arrange before delinquency than after.
Consider setting up automatic payments from a dedicated account so you never miss a due date. If you borrowed through a short-term product, prioritize repayment above discretionary spending and avoid taking on additional debt until the balance is cleared. For homeowners who used a HELOC or home equity loan, build the repayment into your long-term budget and resist the temptation to draw more than necessary. The goal is to treat the tax bill as a one-time emergency, not the beginning of a borrowing habit.
Finally, plan ahead for next year's tax bill. Property taxes are predictable, even if they feel sudden. Divide the annual amount by twelve and set aside that sum monthly in a dedicated savings account. Homeowners with escrow accounts already do this through their mortgage payment; if you pay taxes directly, replicating that discipline on your own is the single best defense against future tax emergencies. If your income is variable, aim to set aside a larger share during strong months. A small amount of planning now can eliminate the need for emergency cash for homeowners to pay property taxes next year.
Property tax deadlines are stressful, but they are not the end of the road. Between county payment plans, state deferral programs, home equity products, personal loans, and local assistance resources, you have real choices. Evaluate them in order of cost and risk, ask for help early, and protect the asset that matters most: your home.