Emergency 300 Dollar Loan for Car Repair Deductible
An emergency 300 dollar loan for car repair deductible can get your car back on the road fast. Call 8335013363 to compare lender offers today.
By Owen Mitchell
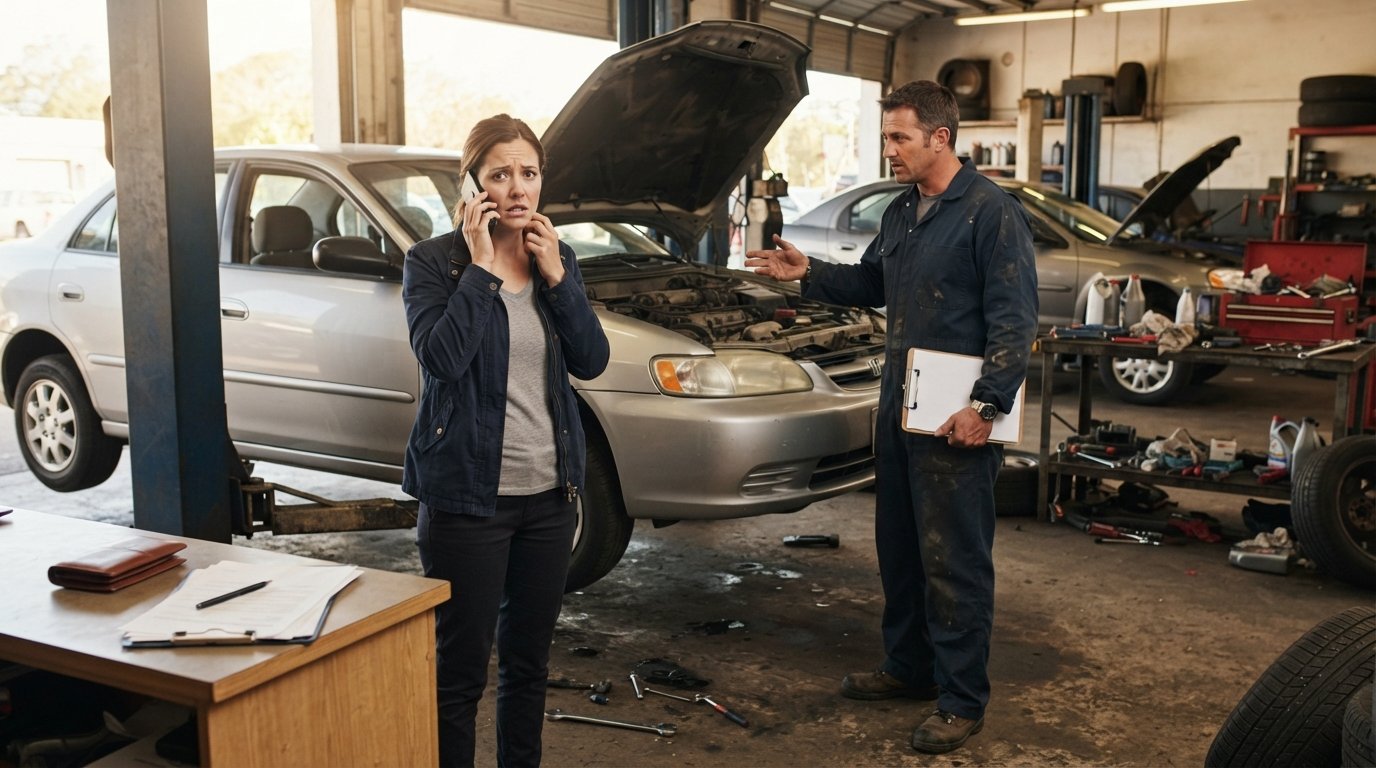
Your car breaks down on a Tuesday morning. The mechanic calls with a diagnosis and a number: your insurance deductible is 300 dollars, and you need to pay it before any repair work begins. You have a job, a bank account, and every intention of paying your bills. What you do not have is 300 dollars sitting idle in checking. This exact scenario plays out for thousands of drivers every day, and it is one of the most common reasons people search for fast, small-dollar funding. An emergency 300 dollar loan for car repair deductible purposes is a real, workable solution when you understand how it works, what it costs, and where to find it. This guide walks you through the entire process, from knowing when a small loan makes sense to comparing offers and repaying the balance without derailing your budget.
Why a 300 Dollar Deductible Creates a Real Cash Crunch
Insurance deductibles are designed to keep premiums affordable, but they shift a fixed cost onto you at the worst possible moment. A 300 dollar deductible is modest compared with the 500 or 1,000 dollar deductibles many policies carry, yet it still arrives as a lump sum when your car is undrivable and your schedule is already disrupted. Most households in the United States cannot absorb an unexpected 300 dollar expense without adjusting something else, which is why so many drivers look for a targeted small loan rather than draining savings or missing other obligations.
Timing makes the problem worse. Repair shops typically will not release a vehicle or begin covered work until the deductible portion is settled. If your car is your commute, your childcare solution, or your work vehicle, every day without it compounds the financial damage. That urgency is exactly what short-term lending products are built to address, provided you borrow deliberately and repay on schedule.
It also helps to separate the deductible from the total repair bill. Your insurer covers the rest of the covered claim, so your out-of-pocket obligation stays fixed at 300 dollars. That predictability is an advantage: you know the exact amount you need, which makes it easier to choose a loan size, avoid over-borrowing, and plan a repayment date with confidence.
What Counts as an Emergency 300 Dollar Loan for Car Repair Deductible Costs
When people search for an emergency 300 dollar loan for car repair deductible expenses, they are usually describing a small, fast, short-term loan with a single clear purpose. Several loan types can fit that description, and the right one depends on your income, your timeline, and how quickly you can repay.
A payday loan or cash advance is the classic option for amounts under 1,000 dollars. These are small, no-collateral loans backed by your next paycheck, typically repaid in a single payment or a short series of payments. An installment loan spreads repayment across a set number of scheduled payments, which can make a 300 dollar balance easier to manage if your budget is tight. A small personal loan may also work, though personal loans often start at 1,000 dollars or more, making them a better fit if you want to fold in other expenses like a rental car or a follow-up inspection.
Here is a quick comparison of the options that most commonly fit a 300 dollar car repair deductible:
- Payday loan or cash advance: Usually under 1,000 dollars, short term, no collateral, repaid from your next income deposit.
- Installment loan: Typically under 5,000 dollars, repaid in scheduled payments over a longer period, which lowers each individual payment.
- Small personal loan: Often 1,000 dollars or more, useful if you want extra cushion beyond the deductible itself.
- Credit union or employer advance: Not always available, but worth checking before you borrow from a higher-cost source.
Each option carries different costs and repayment structures, and none of them is free money. Short-term loans frequently carry very high annual percentage rates and fees, and they are intended to cover temporary financial gaps, not to serve as a long-term financial strategy. The goal is to match the smallest, shortest, cheapest product to your specific 300 dollar need and then repay it on time.
How to Apply for Fast Funding Through a Loan Connection Service
If you want to compare multiple lenders without filling out a dozen separate applications, a connection service is often the fastest route. CashLoanFunded operates as a free loan matching service, not a direct lender. You submit one online request, and independent third-party lenders in the network review it and may present offers. That structure saves time and keeps your search organized when you are already dealing with a broken car.
The process typically follows three steps. First, you submit a request with basic information: your name, address, date of birth, phone number, banking details, and Social Security number. Second, you check the offers that come back, reading the APR, fees, and repayment terms on each one. Third, you e-sign the terms with the lender you choose and receive your money, potentially as soon as the next business day after approval. The entire online request usually takes under five minutes, and you are never obligated to accept any offer.
A few practical preparations make the process smoother. Have your most recent pay stub or proof of income ready, confirm your bank account is in good standing with no negative transaction history, and decide in advance that you will borrow only what the repair requires. If you are exploring options in a specific region, resources like this guide to emergency loans in Miami Florida show how local availability and state rules can shape which offers you see.
Eligibility Basics: Income Matters More Than Perfection
Many drivers assume they cannot qualify because of past credit trouble. In reality, the criteria for these smaller loans center on your ability to repay, not a flawless credit report. You generally need to be at least 18 years old, have valid identification, show a stable source of income, and maintain a bank account. Applicants with bad credit, prior repossession, or a bankruptcy history can still be considered if they meet the income criteria.
That said, credit is not irrelevant. Applying for a loan may involve a credit check, and that inquiry can affect your credit score. Missing or late payments can damage it further, and late payments often trigger additional fees and higher interest rates. Treat the loan as a short bridge, not a habit, and protect your credit by repaying exactly as agreed.
Availability also varies by state. Loan amounts, terms, and even whether a product can be offered at all are subject to state regulations and individual lender criteria. Before you commit, confirm that the offer in front of you complies with your state's rules and that you understand every fee attached to it.
Comparing Offers Without Getting Burned
Speed should never come at the cost of clarity. When offers arrive, compare them on the numbers that actually affect your wallet, not on how fast the money can land. A lower advertised fee can still cost more overall if the repayment term is shorter or the APR is higher.
Use this checklist as you review each offer:
- Find the APR and the total finance charge, not just the flat fee.
- Confirm the exact repayment date and whether the payment is automatic.
- Check for prepayment penalties if you plan to pay early.
- Verify the lender's contact information and read the full terms before signing.
- Make sure the total repayment fits comfortably inside your next few paychecks.
If a lender pressures you to sign immediately or refuses to provide written terms, walk away. Legitimate lenders disclose costs in writing and give you time to review. Reputable connection platforms also make clear that they are not the lender and do not control the final terms, which is a sign of transparency rather than a red flag. When you are ready to explore short-term options through a network of third-party lenders, services like AdvanceCash let you submit a single request and compare what comes back.
Repaying a 300 Dollar Loan Without Derailing Your Budget
The loan solves Tuesday's problem, but repayment is where the real financial outcome is decided. A 300 dollar balance is small enough to retire quickly if you plan for it. Start by identifying the exact date your payment is due and the exact amount, then set aside part of each paycheck between now and then.
If your budget is tight, look for small offsets: a temporary pause on subscriptions, one week of packed lunches, or a modest overtime shift. Paying early, when the lender allows it without penalty, reduces the total interest you owe and closes the gap faster. If you genuinely cannot pay on time, contact the lender before the due date. Many lenders offer options, and proactive communication is far better than a missed payment that triggers late fees and credit damage.
Finally, treat the experience as a data point. If a 300 dollar car repair deductible nearly broke your month, that is a signal to build a small emergency fund over the next several months. Even 500 dollars set aside can turn the next surprise into an inconvenience instead of a crisis, and it reduces your reliance on borrowed money going forward.
When a Small Loan Is the Wrong Tool
An emergency 300 dollar loan for car repair deductible costs is a reasonable tool in specific circumstances: you have stable income, you can repay within the loan term, and you have no cheaper option available. It becomes the wrong tool when the repair bill is only the first of several problems, when your income is unstable, or when you would need a new loan to repay the old one. In those cases, talk to the repair shop about payment plans, ask your insurer about deductible financing or payment arrangements, or explore assistance programs through community organizations.
Short-term loans carry high APRs for a reason: they are priced for speed and convenience, not for long-term borrowing. Using them sparingly, for genuine temporary gaps, keeps them from becoming a recurring expense. Used carelessly, they can turn a 300 dollar problem into a much larger one. The difference is almost entirely in how deliberately you borrow and how reliably you repay.
With the right preparation, a single online request, and a clear repayment plan, a small emergency loan can get your car back on the road and your budget back on track. Know your number, compare your offers, and borrow only what the deductible requires.